


Autoliv (ALV) has just released new figures, and they were not quite what the market wanted. Third quarter revenue held roughly steady while higher costs squeezed profitability and weighed on sentiment.
Recent trading suggests Autoliv’s momentum has cooled. The share price is down 7.1% over the past 90 days and 5.5% year to date, even though the 3 year total shareholder return of 37.3% and 5 year total shareholder return of 36.0% still point to a stronger longer term record.
Spot undervalued peers facing similar margin pressure by scanning our curated list of 29 high quality undervalued stocks across the wider auto and manufacturing space.Autoliv looks like a solid safety supplier under temporary margin strain. The stock has slipped on those cost pressures. The real issue now is whether that recent weakness already reflects fair value.
Most Popular Narrative: 14% Undervalued
Against the latest close at $115.32, the most followed narrative pins Autoliv’s fair value near $134.81. This frames the recent share pullback as a valuation gap rather than a broken business story.
Recent success with new product launches in China and strengthening relationships with major Chinese OEMs now lines up with China sales growing more than 40 percentage points faster than local light vehicle production and rising to 55% of Autoliv’s China mix, which supports the view that higher safety content and deeper local penetration can continue to lift revenue and earnings quality.
See why 21 investors see Autoliv as 14% undervalued.
Result: Fair Value of $134.81 (UNDERVALUED)
Still, the Autoliv narrative leans heavily on China and India continuing to outperform, while 2026 raw material headwinds of about US$110 million remain a clear pressure point.
Find out about the key risks to this Autoliv narrative.
Another View On Autoliv’s Valuation
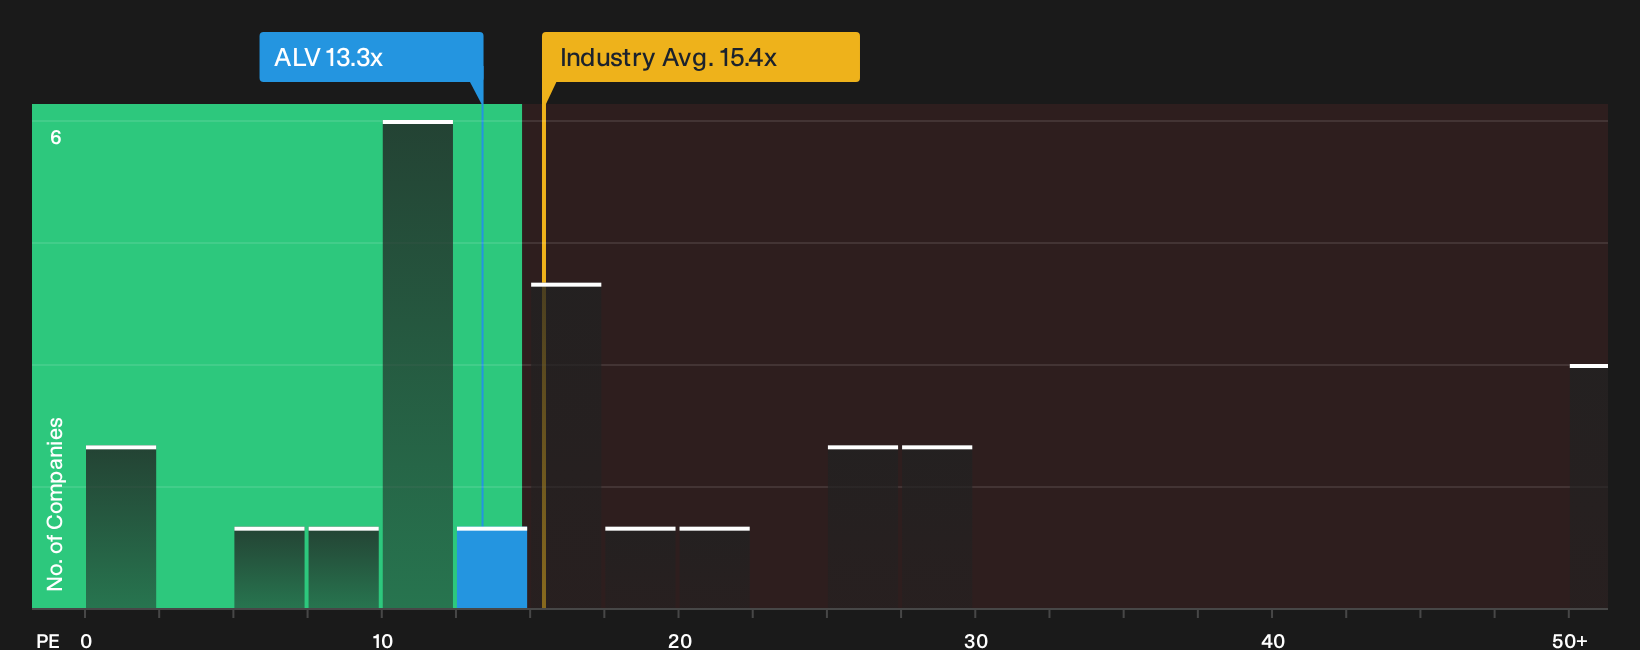
On simple ratios, Autoliv looks more grounded than the bullish fair value story suggests. The stock trades on a P/E of 13.3x, in line with its 13.3x fair ratio, yet below the US Auto Components sector at 15x and a 16.9x peer average. That gap can point to either a margin of safety or a warning that expectations stay muted. Which side of that trade do you think it reflects?
See what the numbers say about this price in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Autoliv after all that detail is helpful but your capital is on the line, so move fast and weigh both sides of the story using 2 key rewards and 2 important warning signs.
Looking for more Autoliv-sized investment ideas?
Do not stop with Autoliv. Use the Simply Wall St screener to quickly surface fresh opportunities before others move first and lock in the most attractive setups.
- Target resilient compounding potential by focusing on businesses with dependable cash flows and healthy finances through our list of solid balance sheet and fundamentals (24 results).
- Zero in on potential mispricings by scanning for quality companies that screens flag as attractively valued using the 29 high quality undervalued stocks.
- Prioritise sleep-at-night holdings by filtering for businesses with lower measured risk scores through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com