


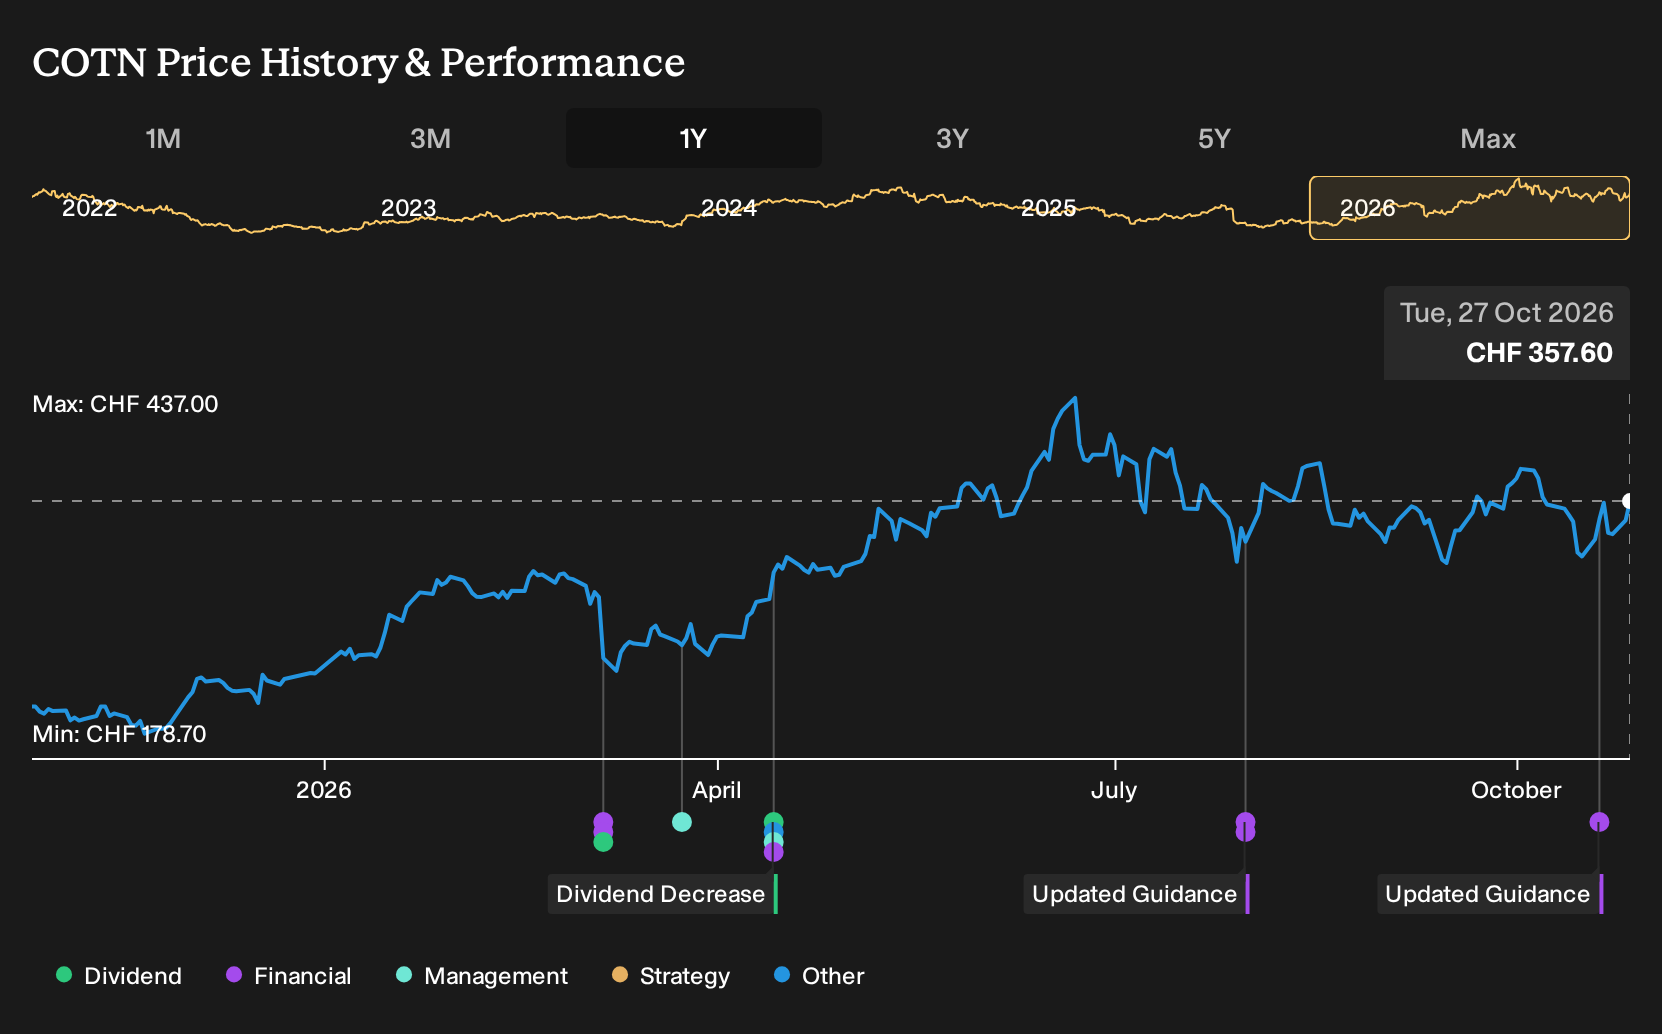
- Comet Holding AG issued earnings guidance for fiscal 2026, indicating expected net sales in a range of CHF 570 million to CHF 590 million.
- This explicit net sales corridor gives investors a clearer view of how Comet Holding sizes upcoming demand and plans capacity for its technologies.
- The focus now turns to how Comet Holding's updated 2026 net sales guidance could influence the broader investment narrative around the business.
Compare how Comet Holding's 2026 sales outlook stacks up against peers by evaluating it alongside 195 high quality undervalued stocks, which is built around resilient balance sheets and cash flows.
Comet Holding Investment Narrative Recap
To own Comet Holding, you need to be comfortable with a business tied closely to semiconductor and industrial demand cycles, while also funding heavy product and regional expansion. The 2026 net sales corridor of CHF 570 to 590 million frames what management currently sees as achievable capacity, but it does not change the fact that the key near term swing factor remains how quickly new tools gain traction.
The biggest operational risk still sits in slower customer adoption and price pressure, at the same time as Comet continues to invest in Synertia, CA20 and Malaysia. If those projects ramp more gradually or face further testing delays, margin pressure and already thin 3.3% profitability could stay in focus. The new guidance does not remove that execution risk in the short run.
The most relevant reference point for this guidance is Comet Holding’s earlier push into Malaysia, which is aimed at higher manufacturing efficiency and better scalability. That build out matters because the 2026 sales range implicitly assumes the group can produce and ship at those levels without major bottlenecks or cost overruns.
Those Malaysia investments, together with Synertia and CA20, still anchor the main potential catalysts. Efficient execution could help support net margins and make the CHF 570 to 590 million sales corridor easier to absorb operationally. If ramp up costs stay heavy or pricing gets tougher, investors will likely focus less on the top line range and more on the quality of earnings that come with it.
Comet Holding's narrative projects CHF 908.5 million revenue and CHF 264.2 million earnings by 2029. This implies 24.6% yearly revenue growth and an earnings increase of about CHF 248.6 million from CHF 15.6 million today.
Uncover why Comet Holding's fair value indicates a 52% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate take on Comet Holding leans hard into execution risk at Penang. The most cautious analysts were pencilling in CHF 913.5 million of 2029 revenue and CHF 215.2 million of earnings before this guidance, yet still saw only a modest upside. That shows how sharply opinions can differ; it can help to review several competing narratives yourself.
Explore 2 other Comet Holding fair value estimates, including one that suggests it could be worth just CHF522.30!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Comet Holding research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Comet Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Comet Holding's overall financial health at a glance.
Looking for more Comet Holding style investment ideas?
Once you have formed a view on Comet Holding, it can help to compare it with a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If you care most about quality at a reasonable entry point, you can review a hand picked set of candidates through the 195 high quality undervalued stocks.
- If capital preservation and stability sit higher on your list, consider starting with the 223 resilient stocks with low risk scores that filters for resilient businesses with lower risk scores.
- If balance sheet strength is non negotiable for you, broaden your research with the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com