


Ramelius Resources (ASX:RMS) has put fresh operational numbers on the table ahead of its Q1 2027 earnings release, reporting September quarter output of 48,839 ounces of gold at an all-in sustaining cost of A$2,656 per ounce.
The fresh production update lands after a mixed run for Ramelius Resources, with the share price up 10.38% over 90 days but down 17.02% year to date. Long term total shareholder returns of 126.70% over three years suggest momentum has built over time even as shorter term moves remain choppy.
Spot fresh momentum in gold producers like Ramelius Resources by scanning our hand-picked 35 elite gold producer stocks tied to recent output, cost trends, and upcoming earnings catalysts.After a strong three year run and a choppy year to date, the real tension for Ramelius Resources now sits in the valuation. Has most of the easy upside already played out, or is the market still underpricing it?
Most Popular Narrative: 63% Undervalued
Ramelius Resources last closed at A$3.51, while the most followed narrative on the stock assigns a fair value of A$9.47, which frames the current price as a steep discount in the eyes of that long term holder.
I've been a share holder of this company for over 15 years, and seen the share price at 7c. With incremental share purchases, I've accumulated a 6 figure holding. It's been one of my set and forget 'Buffet' stocks. Each read of the annual report maintains my faith in its growth strategy, where a disciplined board of directors with a very professional management team have executed a promised vision.
I've seen the share price punch through $5 and I've taken some profit. However, the journey to greater riches is still on, with continued exploration, acquisitions and sensible operations, so while I have time before retirement, I'll keep riding the outlook.
See why 6 investors see Ramelius Resources as 63% undervalued.
Result: Fair Value of A$9.47 (UNDERVALUED)
Still, the bullish long term narrative on Ramelius Resources leans heavily on gold prices and consistent output. Weaker commodity markets or operational setbacks could quickly challenge it.
Find out about the key risks to this Ramelius Resources narrative.
Another View On Ramelius Resources
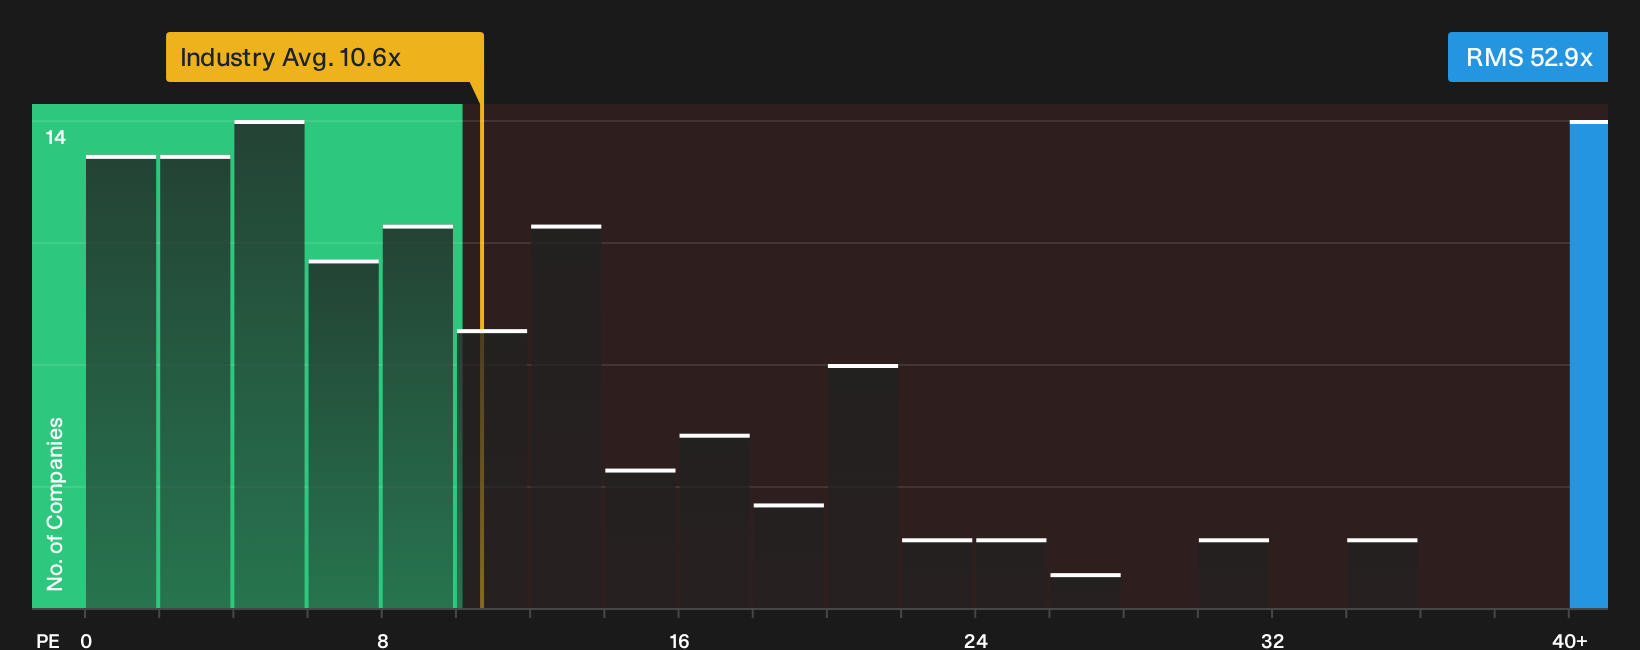
There is a very different message coming from the market multiples. Ramelius Resources trades on a P/E of 52.9x, compared with 13.7x for peers and 10.6x for the broader Australian metals and mining group. The fair ratio sits at 27x. That gap points to real valuation risk if earnings forecasts or sentiment cool.
To see how that richer P/E and the fair ratio fit into a fuller breakdown, take a closer look at our valuation workup on Ramelius Resources, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Ramelius Resources so far. If you want to move fast and base your stance on the same core facts, start with the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Ramelius Resources?
If you only focus on Ramelius Resources, you risk missing other opportunities that match your goals and risk tolerance across quality, yield, and upside potential.
- Target potential mispricing by scanning the 2 high quality undervalued stocks and compare businesses that combine quality fundamentals with prices that may not fully reflect them.
- Strengthen portfolio resilience by reviewing the list of solid balance sheet and fundamentals (12 results) and focus on companies with cleaner debt profiles and healthier financial footing.
- Put your capital to work by assessing the 4 dividend fortresses that offer higher income streams alongside business models built around regular cash returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com