


- Mondelez International recently expanded its snacking portfolio with CHIPS AHOY! Minis Drizzled cookies in caramel and fudge varieties and launched RITZ Gluten Free Crackers, adding new options in bite size indulgence and gluten free formats.
- The fresh mix of portion friendly sweets and certified gluten free crackers points to Mondelez International leaning into more tailored, occasion based snacking that can support brand relevance with consumers who want both indulgence and inclusion.
- We will look at how Mondelez International's investment narrative intersects with its gluten free RITZ launch and broader snacking innovation.
Mondelez International Investment Narrative Recap
To own Mondelez International, you need to believe that global snacking demand, brand strength across Oreo, RITZ and CLIF, and steady reinvestment in marketing and supply chain can support consistent earnings over time. The recent product launches in gluten free and portion friendly treats look incremental rather than transformational, so they do not materially change the near term story.
The key short term swing factor still sits with input costs and consumer elasticity. Cocoa and other commodities, together with any renewed volume softness in North America, remain the pressure points. If lower income shoppers cut back or trade down again, the push into premium indulgence could meet more resistance and slow margin progress.
The RITZ Gluten Free Crackers launch ties directly into the catalyst around premium indulgence and better for you snacking. It extends an existing power brand into a certified gluten free segment that can support mix, pricing and shelf space, provided shoppers accept the product as close enough to the classic RITZ experience.
For you as an investor, the useful question is execution. Watch how rapidly Mondelez International secures distribution, repeat purchase and retailer support for gluten free RITZ. Strong uptake would support the view that reinvestment into new formats and health oriented ranges can help manage commodity volatility and any slowdown in traditional biscuit and chocolate categories.
Mondelez International's narrative projects US$43.2b revenue and US$4.7b earnings by 2029. This rests on analysts assuming 2.8% yearly revenue growth and an earnings increase of about US$1.2b from US$3.5b today.
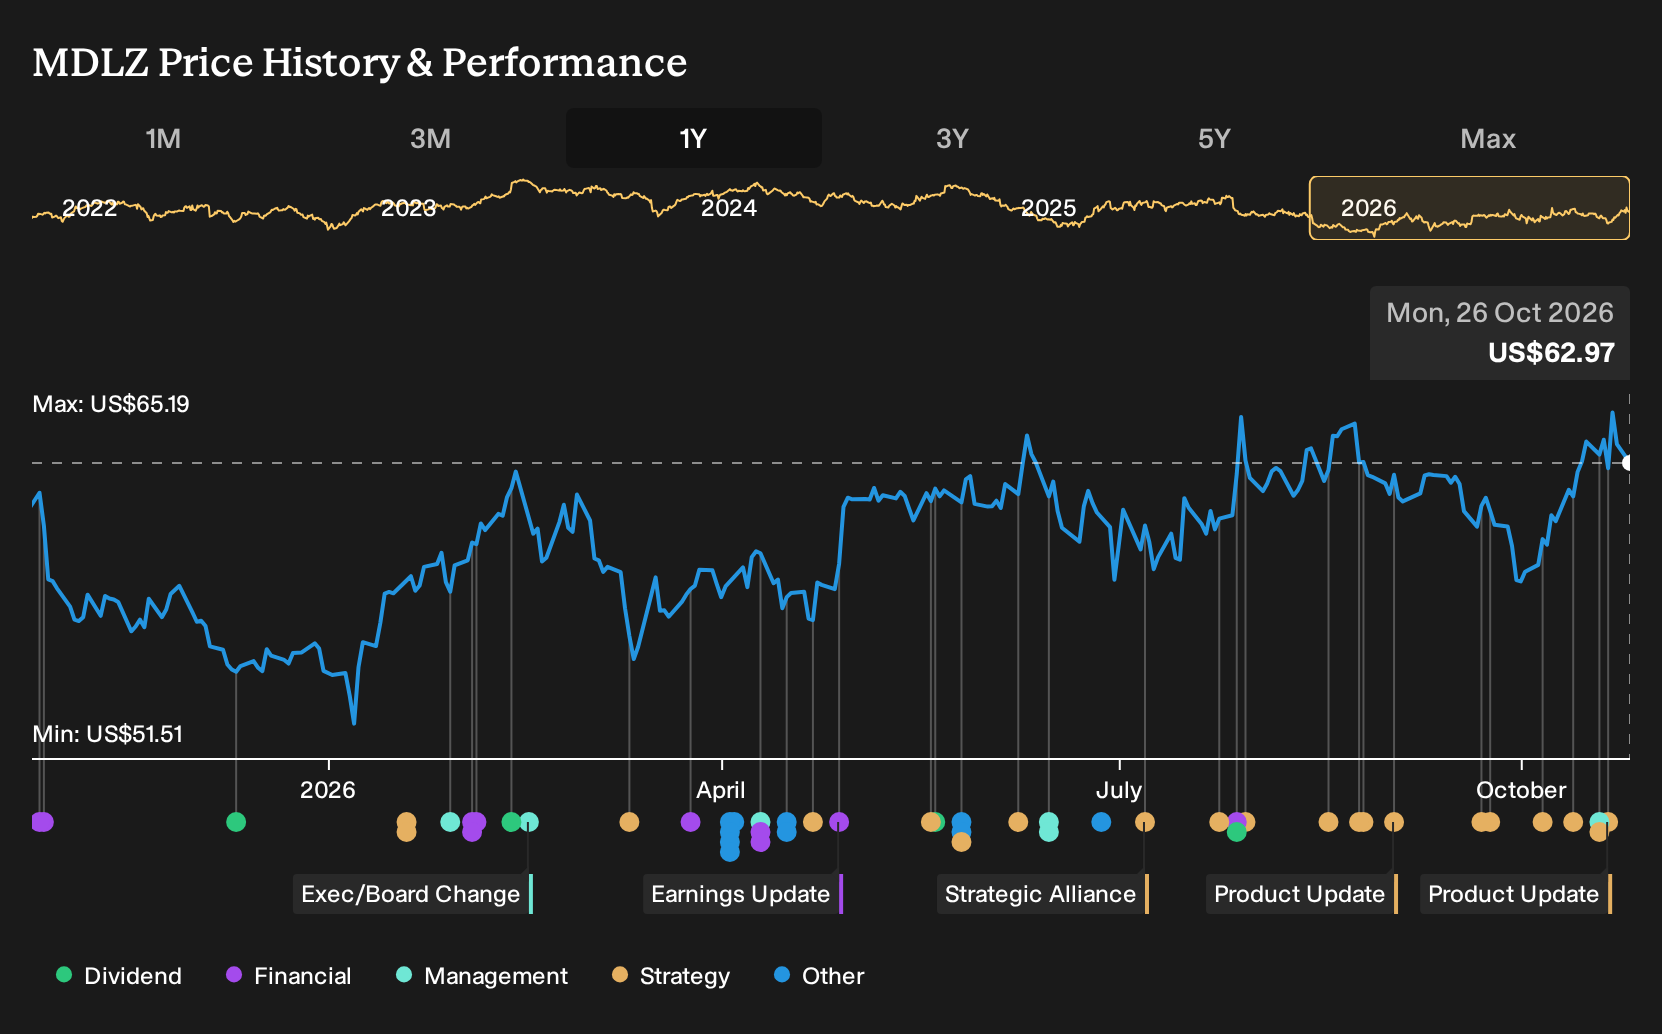
Discover why Mondelez International's fair value suggests a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit far apart, from about US$69 to roughly US$126, which shows how sharply opinions on Mondelez International can diverge. When you layer on cocoa cost uncertainty and new product launches in gluten free and portion controlled treats, you can end up with very different views on how resilient future performance could be. Readers should review multiple community viewpoints before deciding where they stand.
Explore another Mondelez International fair value estimate, including one that suggests it could be worth just $69.13.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mondelez International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mondelez International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mondelez International's overall financial health at a glance.
Looking for more Mondelez International style ideas?
If the Mondelez International story has sharpened your thinking on brands, pricing power and cash generation, it can help to line it up against other businesses that share some of those traits. The Simply Wall St Screener lets you filter for balance sheet strength, income potential and quality fundamentals so you can build a watchlist that actually matches your risk tolerance and goals.
- For investors who care most about staying power and financial resilience, start with a 30 resilient stocks with low risk scores that screens for companies with comparatively lower risk scores.
- If income is a priority, you can focus on payout strength by reviewing a set of 5 dividend fortresses that combine higher yields with an emphasis on stability.
- Those hunting for quality that the wider market may be ignoring might prefer a 21 high quality undiscovered gems that surfaces under followed businesses with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com