


Fresh commentary around SRG Global (ASX:SRG) is circling its A$5b work in hand and A$11b project pipeline, with investors weighing revenue visibility benefits against the risk of tighter margins on future contracts.
SRG Global’s A$3.42 share price comes after a mixed pattern of short term moves, with the stock down about 15% on a 30 day share price return yet still showing a positive 90 day share price return of roughly 2%. At the same time, the year to date share price return of nearly 15% and a 1 year total shareholder return of about 24% point to momentum that has been far stronger over a multi year stretch where total shareholder returns have been many times the starting value.
Compare SRG Global's contract driven story with other infrastructure and capital goods plays by scanning our hand picked 42 power grid technology and infrastructure stocks that is aligned with long term project backlogs and asset heavy business models.
Recent trading leaves SRG Global looking caught between a business anchored by long term contracts and a share price that has cooled. Is this pullback a reset in sentiment, or a signal about valuation risk ahead?
Most Popular Narrative: 21% Undervalued
SRG Global’s most followed valuation storyline puts fair value at A$4.32 per share, ahead of the last close at A$3.42. This frames the recent share price pullback as a potential gap between sentiment and the long term contract profile.
SRG Global's capital light model, with capex around 2% of revenue, EBITDA to cash conversion of 101% in FY26 and a move to a net cash position with close to A$300m in available liquidity, creates room for self funded growth and future earnings accretion from potential bolt on acquisitions.
See why 23 investors see SRG Global as 21% undervalued.
Result: Fair Value of A$4.32 (UNDERVALUED)
Still, SRG Global’s reliance on government infrastructure budgets and the execution risk on large water and marine contracts could quickly challenge the current undervaluation story.
Find out about the key risks to this SRG Global narrative.
Another View: What SRG Global’s P/E Is Saying
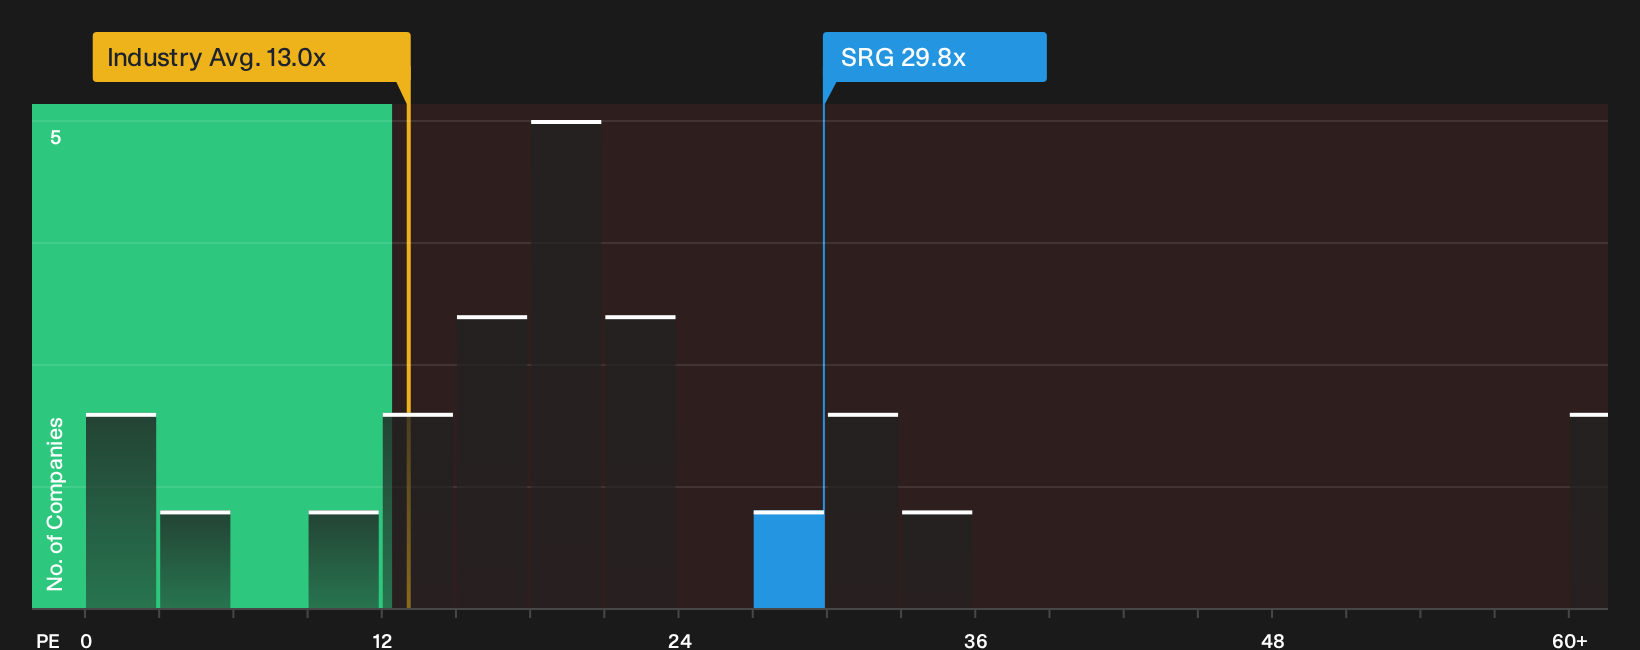
On cash flow and analyst targets, SRG Global screens as undervalued. Look at the P/E ratio though and the picture changes. The stock trades on 29.8x earnings, above both the estimated fair ratio of 22.9x and peer averages of 27.6x and 13x globally. This points to less room for error if growth cools.
That premium raises a simple question for investors. Is the contract book and earnings profile strong enough to keep justifying a higher multiple? Or is there more downside risk if sentiment shifts toward cheaper construction stocks. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of signals around SRG Global point in different directions, so move quickly, review the underlying numbers, and weigh both the upside and the caution flags through 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond SRG Global?
If you only stop at SRG Global, you risk missing other opportunities that fit your style, your risk limits, and your income goals.
- Tap into potential turnarounds by scanning 23 elite penny stocks with strong financials that match your tolerance for higher volatility with disciplined financial filters.
- Zero in on quality at a sensible price with our hand picked 2 high quality undervalued stocks that filters for strong fundamentals and attractive valuations.
- Strengthen your income stream by reviewing the 4 dividend fortresses that focuses on higher yielding businesses with robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com