


- Aon has appointed long-time executive Leonora Siccardi as Global Chief Execution Officer for Risk Capital and Human Capital, a new role created to align strategy, investment priorities and delivery across its risk, people and analytics businesses.
- Siccardi’s dual responsibilities, combining her new execution remit with existing claims and client solutions roles, concentrate decision making around how Aon develops, commercializes and implements new capabilities across its risk and human capital platforms.
- This development raises questions about how Aon’s investment narrative could be influenced by Siccardi’s expanded execution role across Risk Capital and Human Capital.
Aon Investment Narrative Recap
To own Aon, you need to be comfortable with a story that leans on fee based risk and human capital services, and a heavy execution load around USI, NFP and analytics. The near term focus sits on integrating these pieces while carrying a higher debt balance, with less help from buybacks as a support for the share price.
Siccardi’s execution role looks more like plumbing than a clear short term catalyst. It may help tighten how Aon turns strategy into delivered products across Risk Capital and Human Capital, but the key swing factor still rests on whether USI integration, synergy delivery and middle market expansion track expectations without disrupting organic growth.
The US$17b USI acquisition remains the operational announcement that matters most against this leadership change. Management is targeting US$3.3b of revenue and US$1.2b of adjusted EBITDA from USI on a fully synergized basis, with US$395m of net EBITDA synergies split between revenue and cost actions across defined workstreams.
Investors watching Aon will likely tie Siccardi’s new remit directly to whether those USI plans translate into cleaner integration, consistent client delivery and better use of analytics across Risk Capital and Human Capital. Execution risk around middle market buildout, E&S expansion and higher leverage is already front of mind, so any operational progress here could shape how the existing catalyst set is viewed.
What Aon’s Consensus Numbers Assume
Aon's current analyst narrative links Siccardi’s expanded remit directly to a fairly demanding set of forecasts. Consensus expects revenues of US$23.1b and earnings of US$4.1b by 2029, with an assumed 9.5% annual revenue growth rate over the next three years. That earnings figure sits above the US$3.9b of earnings today, implying an increase of roughly US$0.2b that has to come through execution on USI integration, NFP, middle market expansion and the broader analytics buildout.
Aon's narrative projects US$23.1b revenue and US$4.1b earnings by 2029. This requires 9.5% yearly revenue growth and an earnings increase of about US$0.2b from US$3.9b.
Uncover how Aon's fair value indicates a 17% potential upside to its current price, which could narrow quickly if execution meets expectations.
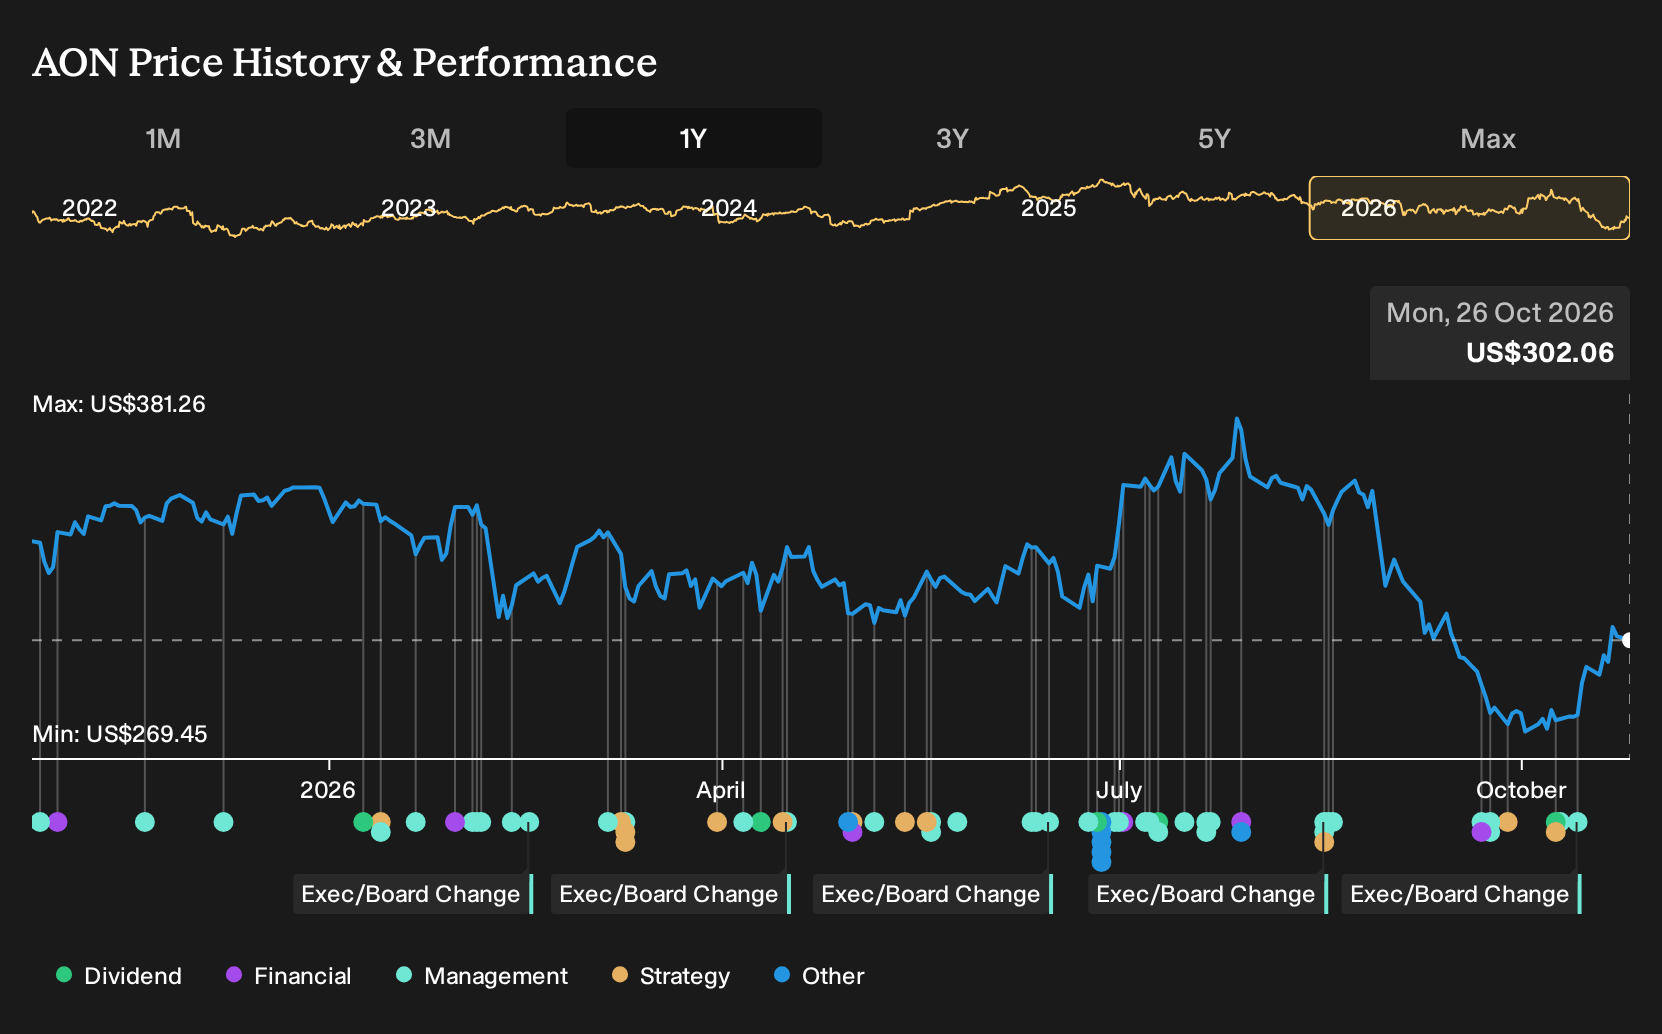
Exploring Other Perspectives
One alternate angle you might explore is the bullish view on Aon’s middle market buildout. The most optimistic analysts were pencilling in about US$25.3b of revenue and US$4.1b of earnings by 2029 before this appointment. That outlook leans on faster execution and heavier analytics adoption, which Siccardi’s new role could meaningfully reshape.
Explore another Aon fair value estimate, including one that suggests there may be as much as 46% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Aon research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aon. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Aon's overall financial health at a glance.
Looking For More Ideas Beyond Aon?
If you want to pressure test your Aon view against other opportunities, a quick scan through the Simply Wall St Screener can help you line up alternatives with similar financial traits or very different risk profiles.
- For investors who care most about financial resilience, filter for companies with stronger balance sheets and steady fundamentals through this curated list of solid balance sheet and fundamentals (24 results).
- If value is your priority, compare Aon with a broader pool of potentially mispriced opportunities by running through a focused set of 29 high quality undervalued stocks that pair quality metrics with more modest expectations.
- Income focused readers can scan for payout heavy candidates by checking a tailored group of 5 dividend fortresses that combine higher yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com