


Industry forecasts pointing to a larger global boulder clearance services market have pulled investor attention back to Orica (ASX:ORI), given its role supplying blasting and rock-breaking solutions across mining, construction, and infrastructure projects.
Recent trading has been uneventful on a weekly and monthly view. However, Orica’s A$22.85 share price still sits against a backdrop where the year to date share price return has slipped 6.3%, while the 1 year total shareholder return of 6.0% and 3 year total shareholder return of 69.1% point to a longer stretch of stronger sentiment that investors are now weighing against the fresh industry growth story.
Scan beyond Orica to compare it with 1 power grid technology and infrastructure stocks, which could also benefit from long term infrastructure and construction spending.So after a softer year to date move and a much stronger three year run, is most of Orica’s value already reflected in A$22.85, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 12% Undervalued
On Simply Wall St’s most followed narrative, Orica’s fair value sits at A$25.91 against the recent A$22.85 close. This frames the current price as a discount that hinges on execution in digital solutions, chemicals and cost savings.
The main factor that needs to go right is continued execution on cost reduction, capital discipline and portfolio tilt toward gold, copper and specialty mining chemicals, while managing supply incidents and thermal coal volume headwinds.
The current valuation implies the share price does not fully reflect the view that Orica is undervalued and that higher quality earnings from digital solutions, specialty chemicals and lower emissions assets are becoming a larger share of the business.
See why 26 investors see Orica as 12% undervalued.
Result: Fair Value of A$25.91 (UNDERVALUED)
Still, the story can fray quickly if debottlenecking and third party supply for fully utilised cyanide plants slip, or if recent acquisitions underdeliver on cross selling and cost savings.
Find out about the key risks to this Orica narrative.
Another View: Orica Looks Expensive On Earnings
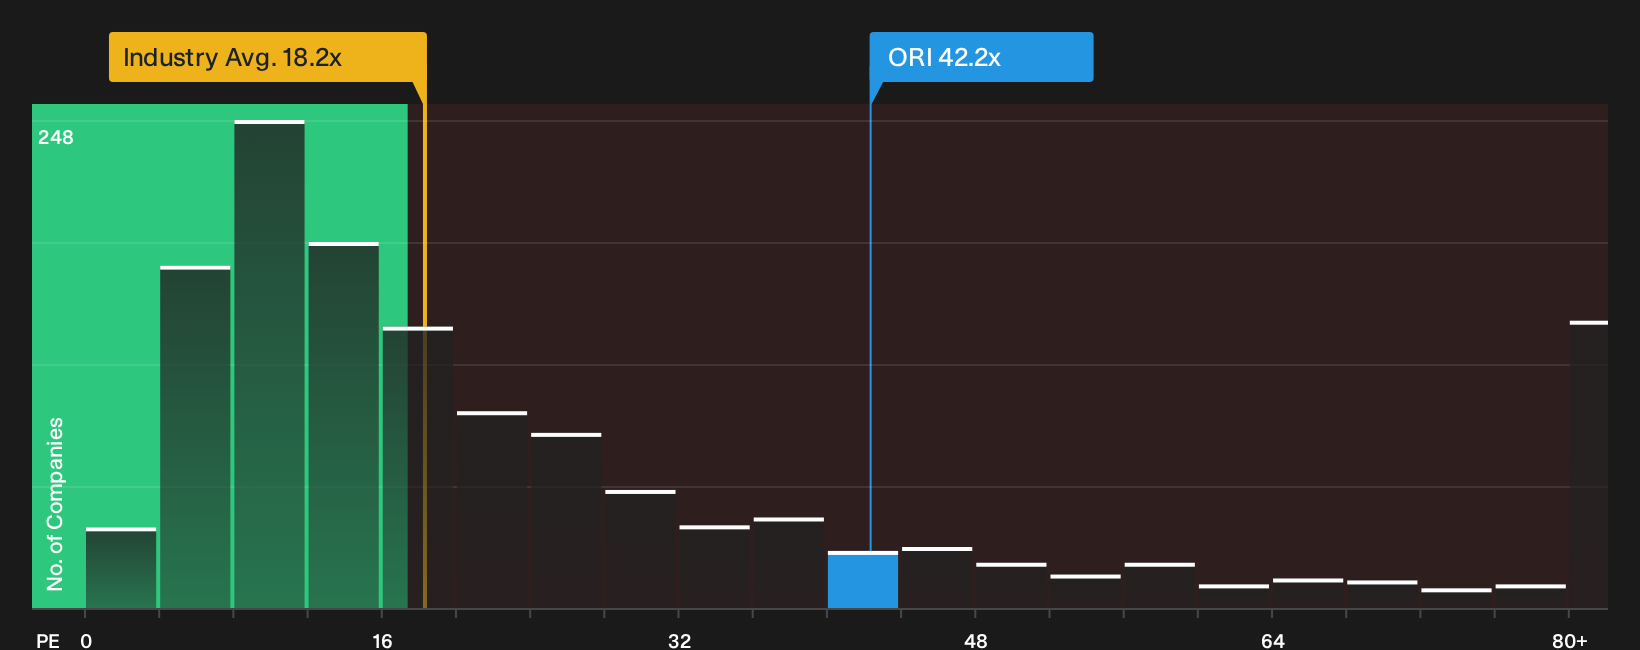
The DCF based fair value of A$25.91 presents Orica as undervalued. A quick check against earnings multiples tells a different story. On a P/E of 42.2x versus a peer average of 26.6x, a global chemicals mark of 18.2x and a fair ratio of 19.2x, the stock carries a rich earnings tag that could amplify any disappointment. Where does that leave you in deciding which signal to focus on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Orica feels familiar, consider acting while the data is fresh and form your own view by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Orica?
You have fresh context on Orica. While that is front of mind, widen your opportunity set and pressure-test your portfolio against other potential candidates.
- Target resilient cash generators with healthy cushions by scanning a list of solid balance sheet and fundamentals (12 results) that filters for sturdier fundamentals.
- Hunt for mispriced opportunities by reviewing a 2 high quality undervalued stocks that highlights companies where quality and price appear out of sync.
- Pursue future leaders early by checking a 15 high quality undiscovered gems that surfaces strong fundamentals before they are widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com