


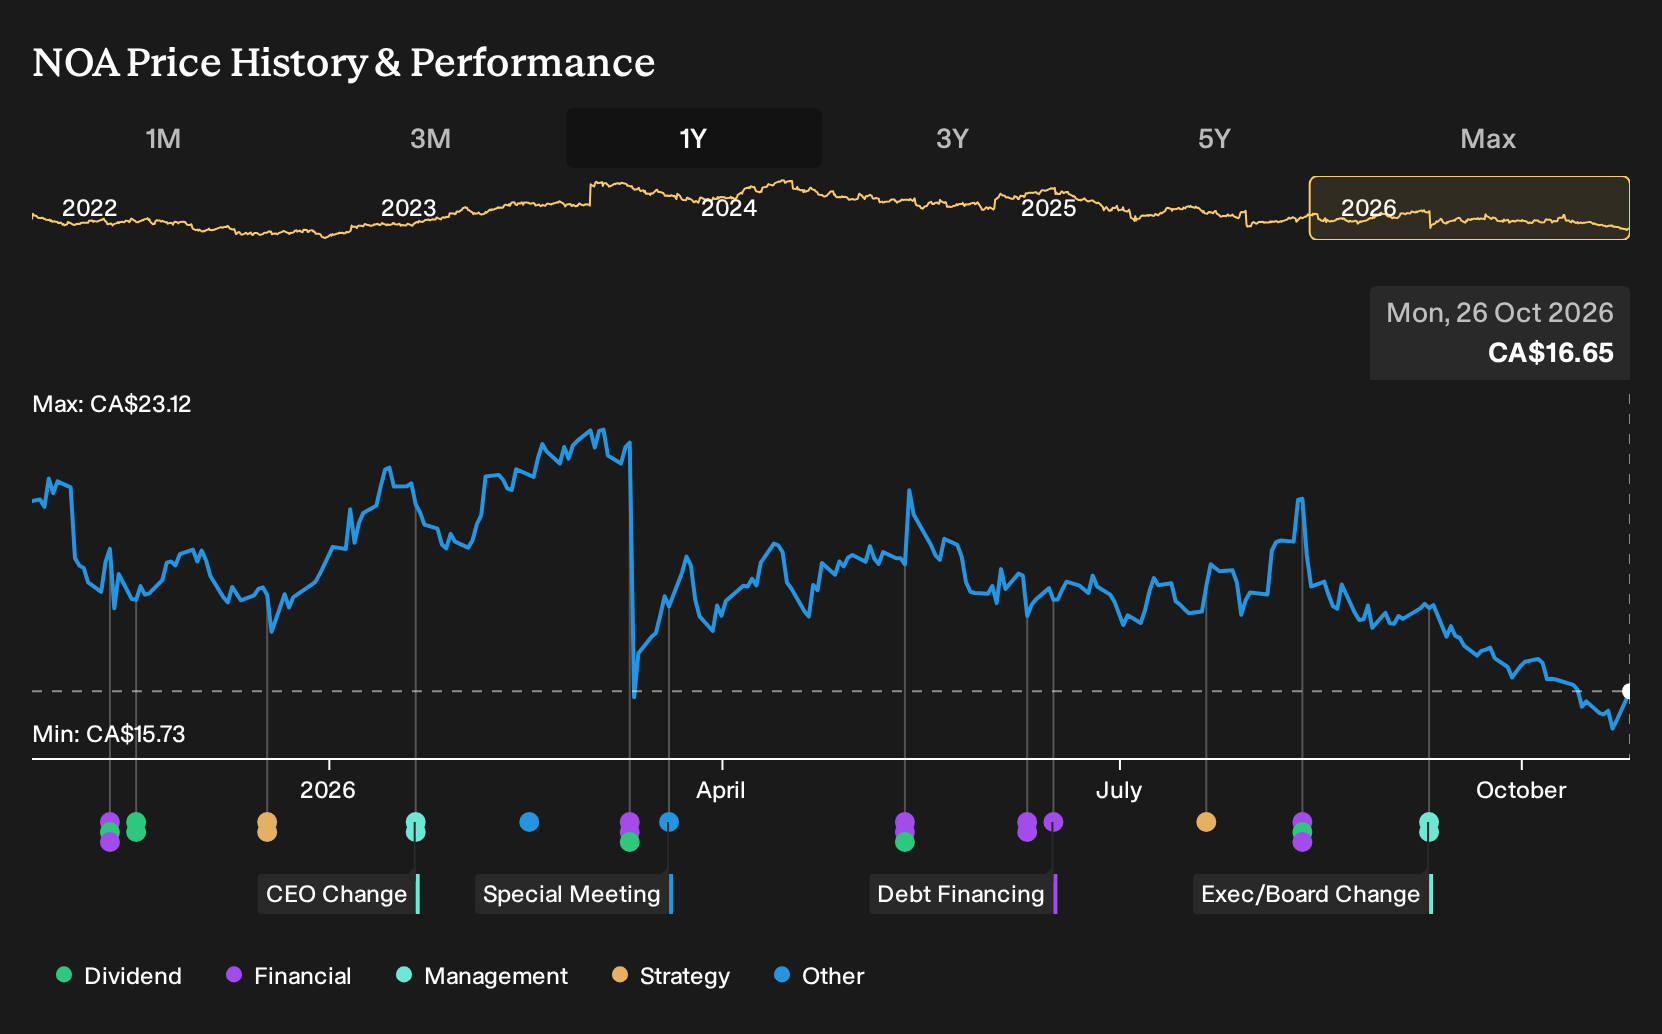
North American Construction Group’s latest quarterly report showed revenue of CA$400.963 million and net income of CA$9.376 million, with net margin slipping to 2.3% compared with a year earlier. Investors who held North American Construction Group over the past year are down 20.2%, including dividends. If you had bought in a year ago based on bullish or bearish analyst stories, how much of that outcome aligns with what was already on record, and how much now depends on whether margins can meaningfully recover?
The easy part of this move is behind North American Construction Group. Zero in on 3 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On North American Construction Group
The shares cost CA$21.33 at the start of the period, and anyone looking at North American Construction Group then had to choose between two very different stories.
The bullish view pinned a Fair Value of CA$55, essentially the price implied if higher margins and faster expansion played out. It leaned on expectations that net margin could reach 8.1% with automation and higher-value contracts doing the heavy lifting.
The more cautious Narrative pointed to a Fair Value of CA$19, an implied lower price if risks bit harder. It focused on dependence on oil sands and coal work where regulatory pressure and capital needs could keep profit margin nearer 5.6%.
What The Results Changed For North American Construction Group
The key fact is simple. North American Construction Group reported Q2 2026 revenue of CA$400.963 million and net income of CA$9.376 million, with net margin at 2.3% versus 3.2% a year earlier. Higher sales but a thinner margin challenged both the bullish 8.1% margin story and the more cautious 5.6% case. The evidence cut both ways.
The lesson to take elsewhere is clear. When a thesis hinges on margin expansion, track the reported net margin line every quarter against the percentages in the original story, not just whether revenue moves in the right direction.
What You Are Paying For In North American Construction Group Today
With North American Construction Group now at CA$16.65 and down 20.2% over the past year, the selected Narrative argues that its Fair Value sits above the current price based on contracted work rather than broad market optimism.
The crux is whether record backlog and bid pipelines really convert into profitable, lower capital intensity projects that support the leverage and free cash flow goals implied in that Narrative.
"The main thing that has to go right is that North American Construction Group converts its record multi year backlog and more than $12 billion global bid pipeline into profitable, lower capital intensity work that supports the targeted 30% free cash flow conversion and planned deleveraging from roughly 2.9 times net leverage."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where North American Work Leads Next
North American Construction Group focuses on projects needing heavy equipment and long contracts. That kind of work depends on reliable background energy supply.
Energy producers with large resource bases face a related challenge. They need fields that keep volumes steady without frequent operational interruptions.
One major operator is targeting higher reliability and lower structural costs. It is reshaping its portfolio to emphasize stronger producing assets.
This combination of steadier production and leaner operations could matter for your watchlist. Especially if you track how long life projects keep funding themselves.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com