


Upstart Holdings has seen its share price under heavy pressure in recent years, and that kind of slide naturally puts the focus on whether the current US$23.00 level is supported by the earnings power of the business. With investors watching both partnership announcements and the income statement, the question now is how today’s valuation lines up with what the company is actually earning.
- Over the past 5 years the stock has fallen about 93.3%, which puts the spotlight firmly on whether the earnings profile can justify even the current reduced valuation.
- MIT Federal Credit Union’s move in 2024 to expand its use of Upstart’s AI-driven platform into indirect auto lending can influence how investors think about future fee income and the timing of any improvement in profitability.
- The analysts covering Upstart Holdings have run their own numbers. See what analysts think Upstart Holdings's shares could be worth.
The issue now is whether the earnings that Upstart generates today, and what it may reasonably earn from partnerships like MIT Federal Credit Union, are enough to support the price you see on the screen.
If you are weighing Upstart Holdings against other ways to play AI-driven finance, it can help to compare it with a wider set of 39 profitable AI stocks that aren't just burning cash.
Is Upstart Holdings Fairly Priced on Earnings?
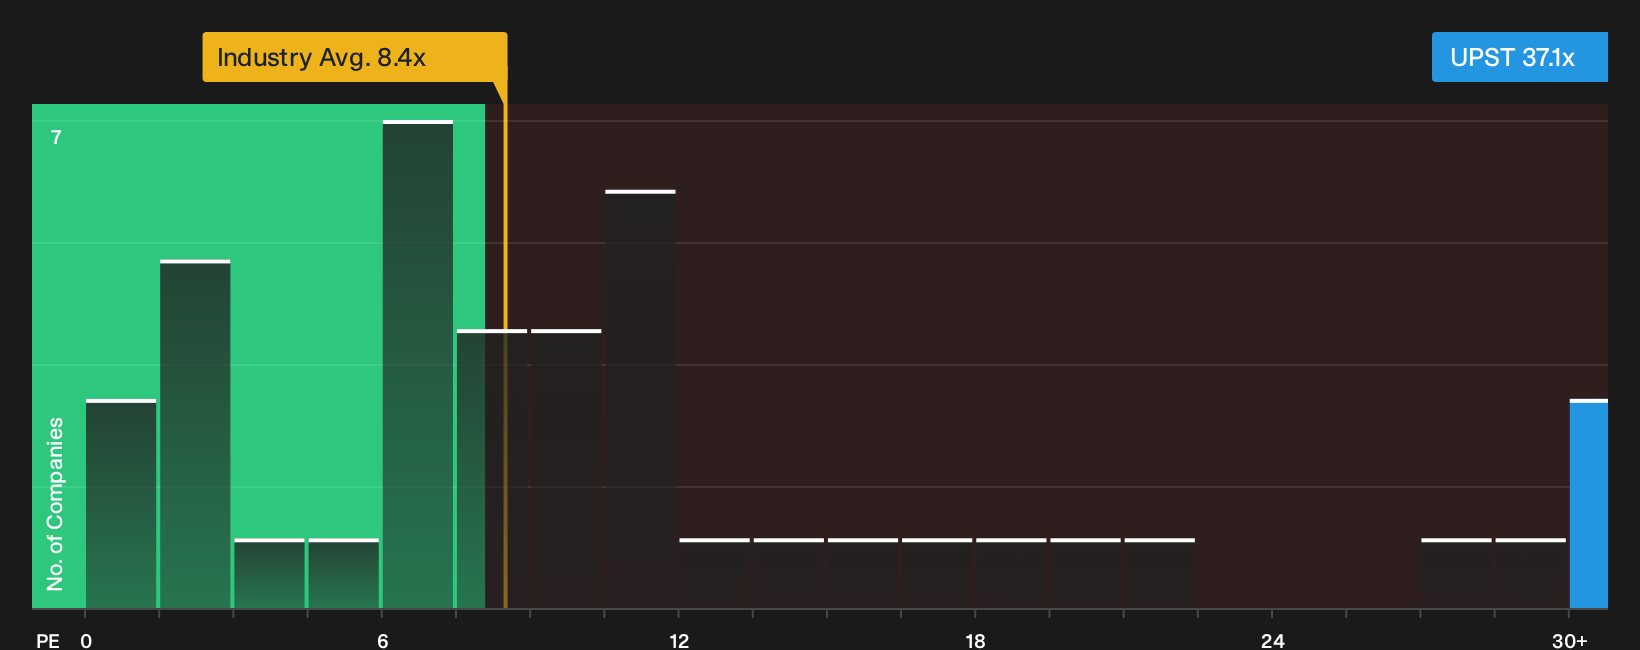
The P/E ratio works well for Upstart Holdings because investors are watching whether the current earnings base can support the share price. At roughly 37.1x, the stock trades at a much richer earnings multiple than the consumer finance industry average of about 8.4x and the broader peer group near 11.5x. This means each dollar of earnings is priced far more highly here than in many comparable lenders.
The fair multiple implied by Upstart Holdings’ own fundamentals sits only slightly below the current P/E, so the share price looks broadly in line with what that tailored benchmark suggests. Because MIT Federal Credit Union has already expanded its use of Upstart’s AI lending platform into indirect auto loans, the market may be willing to keep paying this premium P/E while it waits to see how those partnerships feed into the earnings line. Explore the numbers behind Upstart Holdings's P/E valuation.
The Upstart Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Upstart Holdings pick up where this valuation puzzle leaves off. They spell out which assumptions on growth, margins, and earnings would need to hold for the shares to be worth a lot more or a lot less than today’s price, and they set out those building blocks rather than a single number so you can see how each view stacks up against future results on the Community page.
Community views on Upstart Holdings are split between a funding driven bull story and a regulation and capital intensity focused bear case.
Bull case: 40% undervalued
"Enhanced lending partner confidence, due to strong platform performance and capital market engagements, strengthens funding capabilities and sets the stage for increased origination volume..."
Discover why this Narrative puts Upstart Holdings at 40% undervalued.
Bear case: 28% overvalued
"The move toward committed capital and co-invest structures, including about US$1.3b of cumulative co-invested capital and multi-year forward-flow deals, increases balance sheet exposure..."
Explore why this Narrative puts Upstart Holdings at 28% overvalued.
Before acting on Upstart Holdings' valuation, there is one more lever to check
Big valuation questions are only part of the story for Upstart Holdings, because the people steering the business and the way their rewards are structured can strongly influence how your interests line up with theirs. See who runs Upstart Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com