


Cigna Group has climbed to around US$305.78 per share after a solid multi year run, which puts fresh attention on whether that valuation is properly backed by the insurer's earnings power. With healthcare services back in focus after a sector rebound, the question is how much profit the market is really pricing in.
- The stock has returned 55.3% over 5 years, so anyone buying today is effectively betting that the earnings profile can sustain or improve on what the market has already rewarded.
- Recent sector news around health services operators highlights how expectations for profitability and cash generation can shift quickly, which matters for a diversified healthcare group like Cigna Group that depends on consistent earnings from its insurance and services operations.
- The analysts covering Cigna Group have run their own numbers. See what analysts think Cigna Group's shares could be worth.
The issue now is whether Cigna Group's current share price is adequately supported by the earnings the business is generating today and is expected to produce over time.
If you want to stress test Cigna Group's earnings-based valuation against other options in the market, line it up next to 29 high quality undervalued stocks.
Is Cigna Group Still Cheap on Earnings?
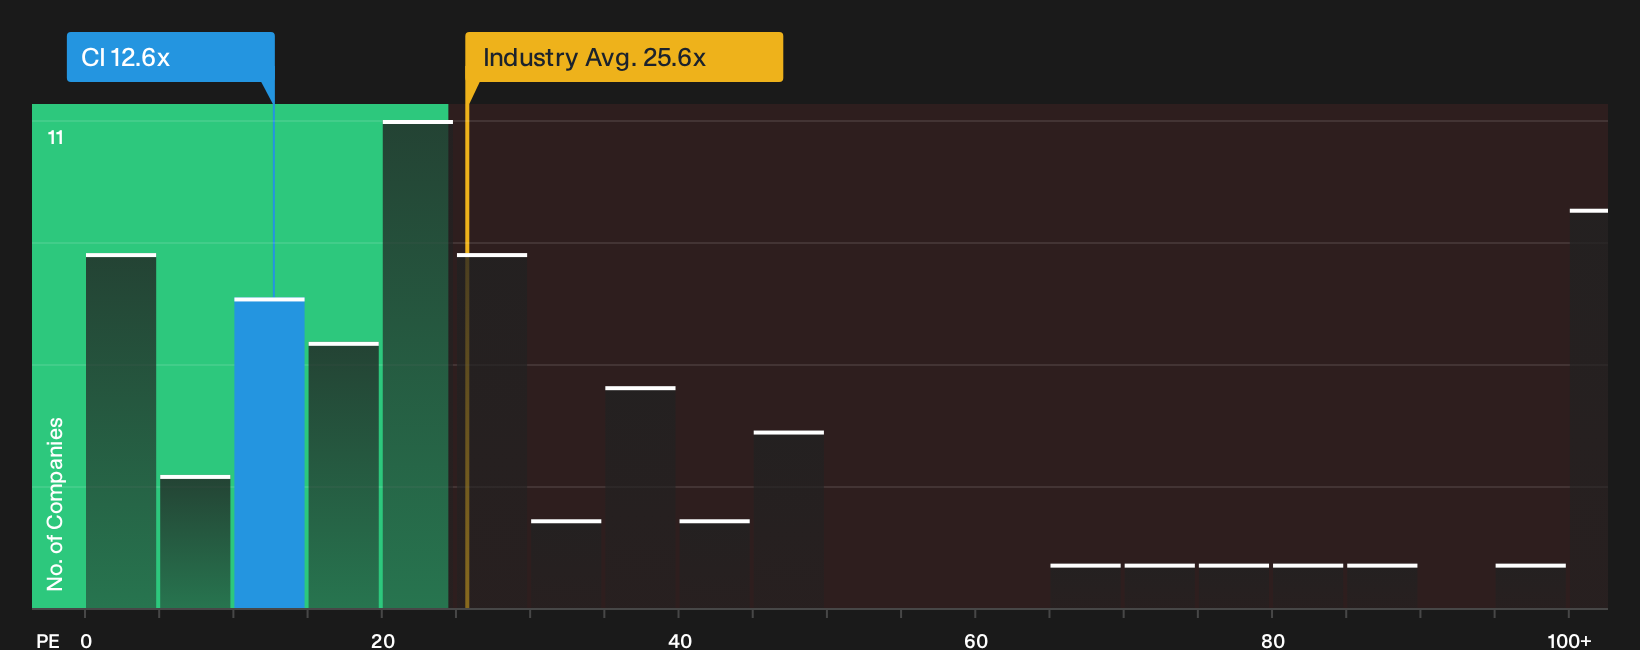
Cigna Group is best gauged on its P/E ratio because earnings remain the key driver of value for a mature health insurer and services provider. The stock trades on roughly 12.6x earnings, which is well below the broader healthcare industry average of about 25.6x and also under the peer group sitting near 31.0x. That gap suggests the market is applying a relatively cautious earnings multiple to the insurer compared with many other healthcare operators.
The tailored fair P/E that blends Cigna Group's size, risk profile, margins and sector context points to a higher level than where the current 12.6x ratio sits, which screens the shares as undervalued on this framework. Because recent health services deals and guidance changes have pulled attention back to the sector, the discount implied by Cigna Group's multiple stands out even more for investors comparing large diversified insurers with smaller operators benefiting from the rebound. Explore the numbers behind Cigna Group's P/E valuation.
The Cigna Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Cigna Group leaves off by laying out what kind of earnings, margin profile and business risk would need to show up for the shares to look meaningfully cheaper or richer than today. Each narrative ties its valuation angle to a specific view on how Cigna Group's growth, profitability and risk balance might evolve, which gives you a reference point you can return to as fresh information comes through.
One of the top community narratives on Cigna Group: 10% undervalued
"Cigna Group is capitalizing on the growing demand for specialty pharmacy and care services, with recent 22% pretax earnings growth in Specialty & Care Services..."
Discover why this Narrative puts Cigna Group at 10% undervalued.
One more angle on Cigna Group that could shift how you see it
Price and earnings only tell part of the Cigna Group story, because the people setting priorities and the way they are rewarded can heavily influence how that story develops over time. See who runs Cigna Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com