


Palo Alto Networks (PANW) is back in the spotlight after rolling out its Unit 42 Continuous Frontier AI Defense service, expanding AI driven security offerings and deepening integrations with third party providers.
Recent trading reflects that enthusiasm. Palo Alto Networks has a 7 day share price return of 12.54% and a 90 day share price return of 22.40%, while the 1 year total shareholder return of 77.25% and 5 year total shareholder return of 360.89% indicate strong longer term momentum.
Capitalize on the AI security momentum around Palo Alto Networks and scan a curated set of cybersecurity peers and adjacent beneficiaries in the 55 AI infrastructure stocks.Bulls see Palo Alto Networks benefitting from AI led security demand and recent price strength, while bears focus on premium pricing and ETF outflows. Which side do current valuation markers support next?
Most Popular Narrative: 1% Undervalued
Palo Alto Networks closed at $390.46, while the most followed narrative pegs fair value near $396.12. This framing treats current pricing as roughly aligned with strong long term expectations that already incorporate ambitious growth and margin targets.
The view that Palo Alto Networks is fairly valued and bullish indicates that the current share price already reflects strong guidance for revenue, NGS ARR, RPO and free cash flow margins through FY27, as well as an eventual move toward a 40% adjusted free cash flow margin by FY28, which leaves limited room for execution shortfalls.
See why 387 investors see Palo Alto Networks as 1% undervalued.
Result: Fair Value of $396.12 (ABOUT RIGHT)
Still, the bullish Palo Alto Networks story relies on clean integration of Idira and Chronosphere, and on easing stock based compensation; any wobble there could quickly test conviction.
Find out about the key risks to this Palo Alto Networks narrative.
Another View: Palo Alto Networks Through The Sales Lens
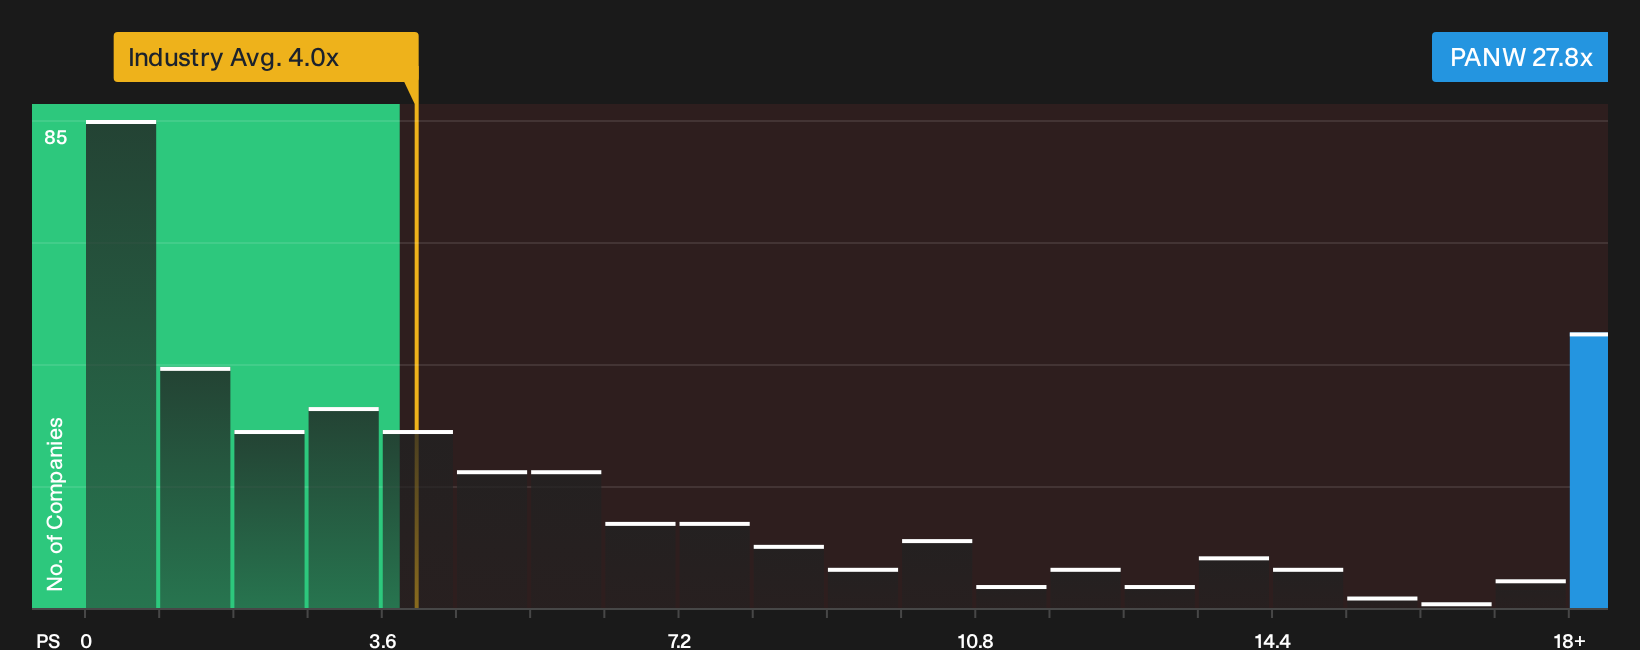
The fair value narrative pegs Palo Alto Networks close to $396. Yet on a simple P/S yardstick, the stock tells a very different story. It trades at 27.8x sales, while US software peers sit near 4x and a fair ratio sits lower again at 15.2x. That gap points to rich expectations baked into today’s price. The real question is whether you think Palo Alto Networks can keep justifying such a premium over time.
For a clearer sense of how the current P/S premium compares with the earnings and cash flow picture, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Palo Alto Networks is split, which is exactly why it helps to run the numbers yourself and weigh both sides of the debate. To pressure test the bullish narrative against the concerns raised, focus on the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Palo Alto Networks?
If Palo Alto Networks has sharpened your focus on where capital works hardest, do not stop here. Broaden your watchlist and give yourself more quality choices.
- Target potential mispricing opportunities by scanning a curated 29 high quality undervalued stocks before market attention fully catches up.
- Build a steadier income stream by reviewing a focused set of 5 dividend fortresses that combine yield with fundamentals.
- Fortify your portfolio resilience by combing through a 30 resilient stocks with low risk scores that screens for sturdier balance sheets and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com