


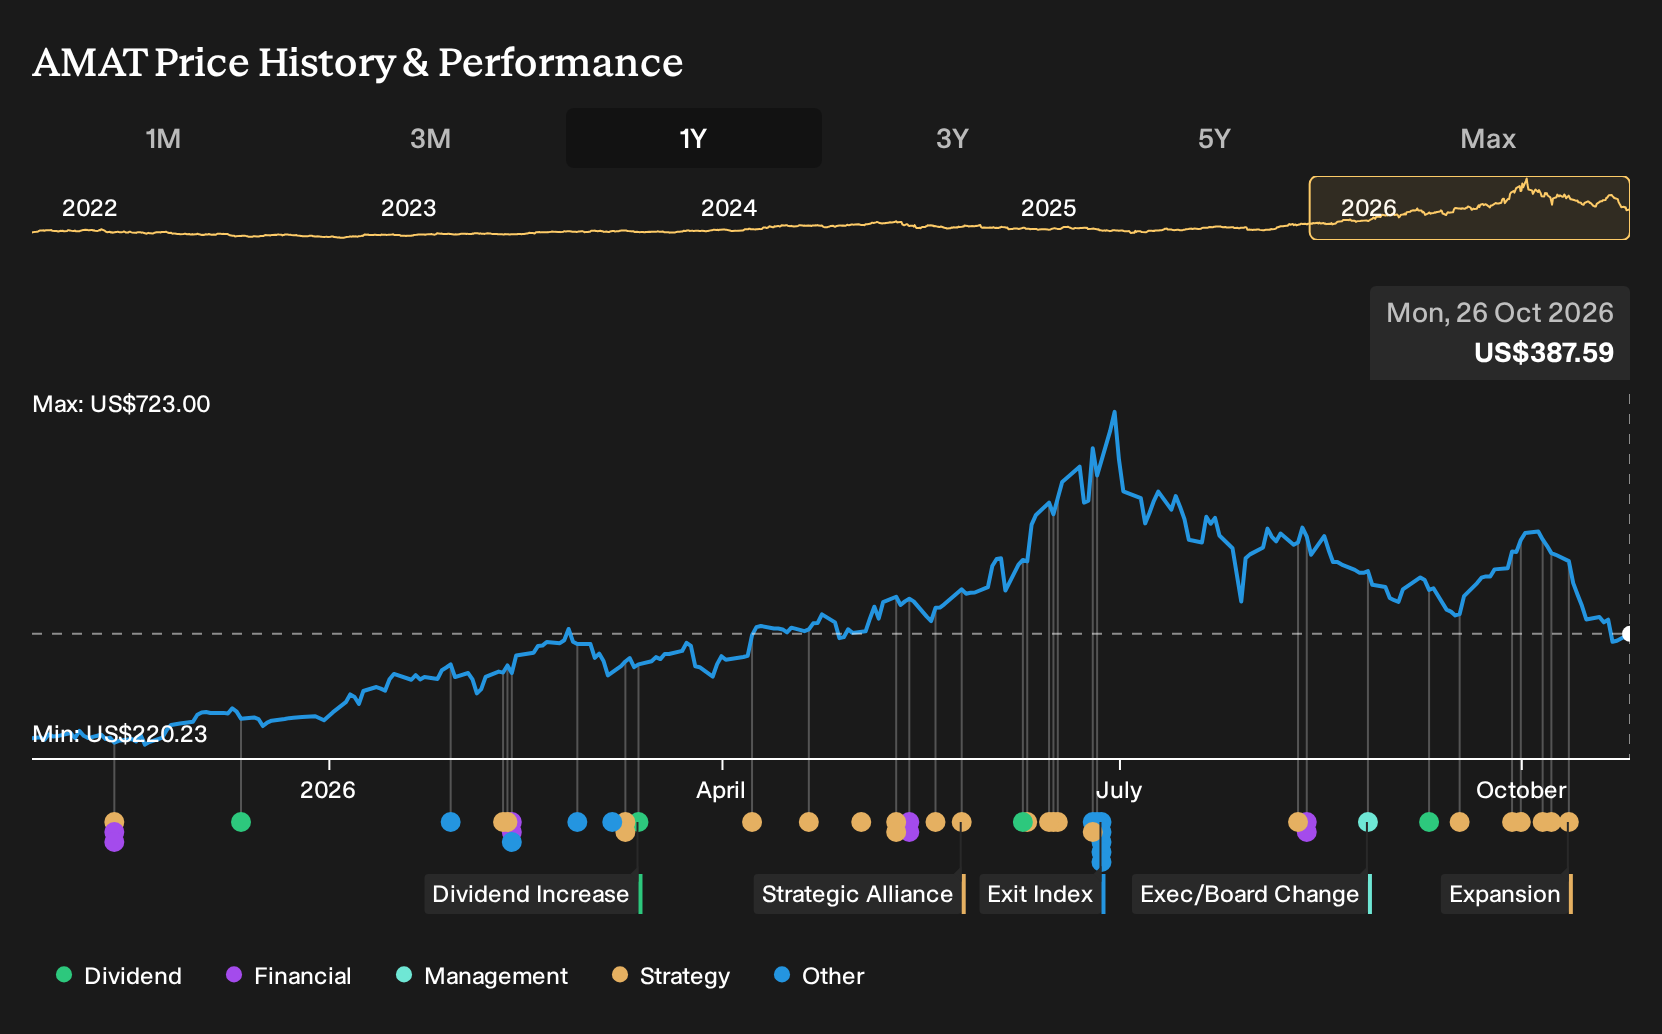
If Applied Materials sat on your watchlist instead of in your portfolio, the result may feel like a missed shot. Investors who held Applied Materials over the past year are up 68.5%, including dividends. That move unfolded while headlines focused on AI-driven chip demand, advanced packaging tools and multi-year fab buildout plans. The harder question now is this: were those trends already clear enough in late 2025 to justify assuming AI and IoT would keep equipment orders climbing?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Applied Materials. See which of 55 AI infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On Applied Materials
The shares cost US$229 at the start of the period. Anyone looking at Applied Materials then had to decide whether chip demand from AI and IoT would keep equipment orders strong enough to back a bullish price.
The optimistic Narrative put Fair Value at US$250 (9% above the start price). That view leaned on AI, high bandwidth memory and advanced packaging needing more complex tools, with analysts assuming revenue growth of 7.8% a year and rising margins.
The cautious Narrative set Fair Value at US$195 (15% below the start price). Here the key concern was reliance on a few regions and export rules, with assumptions of 4.3% annual revenue growth and a future P/E of 20.4x.
What The Evidence Did To The Applied Materials Argument
Applied Materials reported Q3 2026 revenue of US$9,115m and net income of US$2,538m, with net margin at 27.8% versus 24.4% a year earlier. That margin level sat close to the bullish 27.8% assumption and arrived alongside record quarterly sales, so the period leaned toward supporting the optimistic Narrative on both scale and profitability.
The useful lesson is where to look first when a story hangs on operating leverage. Track whether margin targets mentioned in an upbeat case actually show up in later filings, and then decide how much you want to pay for those percentages once they appear in audited numbers.
What Applied Materials' Price Now Assumes
Applied Materials trades at US$388 today. The selected bullish Narrative argues that Fair Value sits above the current price, based on how well the business can turn AI related demand and its EPIC partnerships into higher value segment mix.
On this view, today’s price still does not fully credit Applied Materials continuing to shift revenue toward advanced packaging, process diagnostics and services while keeping investment and ramp costs under control.
"The main thing that has to go right is that Applied Materials continues to translate AI related demand, EPIC partnerships and expanded manufacturing capacity into growth in higher value segments like advanced packaging, process diagnostics and services while managing investment and ramp costs."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
One More AI Hardware Question
Applied Materials sits close to the tools that build advanced chips. Your next step might be asking what keeps those chips fully occupied.
AI models burn through huge computing tasks. That demand pushes operators to look for ever larger, more capable processing clusters.
Another hardware specialist focuses on those clusters, selling the computing platforms that run training and inference at scale.
If that spending pace slows, its customers can lean longer on existing gear. If the appetite for bigger models keeps stretching higher, the need for fresh capacity could become its main challenge and opportunity.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 57% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com