


Marvell Technology has delivered a very large 3 year share price gain. With the stock recently trading around US$233.78 after some short term pullbacks, the question now is whether that outcome can be squared with what the business earns.
- The share price has climbed roughly 4x over 3 years. This puts considerable weight on the idea that Marvell's earnings profile can support a much richer valuation than in the past.
- Fresh products for high bandwidth AI data centers and new work on standardizing hardware security with major cloud providers may support expectations for stronger and more durable profit streams tied to AI and connectivity spending.
- Your read on Marvell Technology is one view; the desks covering it have another. See what analysts think Marvell Technology's shares could be worth.
For investors, the debate is whether the current market value of Marvell Technology is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to test the same earnings and Fair Ratio question across a wider AI infrastructure theme, scan the 55 AI infrastructure stocks.
Does Marvell Technology Look Pricey on Earnings?
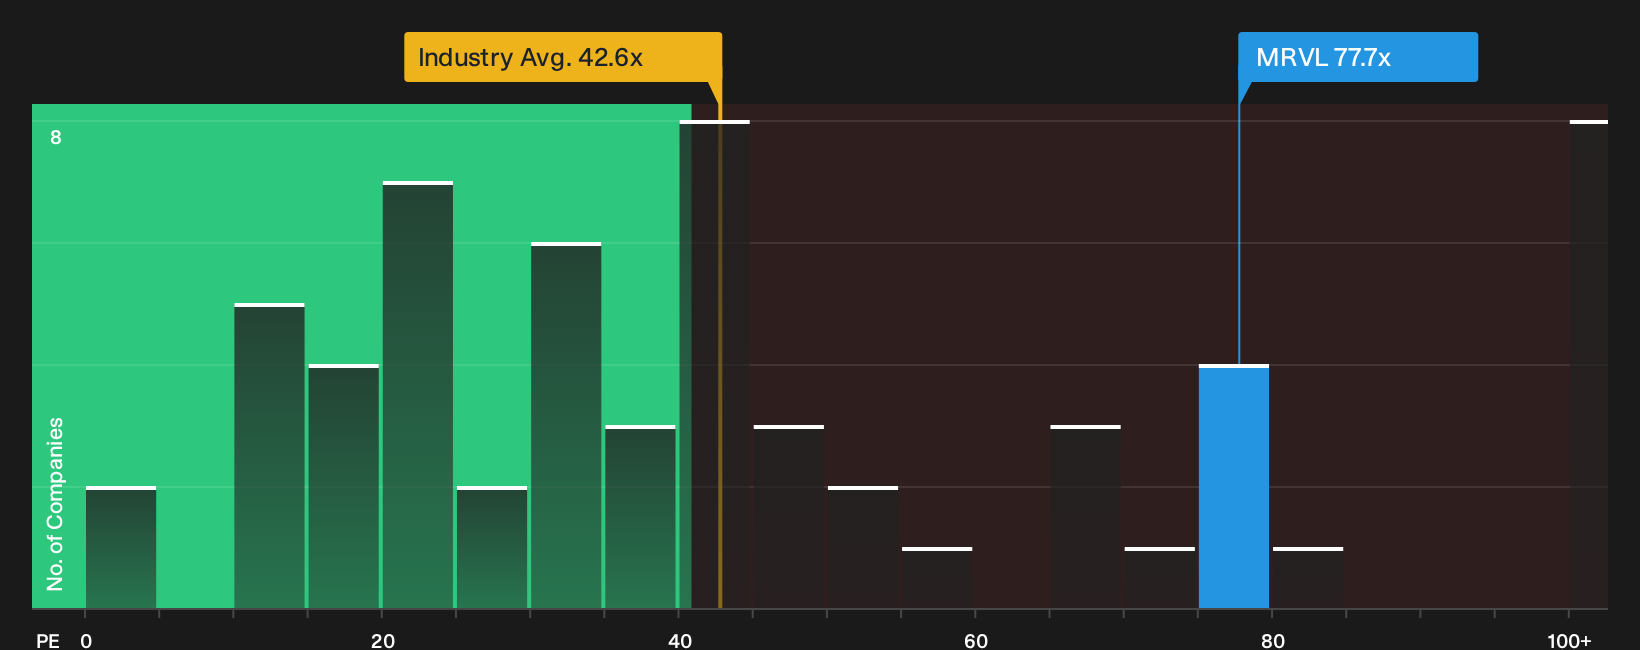
A P/E lens suits Marvell Technology because earnings are the key bridge between its AI and connectivity story and what you pay for each share today. At roughly 77.7x, the current P/E is far above the broader semiconductor sector, where the average sits near 42.6x, and also well ahead of the peer group around 44.6x. That kind of gap indicates the market is putting a high price on each dollar of profit already on the table.
The Fair Ratio model, which adjusts the P/E you might expect for Marvell Technology after accounting for its sector, size, margins and risk profile, points to a lower earnings multiple than the market is paying, so the stock screens as overvalued on this framework. Despite fresh AI data center products and new security collaborations with hyperscalers lifting interest in the story, the current P/E already reflects a rich earnings outlook compared with both sector norms and peers. Explore the numbers behind Marvell Technology's P/E valuation.
The Marvell Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Marvell Technology valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today on current prices. Instead of a single output from a ratio or model, Narratives show the future that figure relies on so you can watch how Marvell Technology's actual progress lines up with those assumptions over time on the Community page.
Community views on Marvell Technology split between investors who see room left in the AI buildout story and others who think the current price already embeds a demanding execution bar.
Bull case: 31% undervalued
"The expanded commercial agreement with a major hyperscaler, which includes a warrant tied to up to US$120b of cumulative revenue over 6.5 years for TPU attached custom silicon, supports the case that Marvell has visibility on sizeable multi year orders..."
Discover why this Narrative puts Marvell Technology at 31% undervalued.
Bear case: 67% overvalued
"At ~$134, the stock is priced for FY2028 execution... there is no margin for error."
Explore why this Narrative puts Marvell Technology at 67% overvalued.
The price of Marvell Technology is only one piece of the decision
Share price and P/E tell you what the market is paying today, but analyst projections for Marvell Technology over the next few years offer a different lens on where expectations sit. Explore where analysts expect Marvell Technology to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com