


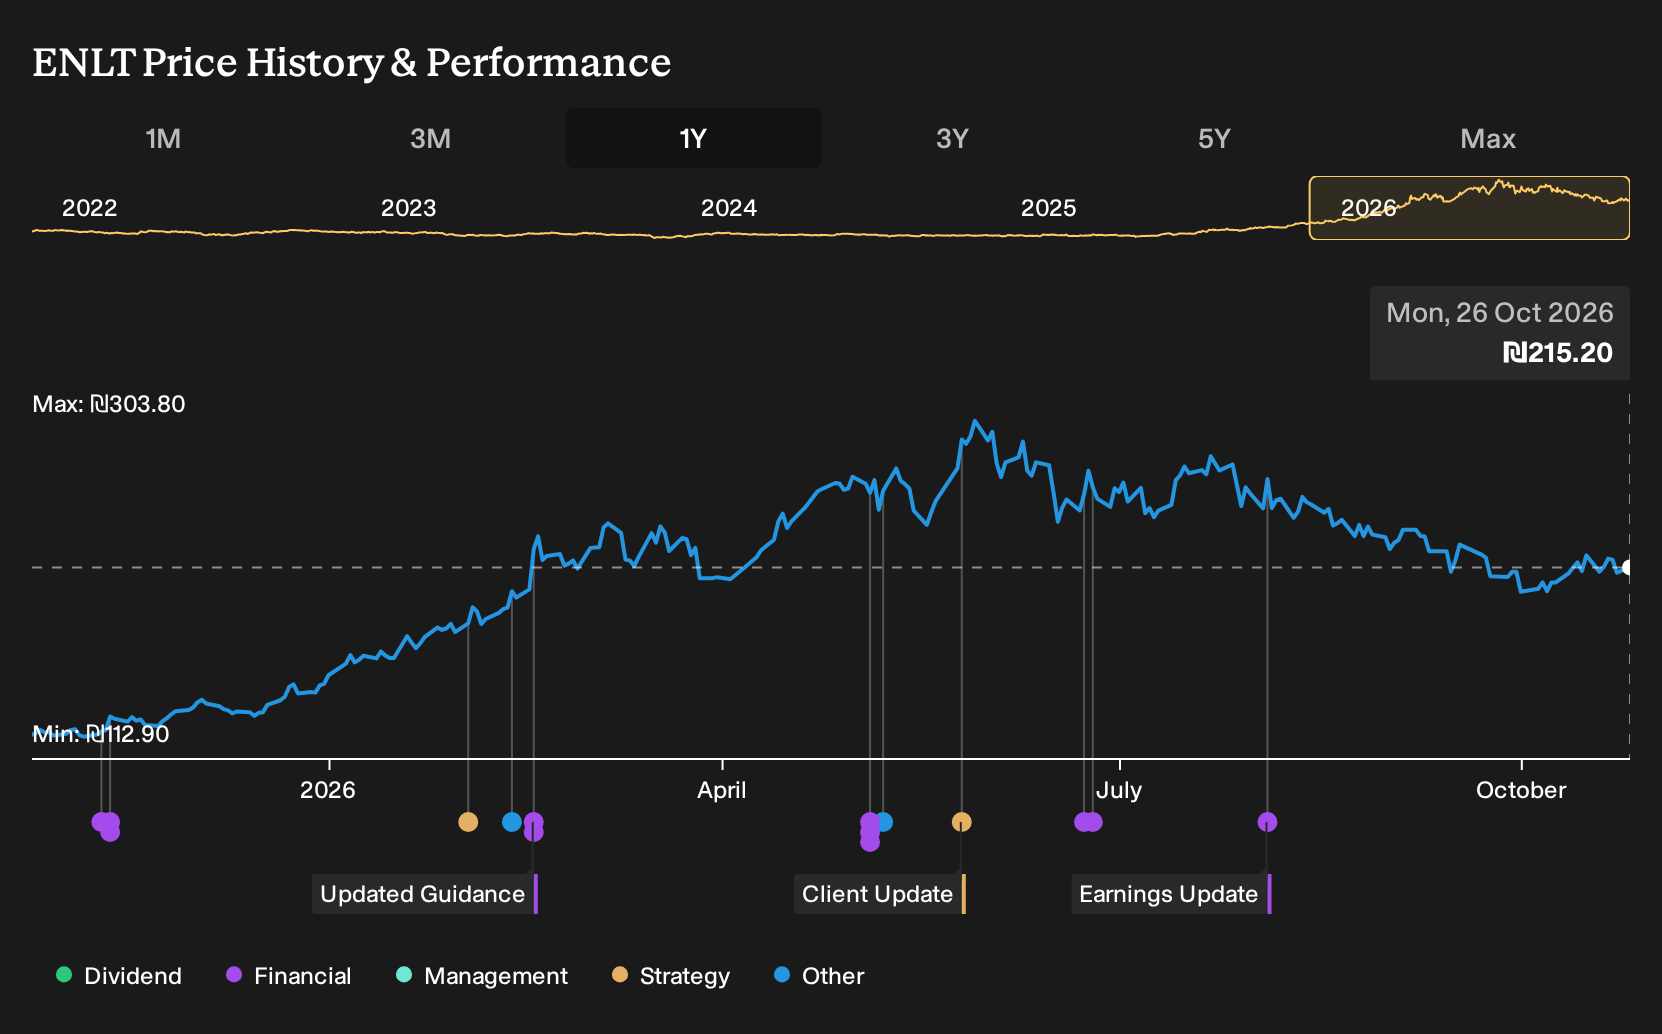
- Enlight Renewable Energy is scheduled to release its Q3 2026 results on November 3, with management expected to report lower earnings compared with the prior year despite higher revenue.
- The combination of rising sales and anticipated earnings pressure points to cost, mix, or project economics squeezing profitability at Enlight Renewable Energy. This can matter more for long term value than short term analyst sentiment.
- We will now look at how Enlight Renewable Energy's investment narrative could shift given rising revenue but weaker expected Q3 profitability.
What Is Enlight Renewable Energy's Investment Narrative?
To own Enlight Renewable Energy, you need to be comfortable with a capital intensive build and operate model across wind, solar and storage, plus a project pipeline of around 20 GW of generation and 35.8 GWh of storage. The appeal is tied to execution on that backlog and keeping projects on time and on budget. The upcoming Q3 2026 report, with higher sales but weaker expected earnings, puts a spotlight on cost discipline and whether recent margin pressure is a temporary project mix issue or a sign of structurally higher expenses.
In the short term, the key swing factors are profitability, funding costs and how efficiently Enlight Renewable Energy converts its growing revenue base of ₪585.2 million and net income of ₪89.7 million into cash. Interest payments are currently not well covered by earnings and the high P/E multiple of 108.9x leaves little room for operational missteps. Analyst expectations pointing to softer Q3 profitability increase the importance of these near term catalysts and bring existing risks such as thinner margins and significant non cash earnings into sharper focus.
That said, there is a less obvious pressure point that could matter even more if ...
There's only one way to know the right time to buy, sell or hold Enlight Renewable Energy. Head to Simply Wall St's company report for the latest analysis of Enlight Renewable Energy's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Enlight Renewable Energy research is our analysis highlighting 1 key reward and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Enlight Renewable Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enlight Renewable Energy's overall financial health at a glance.
Looking For More Ideas Beyond Enlight Renewable Energy?
If you want to balance your view on Enlight Renewable Energy with a wider watchlist, the Simply Wall St Screener can surface other companies that match the kind of portfolio you are trying to build.
- If capital preservation is front of mind, consider reviewing a curated set of resilient businesses in the 223 resilient stocks with low risk scores.
- For readers hunting for mispriced opportunities, it can be useful to scan companies that the data flags as attractively valued using the 195 high quality undervalued stocks.
- Income focused investors who care about consistency as much as yield can assess candidates in the 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com