


- Trustmark is set to report quarterly earnings after market close, with analysts expecting revenue to be flat year over year following a prior 5.3% rise and with a track record of missing Wall Street revenue estimates in recent years.
- The prospect of flat sales against a backdrop of past revenue estimate misses puts fresh attention on Trustmark’s underlying loan demand, fee income momentum, and cost control ahead of the announcement.
- We will look at how Trustmark's investment narrative holds up against the prospect of flat revenue in the upcoming earnings release.
Trustmark Investment Narrative Recap
To own Trustmark, you need to be comfortable with a regional bank that leans heavily on the Gulf South, steady core deposits and disciplined credit, rather than fast top line expansion. Flat revenue expectations this quarter point you back to the real levers: loan demand, deposit mix and fee traction matter more than a single print.
The key near term swing factor is whether Trustmark can keep its net interest margin around the guided 3.80% to 3.85% range while containing expenses on its new tech stack. The main risk right now is that loan and deposit growth assumptions or margin stability do not show through in results, which would challenge the efficiency and earnings narrative.
Recent system work is the announcement that lines up most directly with an earnings day focused on flat revenue. Trustmark has completed a multi year conversion to FIS platforms across deposits, payments, teller, sales and imaging. That is a big operational change. The question for you is what it actually does for costs per branch and per employee.
If management starts to redeploy staff and gradually reduce full time roles, the benefit should appear in the efficiency ratio rather than the headline revenue line. That matters because the bank already reports a net interest margin near 3.8% and high quality earnings. Evidence that the FIS conversion is supporting stable margins and controlled provision expense could help reinforce the long term thesis even if this quarter’s top line is flat.
What The Current Analyst Story Implies For Trustmark
Trustmark's narrative projects US$1.0b revenue and US$252.1m earnings by 2029. That setup assumes 7.4% yearly revenue growth and an earnings increase of about US$17.8m from the current US$234.3m level.
Uncover why Trustmark's fair value indicates a 9% potential upside to its current price that may not last much longer.
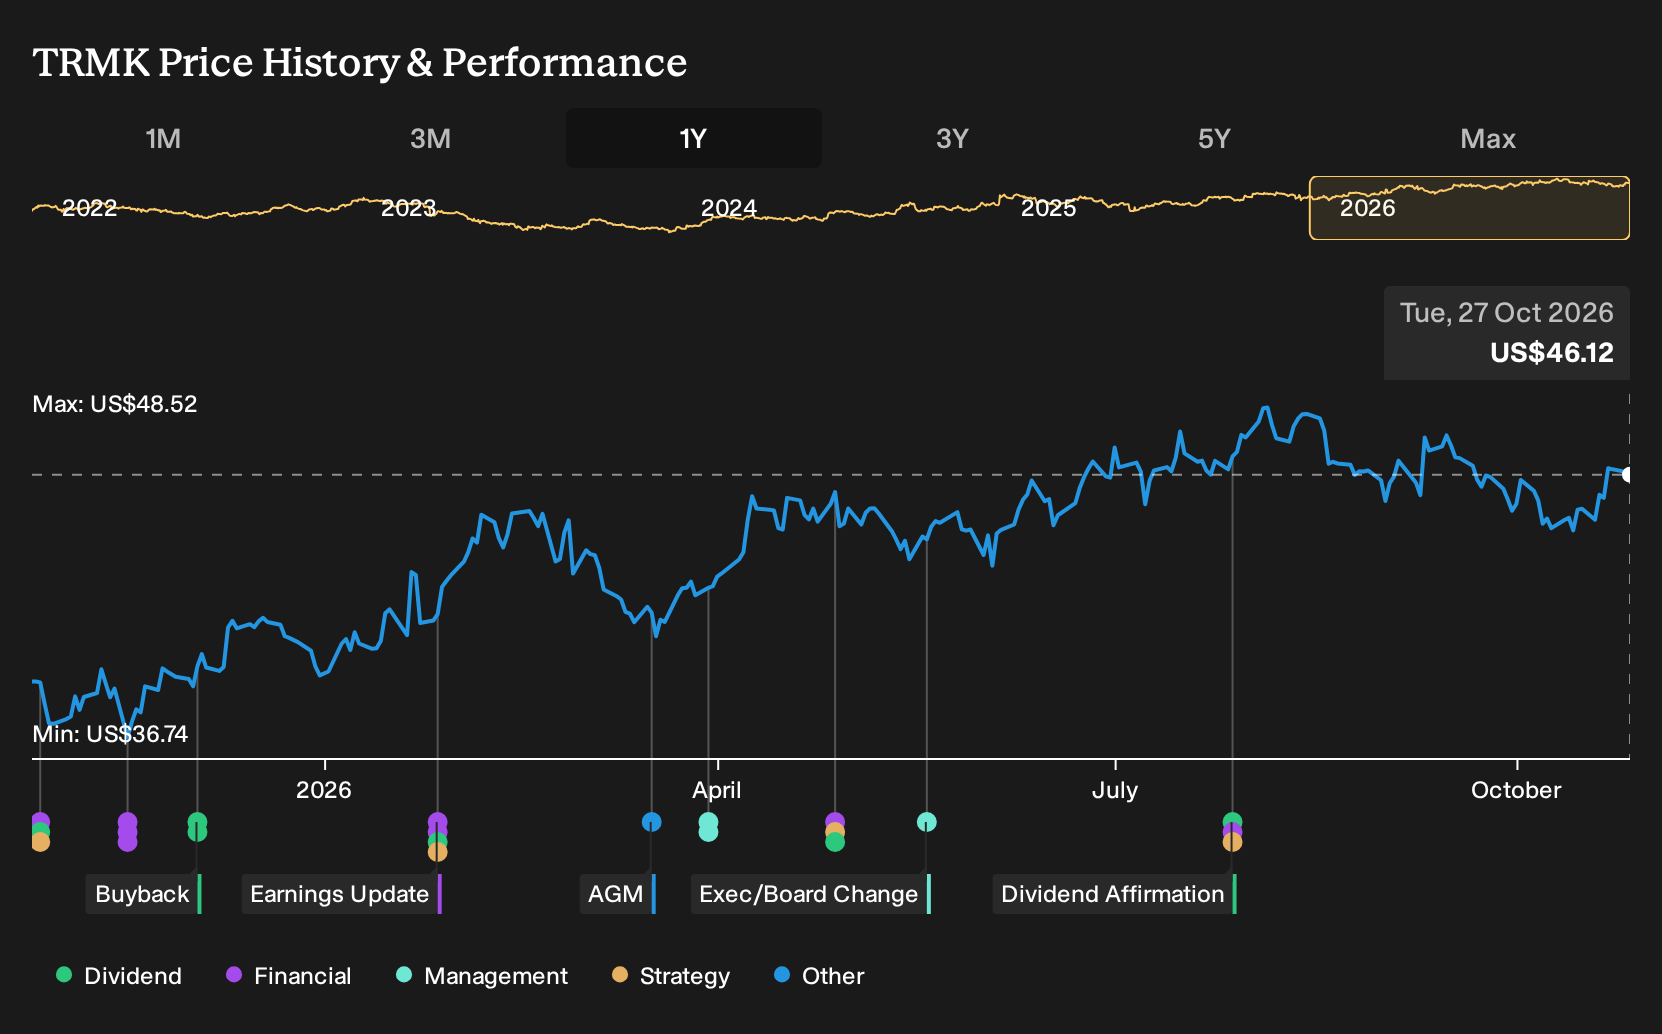
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Trustmark research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trustmark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trustmark's overall financial health at a glance.
Looking for more investment ideas beyond Trustmark?
Once you have a handle on Trustmark, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan through a curated 29 high quality undervalued stocks that may offer a different balance of price and business strength.
- For investors who care most about income resilience, check out a handpicked set of 5 dividend fortresses that could complement a regional bank holding.
- If balance sheet strength is your priority, broaden your watchlist with a focused list of solid balance sheet and fundamentals (24 results) that aims to highlight financially robust businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com