


Why FactSet’s New Private Markets Push Matters Now
FactSet Research Systems (FDS) is drawing fresh attention after partnering with Nasdaq Private Market to feed verified Cap Table data for private companies directly into its platform.
The move adds auditable ownership records on funding rounds, secondary sales, and dilutive events, giving clients tighter visibility into private company structures at a time when interest in FactSet’s private markets toolkit and recent financial performance is already elevated.
Recent trading shows how this story is feeding into sentiment. FactSet’s share price has climbed 18.42% over the past month and 13.51% year to date to US$323.39. The 1 year total shareholder return of 13.38% contrasts with a 3 year total shareholder return that is down 21.47%, signaling improving momentum after a weaker longer stretch.
Look beyond FactSet Research Systems and see how other data and analytics players are priced today by reviewing our curated list of 29 high quality undervalued stocks.
FactSet Research Systems appears to be a solid information engine, with fresh momentum in private markets and recent organic growth. The harder question is whether the current US$323.39 share price still leaves enough value on the table.
Most Popular Narrative: 25% Overvalued
FactSet Research Systems closed at $323.39 while the most followed narrative, which puts fair value at $258.69, argues the stock price is running ahead of itself and leans heavily on how management actions line up with what was said on prior calls.
FactSet closed fiscal 2026, with the largest single ASV quarter in its history, $86 million in one period, a 7% full-year organic growth rate above the high end of its own guidance, and language calibrated to signal that the compression chapter is closed. What management presents this morning is not a company celebrating a record. It is a company selecting, with some care, which parts of the record to carry forward, and which commitments from the prior call to quietly retire.
See why 1 investors see FactSet Research Systems as 25% overvalued.
Result: Fair Value of $258.69 (OVERVALUED)
Still, shifting disclosure around key AI partnerships and the new consumption pricing caution could challenge the idea that FactSet’s current premium is fully justified.
Find out about the key risks to this FactSet Research Systems narrative.
Another View: What Our DCF Model Says About FactSet Research Systems
The narrative above states that FactSet Research Systems is 25% overvalued at $323.39. Our DCF model, however, suggests a different perspective. On that framework, the stock trades below an estimated future cash flow value of $440.45, which indicates potential undervaluation instead. Which interpretation do you find more compelling?
For readers who want to see how a cash flow based approach treats the same numbers, it is worth examining how the SWS DCF model builds up to that fair value estimate in detail. Look into how the SWS DCF model arrives at its fair value.
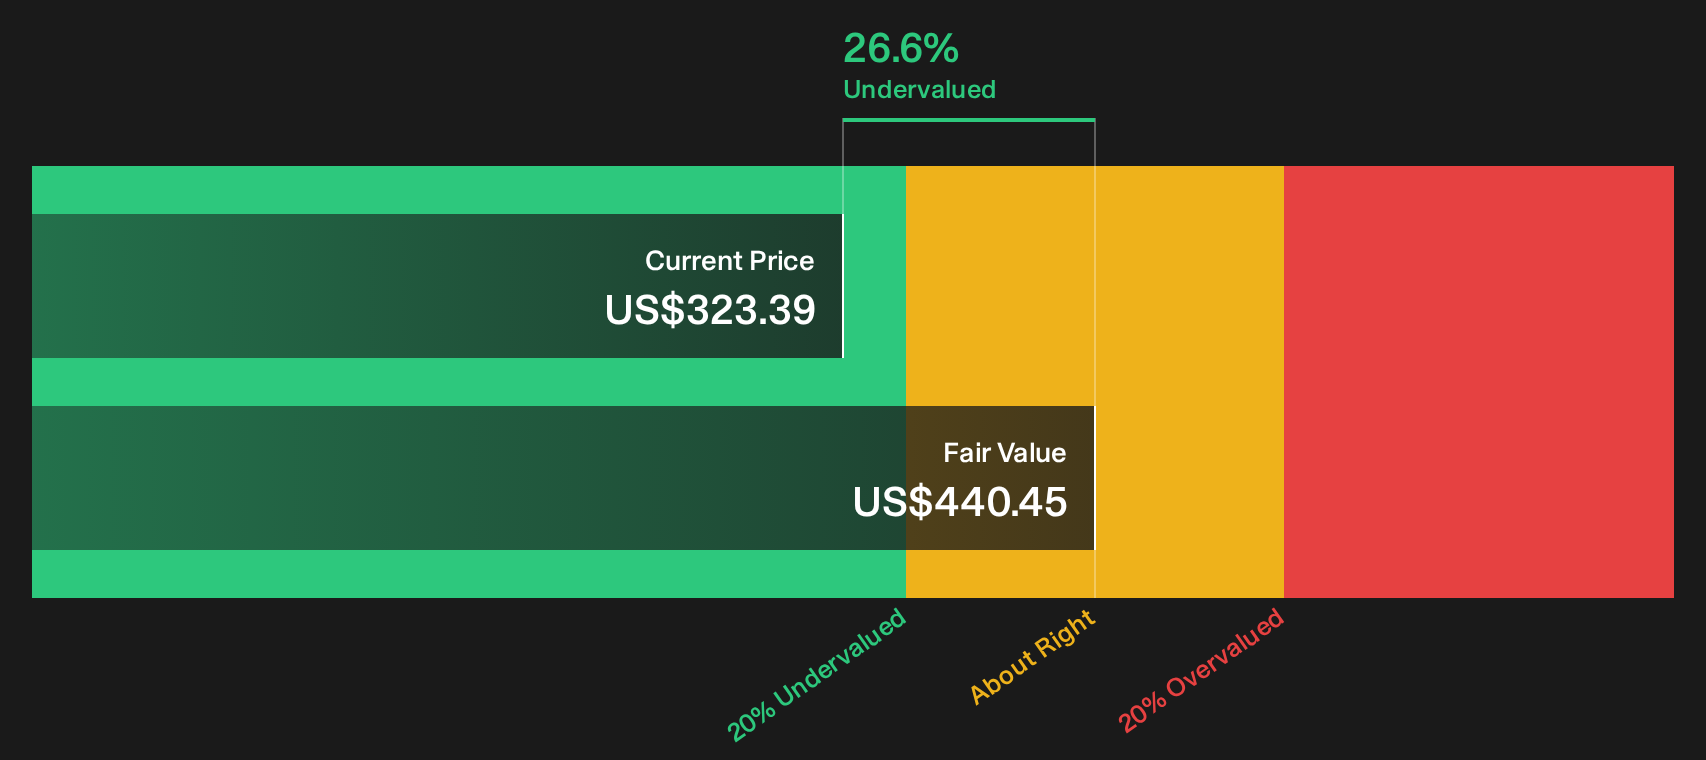
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FactSet Research Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on FactSet Research Systems so far. Market sentiment can flip fast, so review the key data, pressure test the arguments, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FactSet Research Systems?
If you only stop at FactSet Research Systems, you risk missing other opportunities that could fit your goals even better, so broaden your search before you act.
- Target resilient cash generators by scanning companies with strong fundamentals and sturdy finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by reviewing our curated 29 high quality undervalued stocks that may offer more attractive entry points than the market average.
- Strengthen your income stream by checking out a focused 5 dividend fortresses that filters for higher yielding payouts with an eye on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com