


Why Ecolab Stock Is Back In Focus After Fresh Earnings
Ecolab (ECL) is on investors' radar after third quarter results showed higher revenue alongside slightly softer quarterly earnings per share, paired with management guidance calling for double digit sales growth in the coming quarter.
With the shares at US$288.89, Ecolab has inched higher over the past month. That recent 1-month share price return of 3.36% sits on top of a 9.99% year to date share price gain and a far stronger 3-year total shareholder return of 87.22%. This hints that investors have been steadily warming to the story as revenue growth and the latest upbeat sales guidance land on top of smaller partnership announcements such as the ES-Medical agreement.
Scan how Ecolab's earnings driven move compares with other resilient compounders by reviewing the 30 resilient stocks with low risk scores, which have historically paired steadier risk profiles with solid fundamentals.
Ecolab has delivered solid revenue growth and a long run of strong shareholder returns. After this latest move, the central question is straightforward: does the current share price still leave enough value on the table?
Most Popular Narrative: 11% Undervalued
On the most followed view of Ecolab, the narrative fair value of $324.95 sits ahead of the recent $288.89 close, which puts the spotlight on whether its growth engines and pricing power can justify that gap.
Growth engines such as Global High Tech, Life Sciences, Digital and Pest, which now contribute roughly a quarter of sales and include Global High Tech targets for more than 25% annual growth to US$4b of sales and 25% operating margin by 2030, are expected to drive faster organic revenue growth and support the company’s goal of at least 20% operating margin and higher ROIC.
See why 55 investors see Ecolab as 11% undervalued.
Result: Fair Value of $324.95 (UNDERVALUED)
Still, the Ecolab narrative could be challenged if heavy industrial demand weakens further or if higher tariffs and input costs outpace value based pricing.
Find out about the key risks to this Ecolab narrative.
Another View: What Ecolab’s P/E Is Telling You
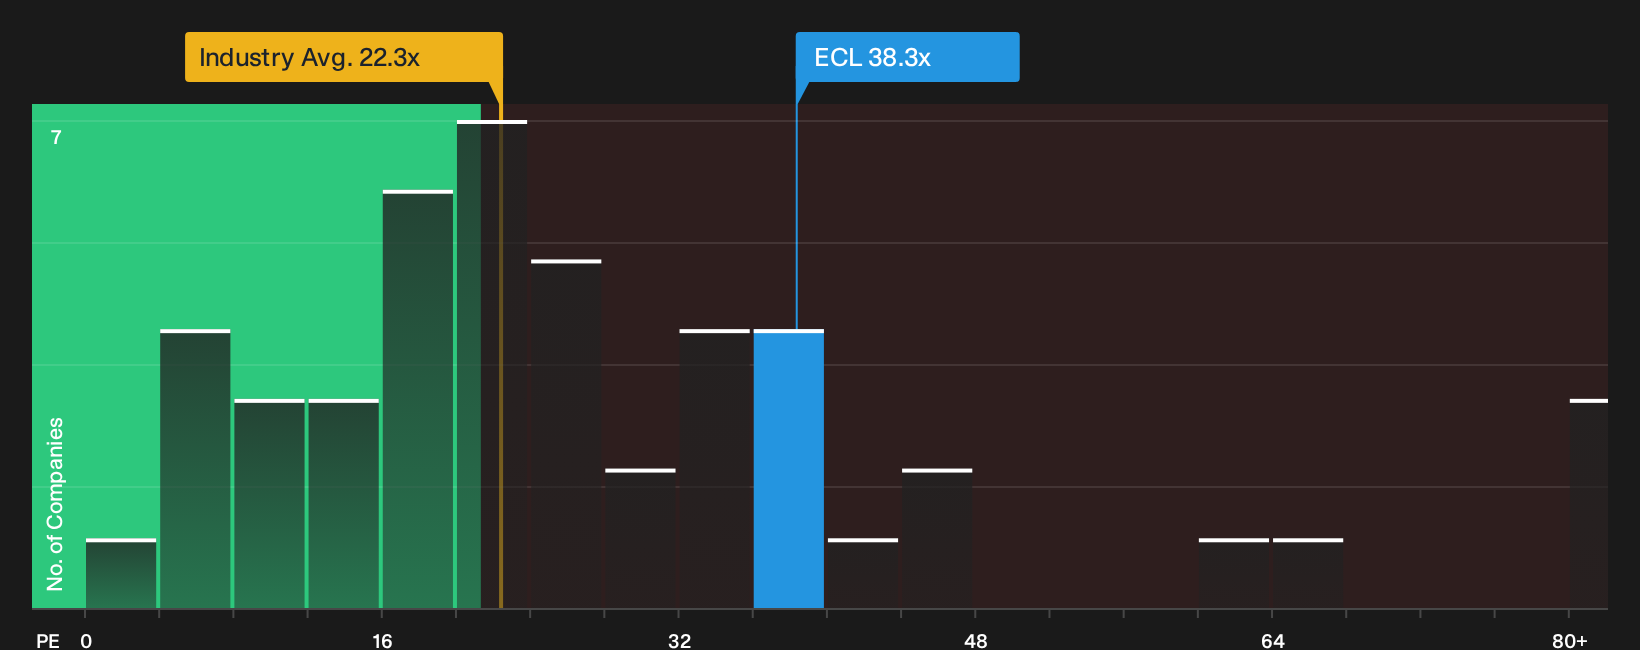
The narrative fair value of $324.95 paints Ecolab as undervalued, yet the market is already paying a rich 38.3x P/E. That is well above the US Chemicals sector on 22.3x and above a fair ratio of 23.7x, which points to valuation risk if expectations slip even slightly.
For a closer look at how this gap between current and fair ratio might narrow over time, and what that could mean for your own assumptions, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution in Ecolab's story feels familiar, trust that instinct and review the numbers yourself today so you are not reacting after everyone else has moved when you weigh up the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Ecolab?
Do not stop your research with Ecolab when you can quickly scan other opportunities that match your style and build a watchlist ready for your next decision.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality where expectations look conservative by checking the 29 high quality undervalued stocks.
- Line up potential income ideas with dependable cash profiles by scanning the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com