


- DFI Retail Group Holdings reported a 17% year on year increase in underlying subsidiary profit for Q3, raised full year underlying profit guidance, and agreed to acquire Maxim’s interests in the Starbucks licensed business for about US$340 million.
- The move to absorb the Starbucks franchise interests gives DFI Retail Group Holdings a larger platform in coffee retail, which could reshape how the group balances its convenience, health and beauty, and food businesses across key Asian markets.
- We will look at how DFI Retail Group Holdings' investment narrative is affected by the stronger Q3 profit performance and upgraded guidance.
Compare how DFI Retail Group Holdings' renewed focus on profitable consumer franchises stacks up against 610 high quality undiscovered gems that could be quietly building similar multi-brand platforms across Asia.
DFI Retail Group Holdings Investment Narrative Recap
To own DFI Retail Group Holdings, you need to believe the business can turn a broad multi format footprint into consistently higher quality earnings, even as cigarette driven convenience traffic, e commerce pressure and value conscious Asian consumers keep grinding away at margins. The recent Q3 profit uplift and higher guidance speak to progress. The most important short term catalyst remains execution in higher margin Health and Beauty, Ready to Eat and digital, together with protecting pricing power.
The Starbucks licensed business acquisition adds a fresh pillar, yet it also raises the bar on delivery. The biggest risk still sits in day to day trading conditions across core Food and Convenience, where heavy price investment, modest digital penetration and weak like for like sales in some banners could quickly dilute recent gains if cost savings and mix shift stall.
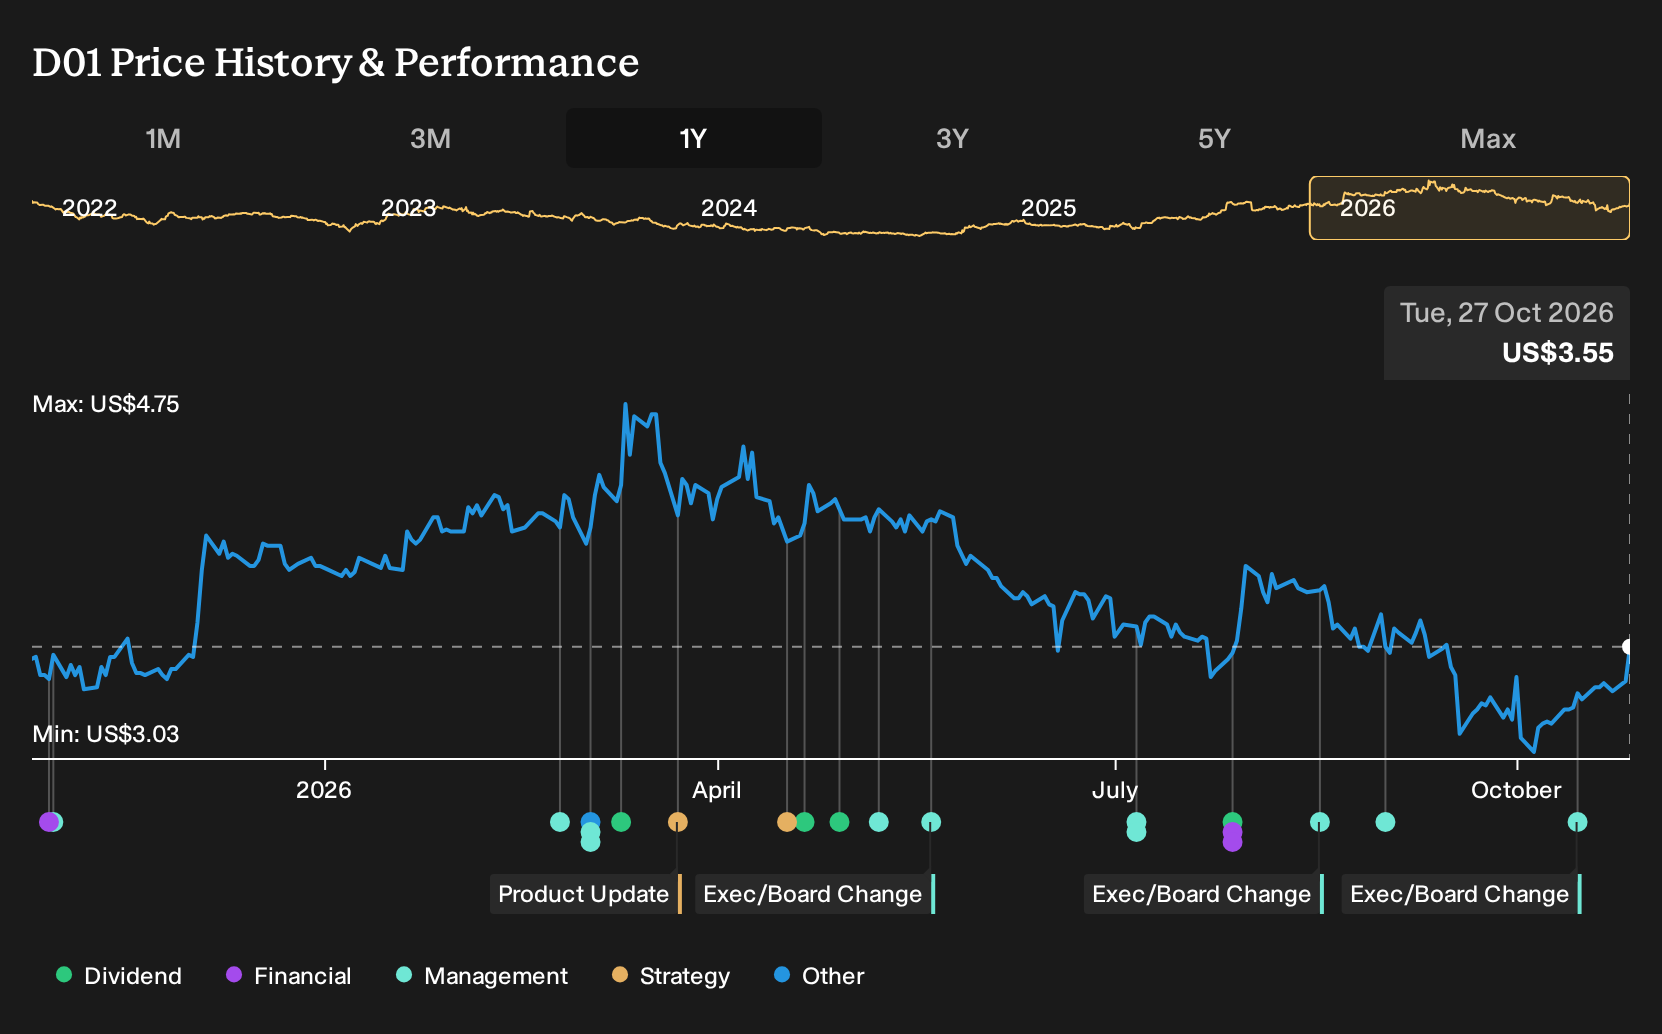
The board level refresh on 15 October 2026 matters here. DFI Retail Group Holdings added Shin Hwee Chua as an Independent Non Executive Director and Audit Committee member, and brought Achal Agarwal and Alia Gogi into the Remuneration and Nominations Committees. Fresh oversight tapping deep Asia retail, fashion and beauty experience should directly link to how effectively the Starbucks platform, Health and Beauty chain and broader omni channel push get run.
For you as a shareholder, this governance change intersects with the main catalysts, especially mix shift toward higher margin health focused formats and e commerce, plus the integration of new restaurant brands. Stronger committees can tighten capital allocation around store rollouts, price investments and digital projects, which matters when earnings are forecast to decline over the next three years and when special dividends have already raised questions about financial flexibility.
DFI Retail Group Holdings' narrative projects US$9.0b revenue and US$349.4 million earnings by 2029. This assumes revenue remains broadly flat and implies an earnings increase of about US$114.7 million from current earnings of US$234.7 million.
Uncover how DFI Retail Group Holdings' fair value indicates a 44% potential upside to its current price before that discount to expectations closes.
Exploring Other Perspectives
One point the more cautious analysts keep circling is Starbucks integration risk. While the baseline story leans on DFI Retail Group Holdings lifting margins, the bearish camp was already modelling earnings easing from about US$390.0 million to US$294.4 million by 2029 on roughly flat US$8.7b revenue. Those views came before this Q3 update and board refresh, so treat them as a starting point and explore how opinions might shift from here.
Explore 3 other DFI Retail Group Holdings fair value estimates, including one that suggests as much as 26% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your DFI Retail Group Holdings research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for DFI Retail Group Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DFI Retail Group Holdings' overall financial health at a glance.
Looking For More Ideas Beyond DFI Retail Group Holdings?
Once you have a handle on DFI Retail Group Holdings, it can help to widen the lens and compare it with other businesses that share similar qualities or offer a different balance of risk and income. The Simply Wall St Screener is a simple way to surface opportunities that match the kind of portfolio you want to build.
- If you want growth potential at lower price points, check out 124 elite penny stocks with strong financials that combine smaller market caps with stronger financial profiles than many peers.
- For investors who care most about quality at a fair price, filter for stocks using the 195 high quality undervalued stocks and see which companies pair healthier balance sheets with attractive valuations.
- When capital preservation is front of mind, focus on resilience first and use the 223 resilient stocks with low risk scores to find businesses with more robust risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com