


Anthropic’s push toward a potential US$1.5 trillion to US$2 trillion IPO has turned attention to the less glamorous but essential picks and shovels of AI, the companies supplying the chips, power and cloud capacity that make models like Anthropic’s possible. Investors do not just face hype. There is a real fork in the road between firms that benefit from this demand spike and those left behind. This article walks through three stocks from our AI Infrastructure Enablers screener that appear especially exposed to this Anthropic story and explains why their role in the AI build out could matter for your portfolio decisions.
The three stocks below are just a sample of what the AI infrastructure theme covers, and the full screen surfaced 70 more companies with equally compelling narratives that are not broken out in this article. To see the broader opportunity set, head straight into the AI Infrastructure Enablers (Semiconductors, Data Centers, and Cloud Providers) screener to analyze, compare, and identify which AI infrastructure enablers best match your own conviction.
Powerchip Semiconductor Manufacturing (TWSE:6770)
Overview: Powerchip Semiconductor Manufacturing runs foundry style chip production, testing, and packaging that feeds servers, networking gear, and AI focused hardware worldwide.
Operations: The business generates NT$55.2b in semiconductor revenue, with NT$27.5b from Taiwan, NT$11.8b from the United States, NT$11.0b from China, and NT$4.9b from other markets.
Market Cap: NT$327.0b
Powerchip Semiconductor Manufacturing gives you pure exposure to the manufacturing and packaging side of AI infrastructure, from servers to memory. Recent six month revenue of NT$30,862.65 million and a swing from loss to NT$17,522.35 million in profit indicate that AI driven demand is already reflected in its order book. One unresolved pressure could still reshape how those gains flow through to future margins.
Those margin questions make it worth seeing the 4 key rewards and 2 important warning signs before Anthropic linked demand potentially reshapes how Powerchip Semiconductor Manufacturing is being priced by the market.

Nanya Technology (TWSE:2408)
Overview: Nanya Technology produces DRAM and other memory chips used in AI data centers, servers, consumer electronics, mobile devices, industry, and cars.
Market Cap: NT$1.52t
Nanya Technology fits neatly into the AI infrastructure theme because memory is the quiet workhorse that lets those huge training runs actually happen, and management is already steering a bigger slice of its output toward that demand.
"Nanya Technology is transitioning a larger share of its output toward AI infrastructure and server applications, with this segment already above 20% of revenue and targeted to reach 40% to 50% by 2029 to 2030, which could support revenue growth and help sustain margins as mix shifts to higher value products."
What really matters next is how one large spending and capacity plan ripples through future pricing power, profitability, and investor patience.
Those expansion bets, and how they might accelerate or strain the next few years of returns, sit at the center of the full narrative for Nanya Technology, including where risk could be mispriced.

Winbond Electronics (TWSE:2344)
Overview: Winbond Electronics designs and sells specialty DRAM and flash memory used in data center, networking, and edge devices supporting AI workloads.
Operations: Winbond Electronics generates about NT$29.8b from logical products, NT$49.5b from flash memory, and NT$65.4b from customized memory solutions.
Market Cap: NT$733.5b
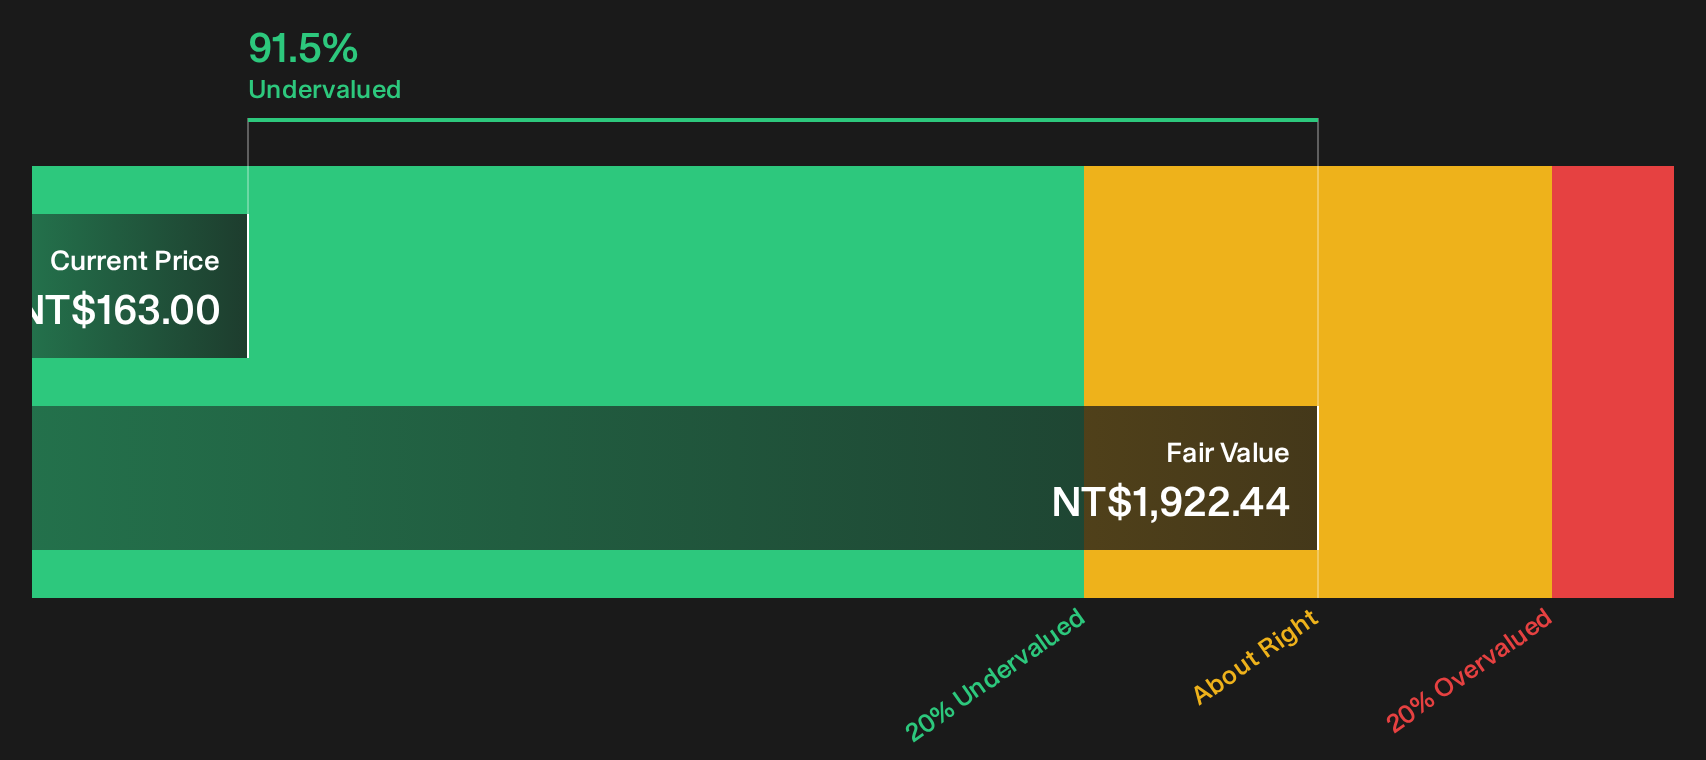
Winbond Electronics provides focused memory exposure within the AI infrastructure theme, with specialty DRAM and flash supporting compute, storage, and networking hardware. Profitability has returned, and the stock trades below some intrinsic value estimates, while future pricing power remains an important factor that could significantly influence how much potential upside reaches shareholders.
That potential upside only matters if you see how pricing power could evolve, so start with the 4 key rewards and 1 important major warning sign to spot where the risk reward trade off might be shifting.
Seeking Fresh Alternatives Before They Fly
Breakout themes move fast and the best entry points rarely stay under the radar for long. Scan fresh momentum ideas before the crowd catches up and act now.
- Spot smaller stories building quiet momentum before headlines start chasing them by running your filters through the 124 elite penny stocks with strong financials while information is still fresh.
- Explore the next wave of computing breakthroughs by scanning the curated 25 quantum computing stocks before attention and valuations shift.
- Identify potential income workhorses while yields are still holding up by screening the curated 224 dividend fortresses and position yourself before demand changes.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com