


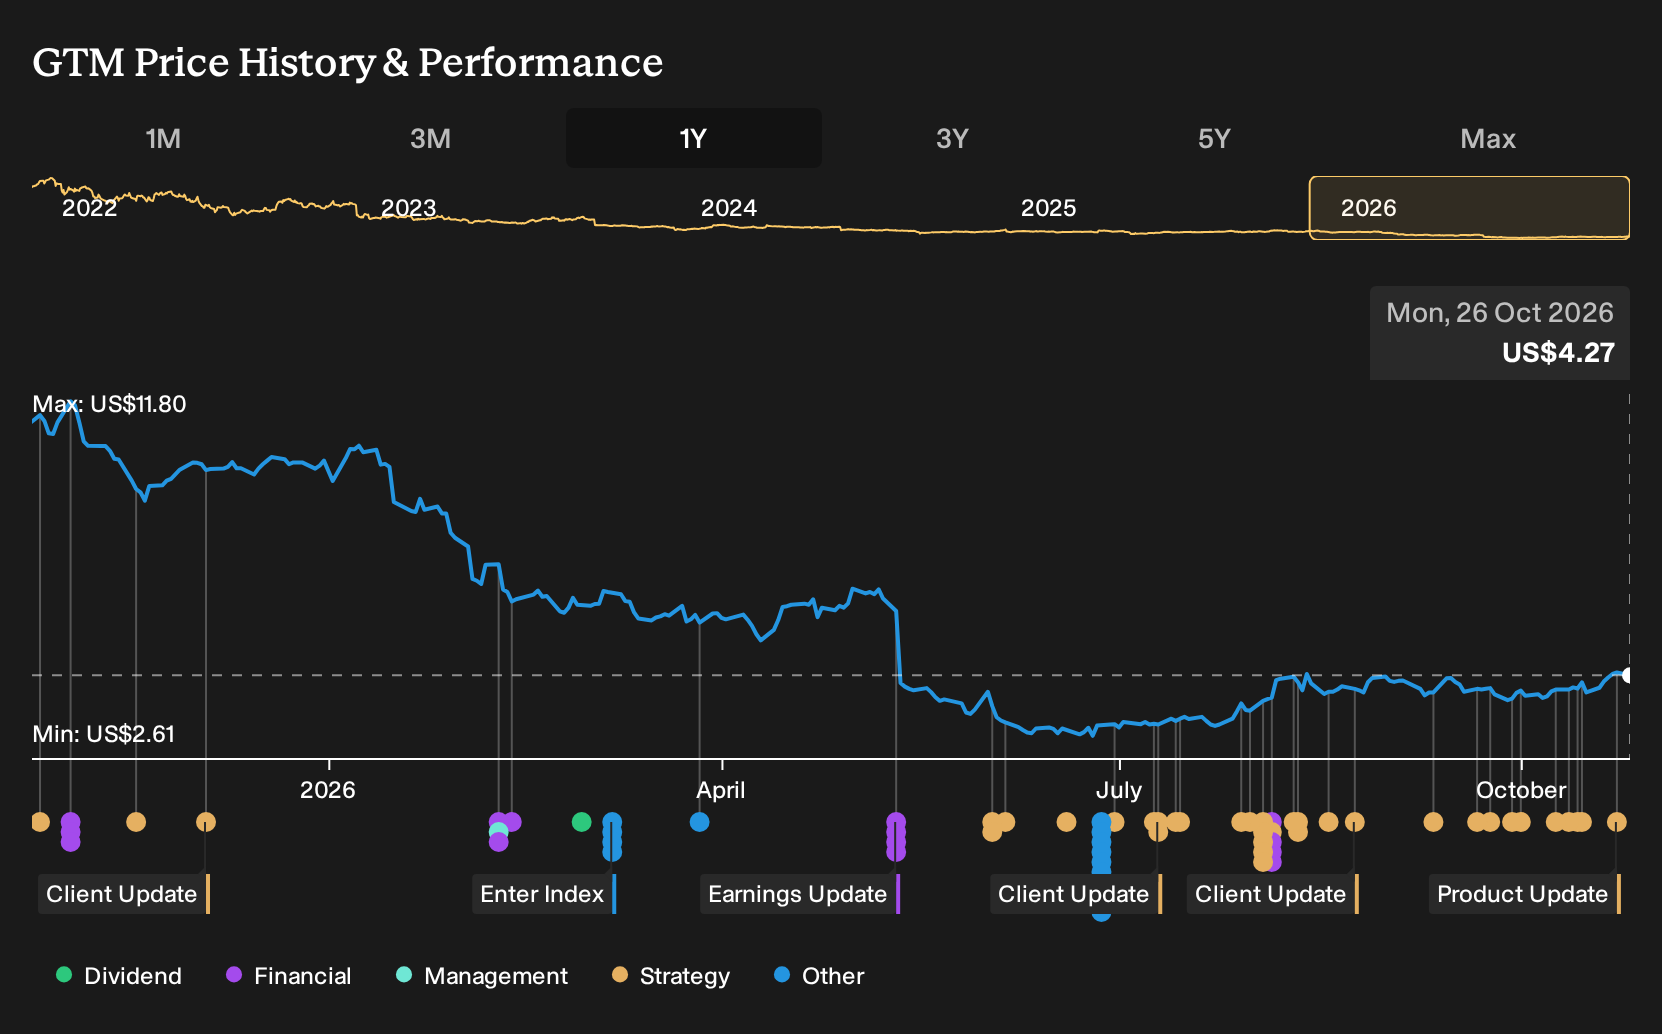
If you had looked at ZoomInfo Technologies in late October 2025 and decided to wait for clearer evidence on AI driven go to market tools, you avoided a rough ride. For ZoomInfo Technologies shareholders, the loss over the past year was 61.4%, including dividends. With that kind of drop and a later revenue guidance cut now in the news, which early assumptions about AI demand, pricing models, or client retention were already on record and worth challenging at the start?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
ZoomInfo Technologies is not the only name tied to this theme. Zero in on 38 AI small caps and compare how each one is priced.
The Two ZoomInfo Stories Investors Were Weighing
The shares cost US$11.42 at the start of the period, and ZoomInfo Technologies sat between two very different AI heavy stories about its future.
The bullish narrative put fair value at US$15, built on the idea that Copilot and other AI features would drive higher contract values with large enterprises, raising margins as more US$100,000 and US$1 million plus customers joined the base.
The bearish view set fair value at US$6.79 and focused on risk. Management could push too hard upmarket, see SME demand fade, and rely heavily on Copilot adoption that might not arrive as expected.
What The Results Changed For ZoomInfo Technologies
ZoomInfo Technologies cut its 2026 revenue guidance and moved from a Q2 2025 net profit of US$24 million to a Q2 2026 loss of US$643.7 million, which challenged the bullish view that AI led upsell and an upmarket push would quickly support higher margins. Net margin moved from 7.8% to a loss of 207.4%, so profitability in the optimistic case remained unproven.
The hinge assumption was that AI features and pricing changes would improve earnings quality, not just storytelling. When you assess another stock built on similar claims, track net margin and guidance revisions against any AI or consumption based pitch, and see whether earnings move in the direction management has outlined.
What ZoomInfo’s Lower Price Now Assumes
Today ZoomInfo Technologies trades at US$4.35, and the selected Narrative’s Fair Value sits above that level based on its own assumptions. The current view leans on a shift toward AI agents, workflow orchestration, and buybacks rather than seat based upsell alone.
For that higher Fair Value to be reached, a buyer today would need to believe enterprise data services and automation usage can more than offset weaker downmarket seats and softer net revenue retention.
"ZoomInfo Technologies is repositioning itself as a headless go to market context layer through GTM.AI, API access, and integrations into tools such as Replit, Slack AI, and Superhuman Go. This could widen its addressable usage beyond human sellers and support new data consumption revenue streams over time, with potential implications for revenue and gross margins."
One Narrative disagrees with today's price. → See where this Narrative says ZoomInfo Technologies should trade
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 23% below our estimate - targets higher value procedures as hospitals adopt more robotic and Smart Care systems.
- Company 2 - 41% below our estimate - scales protective film manufacturing and installation as automakers and dealerships deepen direct relationships.
- Company 3 - 19% below our estimate - concentrates on hyperscale data center builds that expand backlog and strain working capital.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com