


HBT Financial stock eased 1.2% to US$36.75 after the Q3 2026 report hit, a muted move for a regional bank that just printed one of its cleanest profit quarters this year. Basic earnings per share landed at US$0.86 on revenue of US$85.1 million, while the trailing P/E sits around 15x versus roughly 11.5x for the broader US banking sector. That premium price tag relates more to the multi year earnings track and growth forecasts than to today’s slight dip in the share price.
Like the premium valuation on HBT Financial but wondering if that 15x P/E leaves limited room for error in a rate sensitive sector? Compare it with banks screened for sturdier fundamentals in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$85.1 million vs. US$59.2 million (up about 44%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$31.4 million vs. US$19.8 million (up about 59%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.86 vs. US$0.63 (up about 37%)
- Net Interest Margin, or NIM (Trailing 12 Months to Q3 2026 vs Prior TTM): 30.6% net margin vs. 33.6% net margin (margin lower year on year)
Ask Charlie what makes HBT Financial worth a premium multiple.
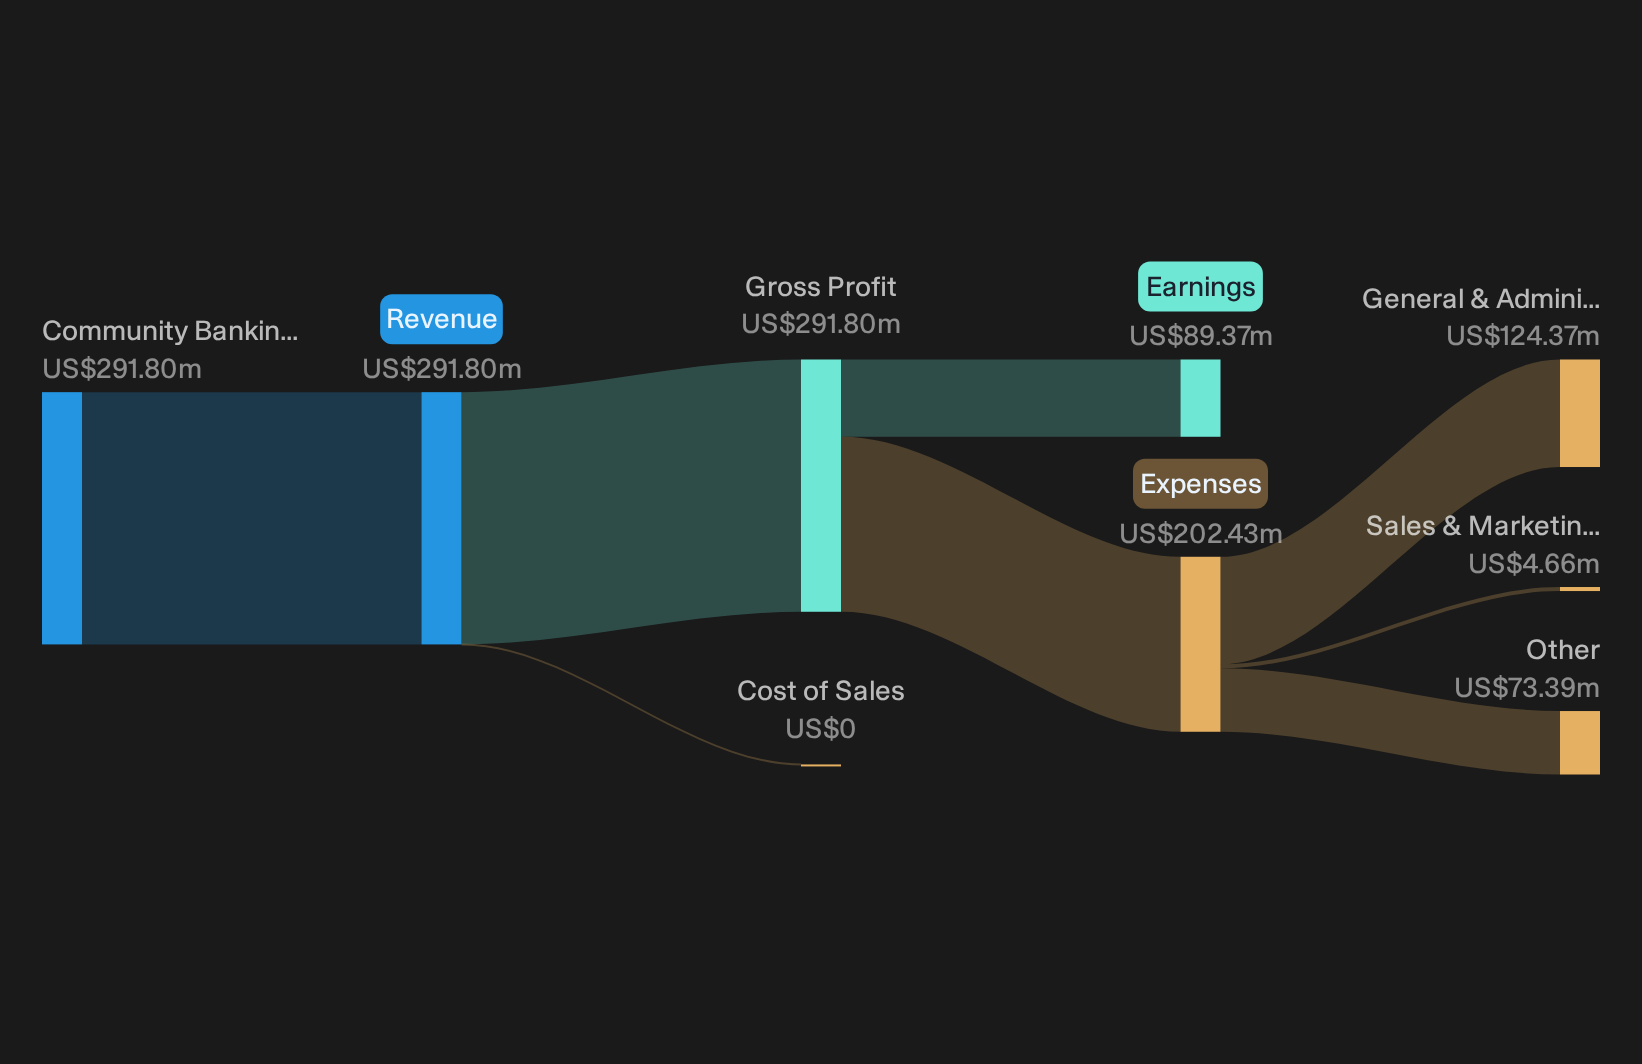
HBT Financial: Earnings Momentum And Expansion Story
For anyone leaning bullish on HBT Financial as a conservative regional relationship bank, this quarter broadly lines up with that story. Revenue of US$85.1 million and net income of US$31.4 million both moved higher year on year, and EPS of US$0.86 stepped up from US$0.63. Profitability softened a touch, with net margin easing from 33.6% to 30.6%. Even so, the business is still generating solid earnings while preparing for the Tri County acquisition, which supports the idea of a steady, earnings generating platform rather than a turnaround.
Testing The Risk Story Around HBT Financial
Bears focused on a rate sensitive, geographically concentrated lender will see a few flags yet not a broken story. The slip in net margin signals pressure on spread income, which fits concerns about funding costs and loan yields. At the same time, higher revenue and earnings suggest the current model is still holding up before Tri County folds in. The share price reaction, down about 1.2% on the day against positive 7 day and 30 day returns, points to profit taking more than a clear loss of confidence.
After a quarter where HBT Financial is managing margin pressure and preparing for an acquisition, it is fair to ask what could quietly upset that story. Review an independent risk analysis for HBT Financial which shows 1 important warning signHunt Quiet Mispricing Opportunities Now
HBT Financial just reported a steady quarter that drew mixed reactions from investors. The real opportunity is finding stocks that could be undervalued before the market closes the gap.
- Company 1 - 26% below our estimate - sells injectable treatments for weight loss and diabetes that remain difficult to access consistently.
- Company 2 - 27% below our estimate - supplies grid testing equipment and components utilities use as they replace aging systems and manage electric vehicle demand.
- Company 3 - 42% below our estimate - builds large LED boards and software adopted by venues and transport hubs shifting away from static signage.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com