


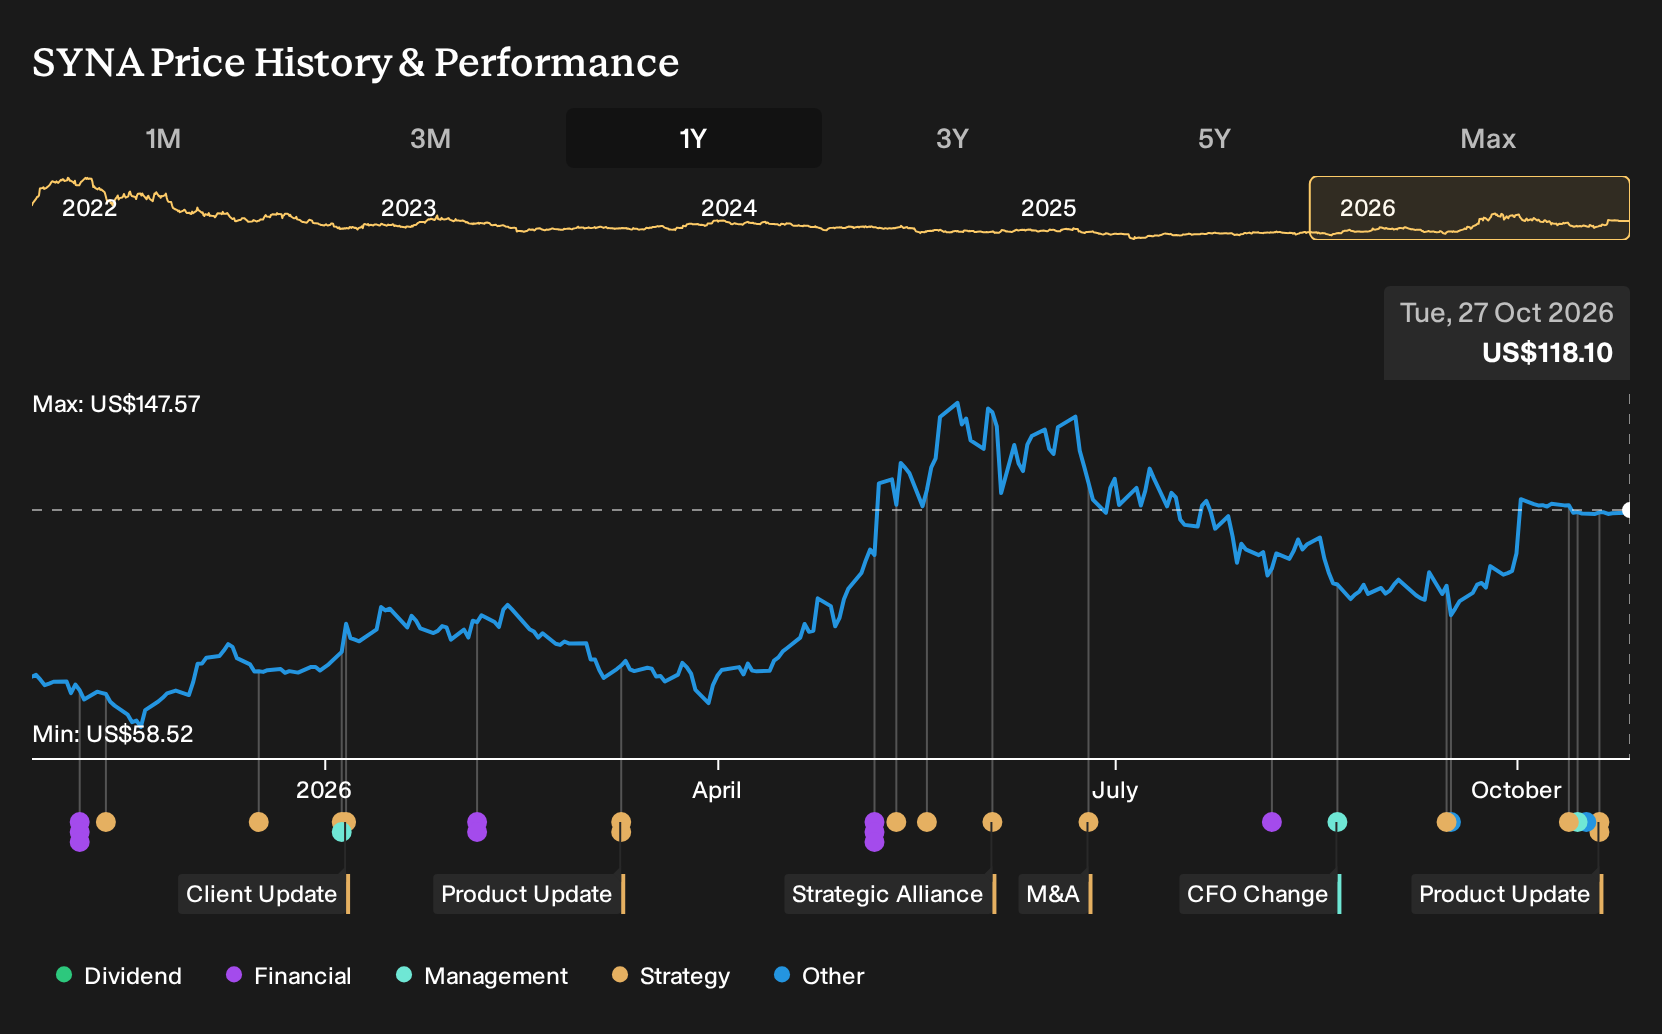
- Synaptics recently launched the Astra SR200 xMCU line and Coralboard SR platform, bringing multimodal, on-device Edge AI with integrated high-bandwidth memory, heterogeneous compute, and an open-source Torq AI toolchain targeting wearables, sensing devices, cameras, and industrial systems.
- The combination of transformer-ready Torq AI acceleration, Coral NPU integration with Google Research, and scalable on-chip DRAM positions Synaptics to address more complex Edge AI workloads that were previously constrained by traditional MCU memory and power limits.
- We will now examine how Synaptics' multimodal Astra SR200 and Coralboard SR launches could influence the existing Edge AI investment narrative.
Synaptics Investment Narrative Recap
To own Synaptics, you need to believe its shift toward Core IoT and Edge AI can eventually turn today’s losses of $490.8 million on $1.2b of revenue into durable earnings. The critical near term catalyst is whether Astra xMCUs and Coralboard SR convert into broad design wins as IoT customers look for richer on-device AI without jumping to full application processors.
The largest near term risk is execution. Synaptics is still early in scaling channels from dozens of customers to thousands, while debt is not well covered by operating cash flow and industrial IoT is described as a weaker area. If Astra and Coralboard adoption is slow, that combination could keep profitability elusive.
The Astra SR200 xMCU and Coralboard SR launch matters most right now. It directly targets the firm’s Core IoT and Edge AI thesis by offering transformer capable, multimodal processing with integrated DRAM and a common Torq toolchain. That aligns with the goal to increase silicon content per device and differentiate beyond basic connectivity or touch controllers.
What investors should watch is how this platform feeds the design funnel and whether distributor agreements like Flip Electronics help Synaptics reach more IoT and industrial customers. Any evidence that Astra and Coralboard are gaining traction across wearables, smart home, and industrial control could influence future revenue mix, while slow uptake would keep channel scale up and R&D spend as key pressure points.
Synaptics' analyst narrative points to US$1.6b in revenue and US$21.2 million in earnings by 2029, built on an assumed 9.4% yearly revenue growth rate and an earnings swing of about US$512 million from a loss of US$490.8 million today to the forecast profit.
Uncover why Synaptics' fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on physical AI and humanoid robotics as the real swing factor for Synaptics. They were already modeling about US$1.7b of revenue and US$190.4 million of earnings by 2029, far above consensus. Those estimates came before this Astra and Coralboard news, so opinions may change. You should compare both narratives and decide which assumptions feel realistic to you.
Explore 3 other Synaptics fair value estimates, including one that suggests potential upside of up to 43% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Synaptics research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Synaptics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synaptics' overall financial health at a glance.
Looking for more Synaptics-like investment ideas?
Once you have a view on Synaptics, it can help to compare it with other stocks that share similar qualities, whether you care most about value, resilience, or balance sheet strength. The Simply Wall St Screener lets you filter for those traits directly so you can build a watchlist that actually reflects your own investing checklist.
- If you want potential value combined with fundamentals that pass a quality bar, start with a curated set of 29 high quality undervalued stocks that may deserve a closer look beside Synaptics.
- For readers who care more about stability and risk control, filter the market down to a 30 resilient stocks with low risk scores and see which ones fit your preferred downside profile.
- When financial resilience matters most, compare Synaptics with a list of solid balance sheet and fundamentals (24 results) and see which businesses line up with your comfort level on debt and cash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com