


- Energy Fuels secured conditional credit approval from Export Finance Australia and the Australian National Reconstruction Fund Corporation for up to A$180 million to support construction of Phase 1 of the Donald Rare Earth and Mineral Sands Project, a key upstream asset in its mine to magnet rare earth supply chain.
- The funding milestone directly targets the Donald Project, which is intended to supply rare earth feedstock for Energy Fuels' processing and magnet related manufacturing ambitions, tightening the link between mining assets and planned downstream capacity.
- We will now look at how Energy Fuels' investment narrative could shift as conditional A$180 million project financing enters the picture.
Energy Fuels Investment Narrative Recap
To own Energy Fuels, you need to believe in a multi asset story that ties uranium production, rare earth processing and heavy mineral sands into one integrated platform. The conditional A$180 million approval for the Donald Project tackles one of the big bottlenecks, long term rare earth feedstock, and supports the mine to magnet vision without yet changing day to day uranium operations.
The key near term swing factor still sits in execution, specifically getting higher grade uranium output and rare earth separation volumes running efficiently at White Mesa. Funding and permitting risk around Donald and other projects remain front and center. The new conditional financing reduces some uncertainty on capital, but schedule slippage or weaker project economics would still be a major overhang.
The conditional backing from Export Finance Australia and the Australian National Reconstruction Fund Corporation is the announcement that matters most here. It directly links to the earlier concern that Energy Fuels needs substantial external capital for Donald and similar projects, or risk slower progress and potential dilution if equity became the only option.
With this credit approval in place, attention shifts toward proving bankable offtakes, locking in construction terms and eventually reaching a final investment decision targeted by the end of 2026. That path is still execution heavy. Any delay in moving from conditional to final financing, or in bringing Donald ore into the rare earth circuit, would keep the feedstock risk alive and could temper how quickly the broader mine to magnet story develops.
Energy Fuels' current analyst narrative points to forecast revenue of US$550.8 million and expected earnings of US$191.1 million by 2029, based on an assumed 73.3% yearly revenue growth rate and a swing in profitability from a loss of US$81.7 million today to that 2029 earnings figure. This implies an earnings increase of roughly US$272.8 million over the period.
Discover how Energy Fuels' fair value indicates a 230% potential upside to its current price that may not last much longer.
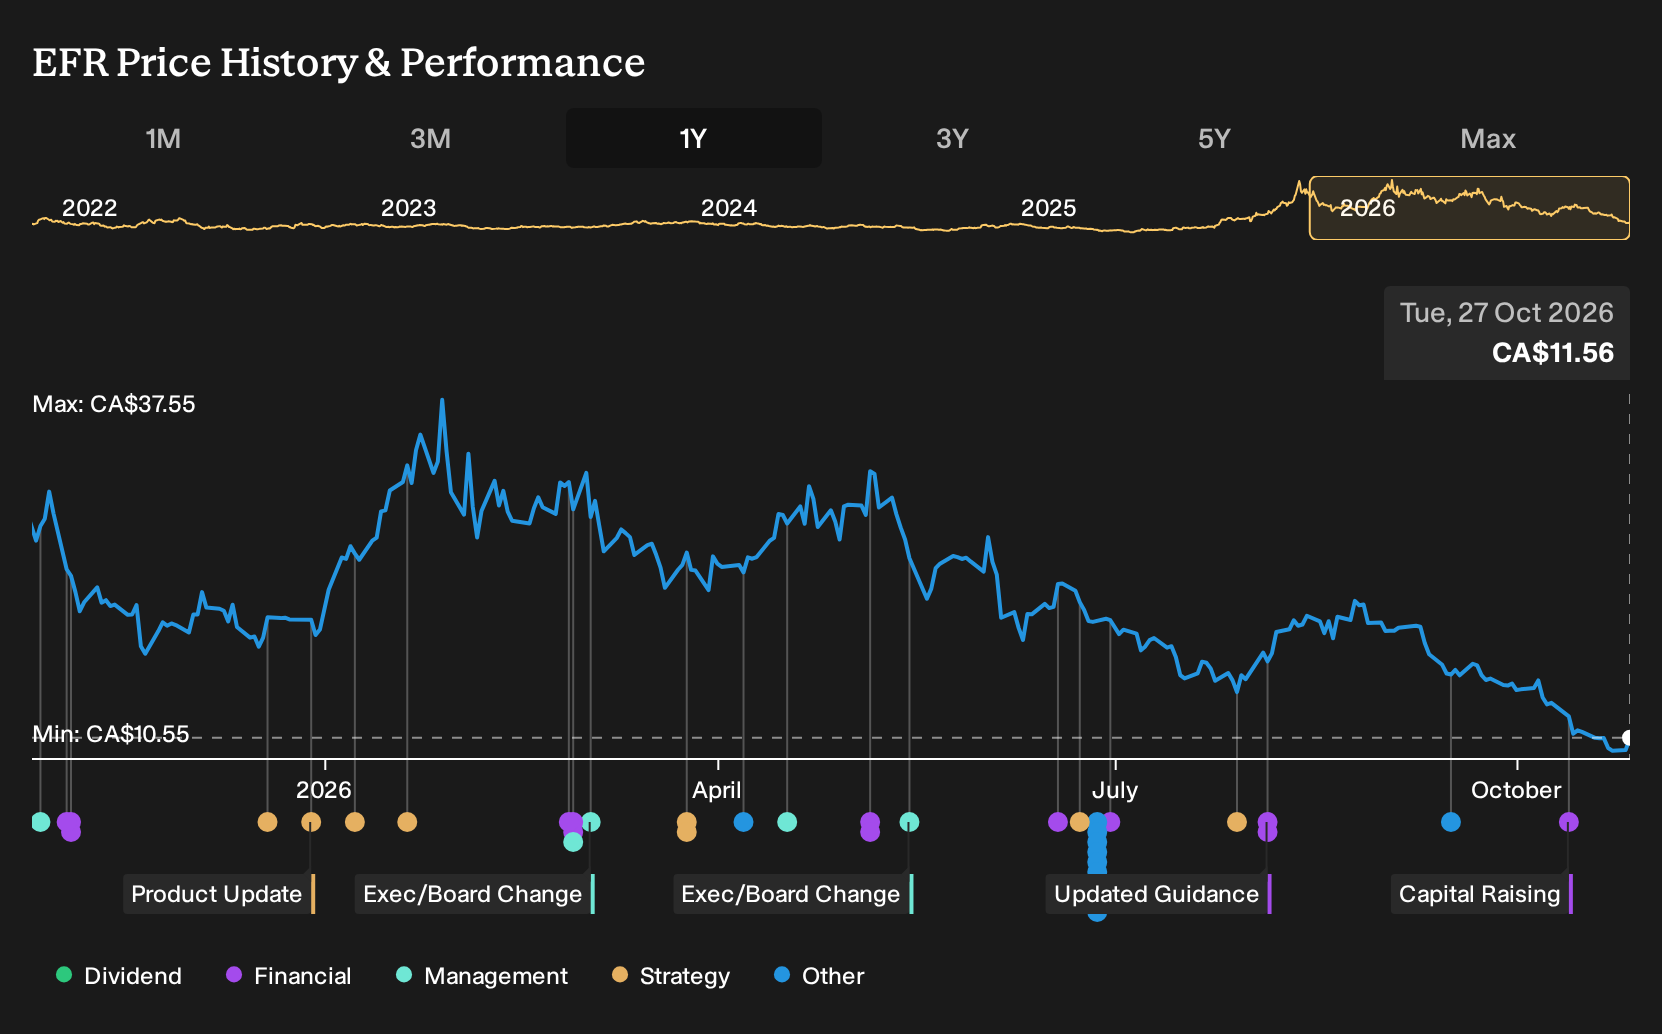
Exploring Other Perspectives
One alternate view on Energy Fuels puts the Donald Project financing inside a much bigger rare earth build out. The most optimistic analysts were already modeling revenue of about US$718.0 million and earnings near US$229.1 million by 2029, well above consensus. Those projections did not yet factor in this A$180 million credit approval, so opinions may shift as the story evolves.
Explore 4 other Energy Fuels fair value estimates, including one that suggests as much as 289% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Energy Fuels research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Energy Fuels. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Energy Fuels' overall financial health at a glance.
Looking For More Ideas Beyond Energy Fuels?
Energy Fuels is one way to gain exposure to critical materials and nuclear themes, but your portfolio might benefit from a mix of different business models, balance sheet profiles and income characteristics. The Simply Wall St Screener can help you filter that wider universe into a short list that fits your approach.
- If you care most about resilience and capital preservation, start with a 8 resilient stocks with low risk scores that could help dampen portfolio volatility when individual holdings move around.
- If balance sheet strength is non negotiable for you, look through the list of solid balance sheet and fundamentals (7 results) and focus on companies where financial footing is central to the thesis.
- If you want ideas that the wider market might be overlooking, work through a 9 high quality undiscovered gems and see which fundamentals catch your eye.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com