


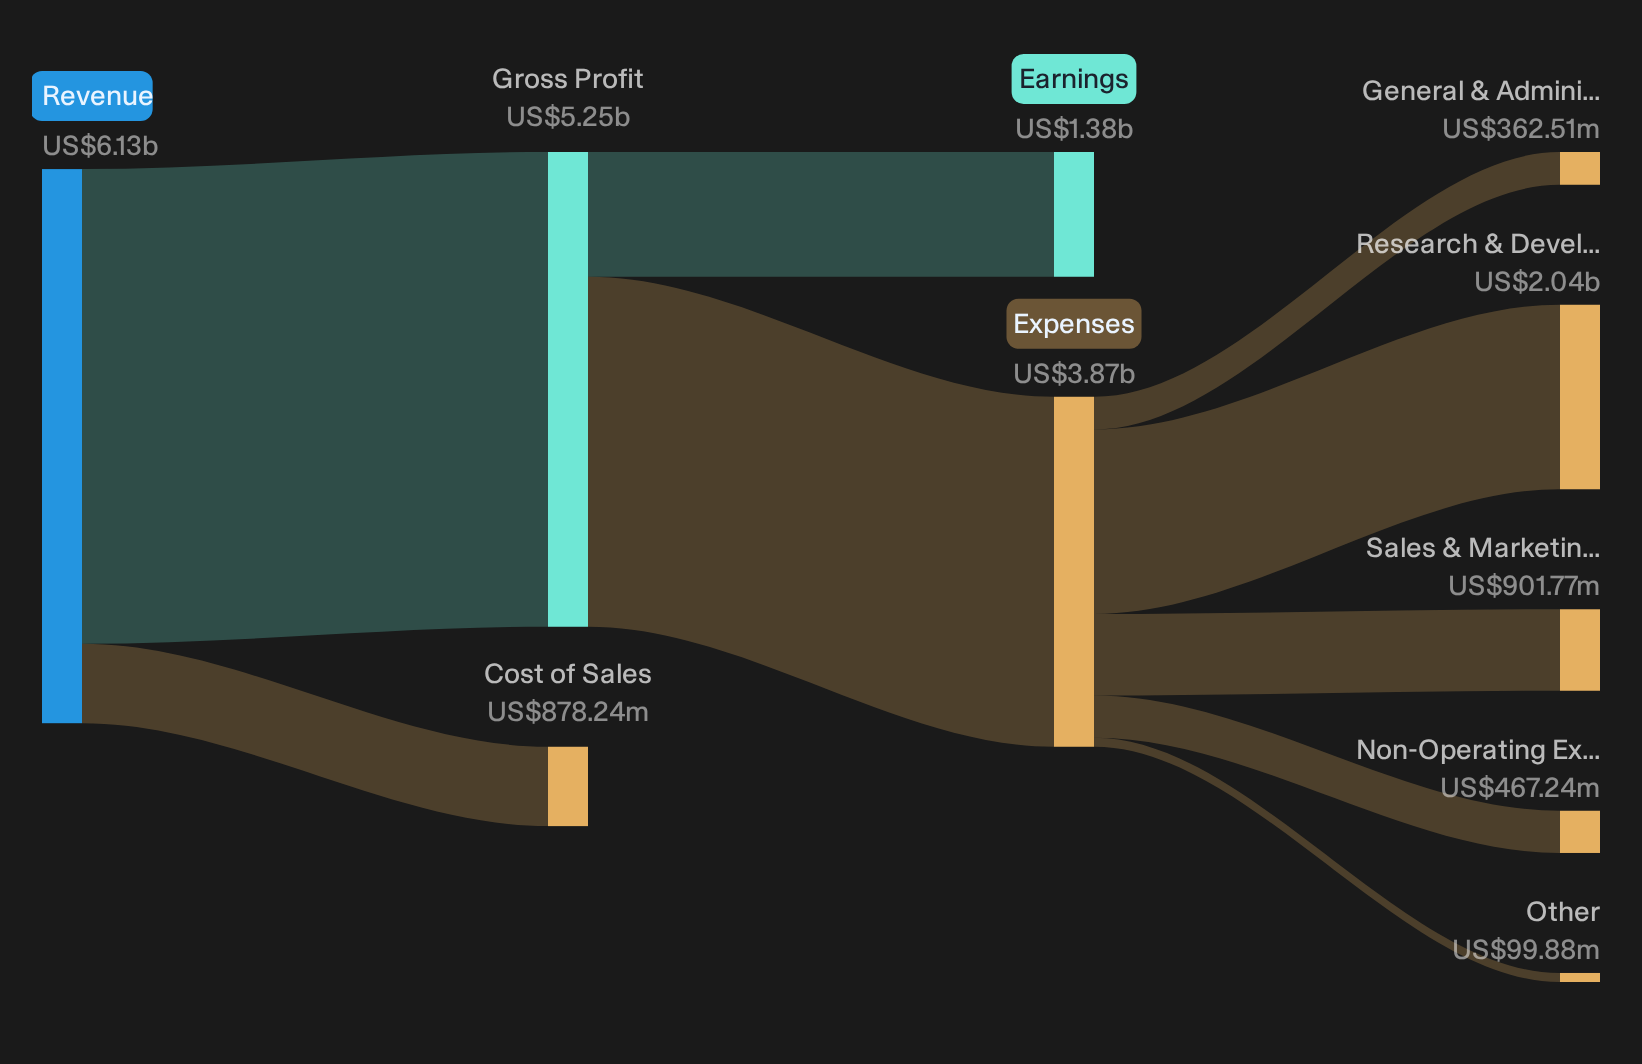
Cadence Design Systems just dropped its Q3 2026 scorecard and the stock ripped 6.5% to about US$343 by the close. The reaction looks powered less by headline EPS and more by what sits underneath. Revenue came in at US$1.633b and the non GAAP operating margin landed at 44.1%, strong numbers for an electronic design automation heavyweight that relies on sticky software and hardware subscriptions.
For investors, the real flashpoint is sentiment colliding with valuation. A premium P/E and a fresh US$8.2b backlog create a simple question: Is that one day surge a fair repricing, or enthusiasm running ahead of the tape?
Love Cadence Design Systems' high margin profile and sticky subscription model but uneasy about paying up for a premium P/E and rich expectations? Compare those concerns with a curated screener of stocks that pair strong fundamentals with sturdier balance sheets in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue, Q3 2026 vs. Q3 2025: US$1,633.3m vs. US$1,338.8m (+22.0%)
- Net Income (Excl. Extra Items), Q3 2026 vs. Q3 2025: US$289.7m vs. US$287.1m (+0.9%)
- Basic EPS, Q3 2026 vs. Q3 2025: US$1.06 vs. US$1.06 (flat)
- Non GAAP Operating Margin, Q3 2026: 44.1% (company reported figure; prior year margin not disclosed)
Prefer clean visuals instead of searching through dense earnings tables and raw figures for Cadence Design Systems? Get the full financial picture in one place, including a clear view of valuation in our company report for Cadence Design Systems.
Cadence Design Systems: AI Milestones Start To Show Up
The bullish storyline focuses on Cadence Design Systems turning agentic AI, richer IP and system design into a bigger, higher margin platform over time. That ambition is laid out clearly.
"Bullish analysts expect Cadence Design Systems to combine agentic AI, advanced IP and system design growth drivers into a larger, higher margin EDA and hardware platform over time."
Q3 shows concrete progress. AgentStack now counts over 100 active customer engagements, with reported productivity multiples such as 34x at Renesas and up to 5x faster design cycles at Nokia. IP and System Design & Analysis each posted growth above 20%, while the non GAAP operating margin of 44.1% reflects operating leverage from this broader portfolio.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Cadence Design Systems: AI Monetization Test Still Unproven
Bearish skeptics worry that Cadence Design Systems can show eye catching AI case studies yet still fall short on durable monetization.
"Agentic AI offerings such as ChipStack, ViraStack and AuraStack are showing strong early productivity gains for customers, yet if Cadence cannot convert these pilots and engagements into durable, high quality recurring contracts at scale, then the expected uplift in software and hardware bookings may not materialize and earnings expansion could lag current expectations."
Q3 partly pushes back on that concern. Recurring revenue rose 18% and backlog reached US$8.2b, helped by more than 100 active AgentStack engagements. Even so, Cadence did not break out AI specific contract value, so the precise revenue lift from agentic tools remains hard to verify.
Hunt Quiet Dislocations Now
Cadence Design Systems just saw a sharp share price move that challenges how much optimism is already reflected. The real opportunity is finding potentially mispriced companies before any valuation gap narrows.
- Company 1 - 34% below our estimate - uses new high horsepower engine capacity investments to pursue extended data center power arrangements.
- Company 2 - 31% below our estimate - leans on control of a leading GPU architecture and software stack embedded in major AI customer plans.
- Company 3 - 41% below our estimate - expands dedicated film manufacturing and installer networks so automakers and dealers bundle recurring protection packages.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com