


Noble stock took a hit today, dropping 5.4% to close at US$45.22, just one trading session after releasing Q3 2026 results. That reaction suggests investor frustration with near term profitability rather than any collapse in the business story.
The headline is blunt. Noble reported a Q3 loss, with basic earnings per share of US$0.73 and net income excluding extra items down US$117.0 million. Against a backlog of US$6.7b and a fresh US$0.50 dividend declaration, the selloff appears to focus on cash generation and margin pressure rather than the long cycle opportunity.
Love Noble’s long cycle backlog but concerned about near term losses and cash generation? Compare that setup with our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$728.8 million vs. US$757.4 million (fell 3.8%)
- Net Loss, Excl. Extra Items (Q3 2026 vs. Q3 2025): loss of US$117.0 million vs. loss of US$21.1 million (loss widened by 454.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.73 per share vs. loss of US$0.13 per share (loss per share increased 449.6%)
- Trailing 12-Month Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025 TTM): profit of US$53.7 million vs. profit of US$309.0 million (fell 82.6%)
Prefer clean charts instead of another wall of earnings tables and footnotes? See Noble’s full picture in an easy visual format, with a clear view of its balance sheet strength and capital structure inside our company report for Noble.
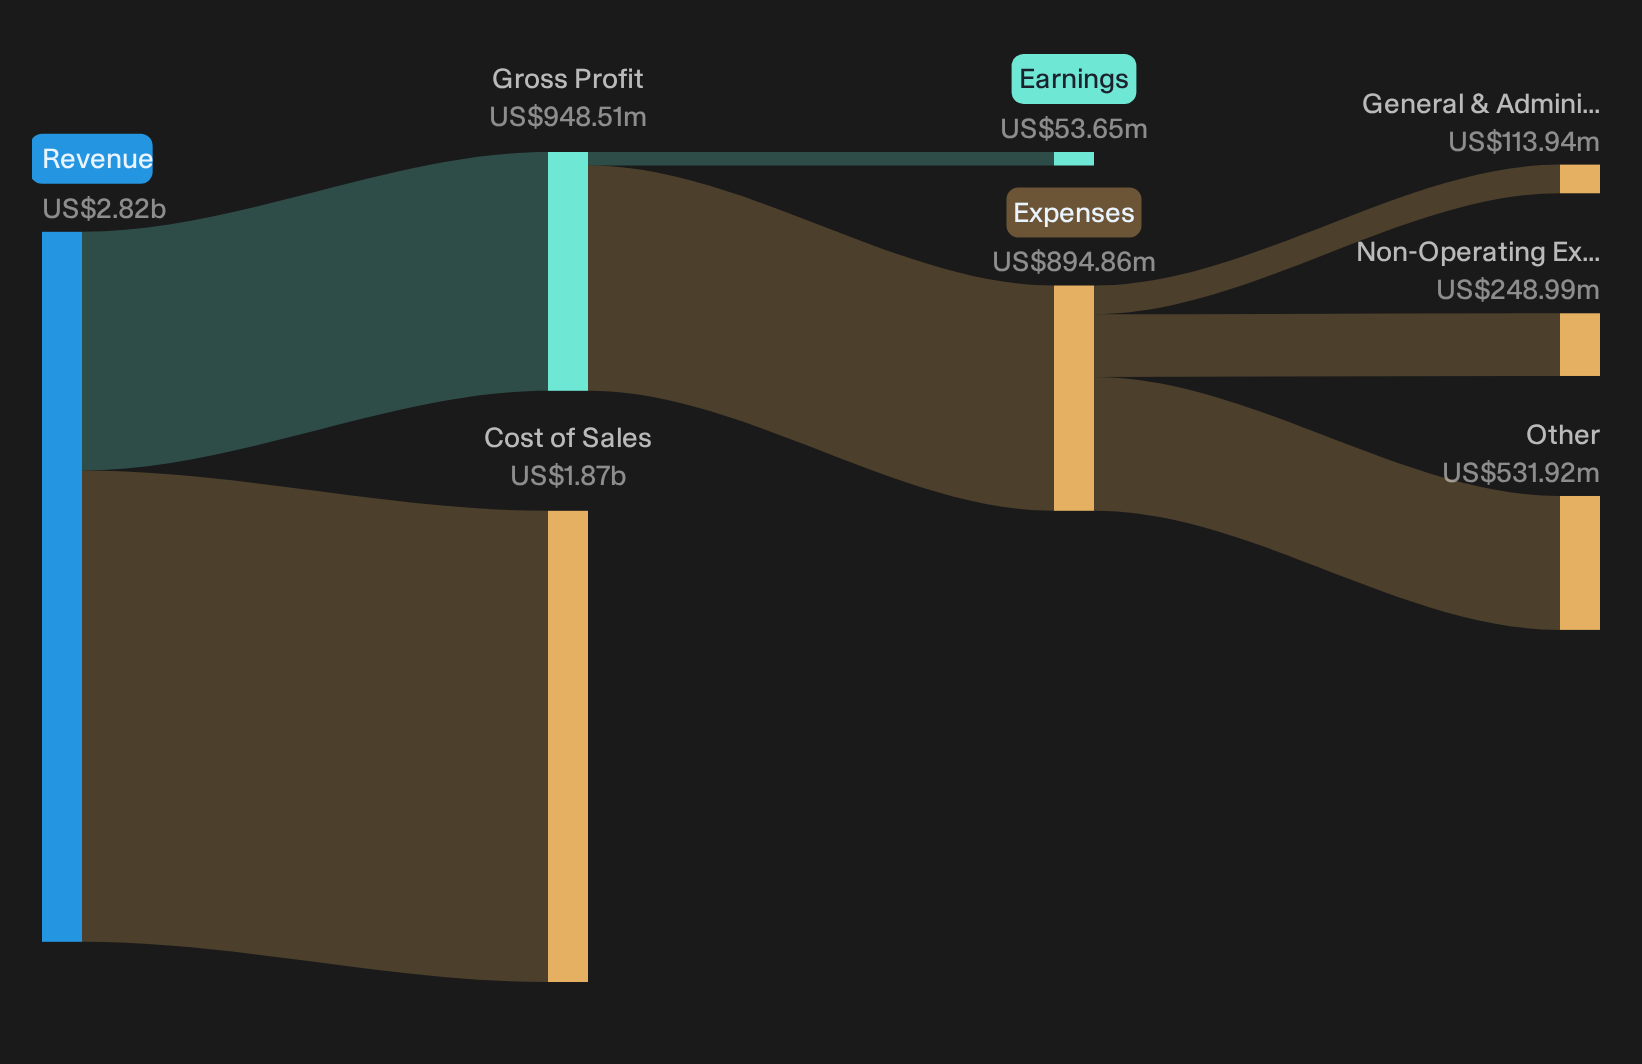
Noble’s Execution Story Meets Hard Q3 Evidence
The bullish script around Noble hinges on turning a concentrated, high spec fleet and heavy capex into much higher earnings power within a few years.
"The main thing that has to go right is that Noble executes its capital-intensive rig reactivations and upgrades on budget and on schedule so that the marketed fleet is effectively fully contracted into the late 2020s while managing contract and regulatory issues in Brazil and Qatar."
Q3 results show early progress on this execution test. Adjusted EBITDA of US$201 million came alongside roughly US$560 million of fresh awards and a US$6.7b backlog, with about US$2.6b already lined up for 2027, and 20% more contracted capacity targeted for the second half of that year.
One Narrative disagrees with today's price. → See where this Narrative says Noble should trade.
Noble Bear Case: Execution Stumbles Now Hitting Cash
Critics argue that Noble’s backlog only matters if operational issues stop interrupting contract flow and delaying returns on heavy rig spending.
"The combination of elevated 2026 CapEx guidance and lower 2026 EBITDA guidance shows how easily project timing and downtime can erode the expected payback profile, which may leave return on invested capital and future free cash flow below what current reactivation spending assumes."
The latest quarter leans toward that concern. Adjusted EBITDA of US$201 million sits against free cash flow that swung to a US$48 million outflow as 2026 CapEx guidance moved higher and EBITDA guidance slid to the lower end of the range. The 5.4% share price decline since the print suggests investors are now treating execution slippage as more than a theoretical risk for Noble.
Hunt For Mispriced Execution Stories
Noble highlights how execution risk and cash timing can significantly influence a single quarter. The real opportunity is finding stocks that may be undervalued before improved execution appears in consensus expectations.
- Company 1 - 19% below our estimate - runs franchised and company-owned teahouses while scaling overseas outlets that rely on its supply chain, brand and technology support.
- Company 2 - 46% below our estimate - converts a construction backlog tied to AI data centers and modular projects into installation work that keeps mechanical and electrical crews utilized.
- Company 3 - 31% below our estimate - turns complex electronics programs in regulated markets into manufacturing mandates as customers shift production to a single integrated design and build partner.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com