


Zip Co (ASX:ZIP) just hit a key operational milestone, extending its Best Buy partnership into every physical store across the United States and pushing its flexible payment options directly to the checkout counter.
Recent trading tells a mixed story for Zip Co. The A$1.70 share price comes after a 1-day share price return of 4.94% on the Best Buy news. However, the 30-day and year-to-date share price returns are down 14.36% and 49.25%, while the 3-year total shareholder return is very large compared with the 1-year total shareholder return decline of 58.54%. This suggests long term holders have seen big swings in sentiment as new products, leadership changes and U.S. initiatives reset expectations.
Spot opportunities shaped by the same consumer-finance forces behind Zip Co's Best Buy rollout by scanning our hand picked 15 high quality undiscovered gems.The Best Buy rollout puts hard evidence of Zip Co’s reach next to a share price that still reflects recent disappointment. Is this move a business inflection point, or simply a brief reset in sentiment before valuation takes over?
Most Popular Narrative: 58% Undervalued
On the most followed view, Zip Co’s A$1.70 share price sits well below an implied fair value of about A$4.03, putting a lot of weight on whether its partnerships and U.S. push really translate into durable economics.
Scaling distribution through partnerships and embedded finance with major merchants and platforms (such as Google Pay, Stripe, and large retailers in key verticals) is decreasing customer acquisition costs and increasing take rates, which should drive further operating leverage and higher earnings.
See why 89 investors see Zip Co as 58% undervalued.
Result: Fair Value of A$4.03 (UNDERVALUED)
Still, the bullish Zip Co narrative can quickly wobble if regulatory scrutiny in Australia or the U.S. tightens, or if bad debts climb as new products scale up.
Find out about the key risks to this Zip Co narrative.
Another View: Zip Co Through The P/E Lens
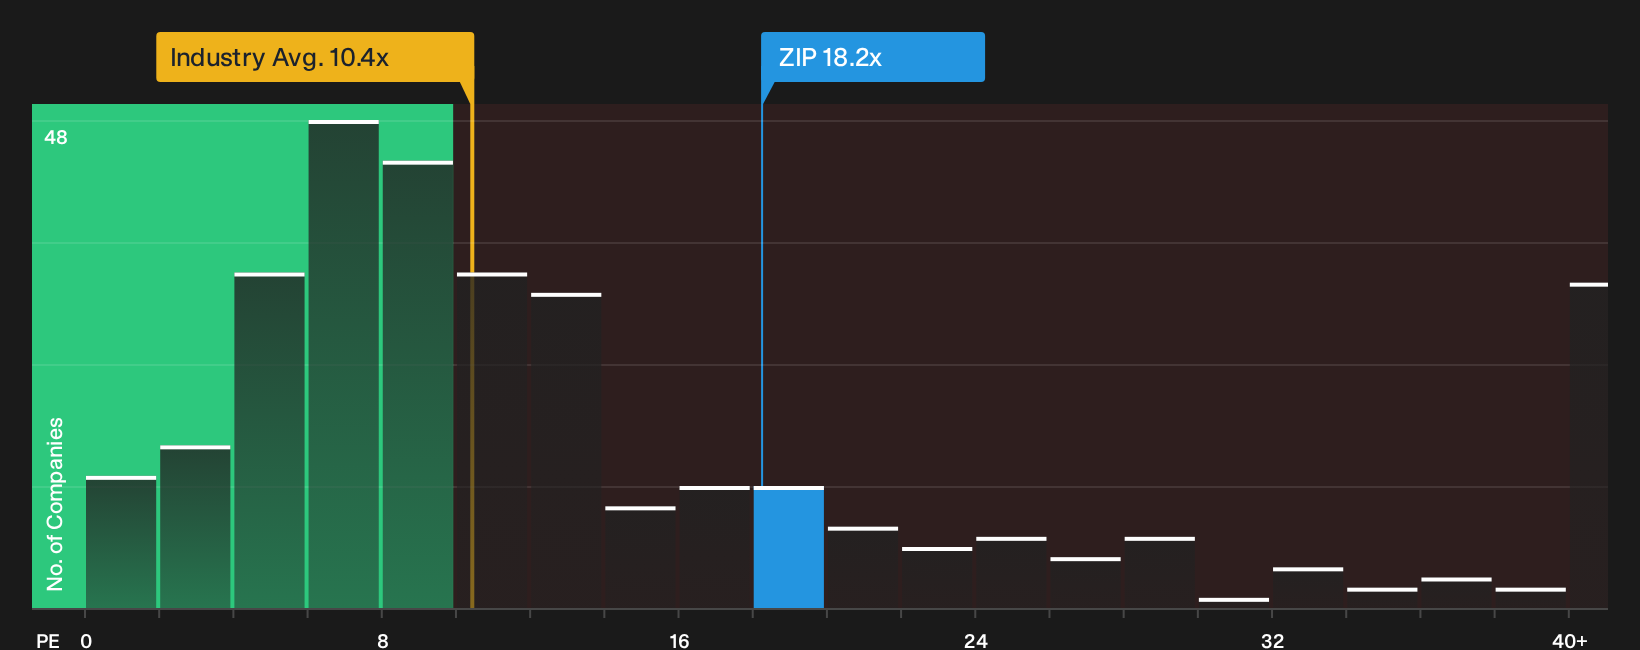
Some investors lean less on fair value models and more on what earnings multiples are saying. On that score, Zip Co looks expensive on the surface, with a P/E of 18.2x compared with 11.1x for local peers and 10.4x for the broader Global Consumer Finance group.
Yet the Simply Wall St fair ratio for Zip Co sits at 29x, which is far higher than where the market currently prices it. That gap points to a trade off between paying up versus the growth that analysts expect. Which side of that trade off feels more realistic to you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Zip Co has your attention, move quickly past the headlines and weigh the trade off between risk and upside yourself with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Zip Co?
If Zip Co has sharpened your thinking, do not stop here. Broaden your watchlist with a few focused stock ideas filtered for very different strengths.
- Target potential bargain opportunities by scanning companies filtered as 2 high quality undervalued stocks, which may trade below what their fundamentals suggest.
- Build a sturdier core by reviewing a list of solid balance sheet and fundamentals (12 results), which can help you focus on financially robust businesses.
- Dial back volatility by checking a 6 resilient stocks with low risk scores, which highlights companies with calmer risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com