


CTT Systems walked into today’s Q3 2026 report with the stock at SEK140, backed by a strong 90 day gain of about 15%. The immediate question for you is simple. Did the latest quarter justify that confidence.
The headline is clear. Q3 earnings per share landed at 1.38 SEK on revenue of SEK78.5m, while trailing net margin over the last year sat at 14.3% compared with 19.7% a year earlier. Traders may focus on the recent share price climb. Longer term holders will be watching that margin squeeze just as closely.
Like CTT Systems’ revenue and EPS but uneasy about that margin squeeze? Take a look at our list of companies that pair healthy profitability with sturdier balance sheets in the list of solid balance sheet and fundamentals stocks (207 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): SEK78.5m vs. SEK73.8m (up about 6.4%)
- Net Income (Q3 2026 vs. Q3 2025): SEK17.3m vs. SEK14.4m (up about 20.1%)
- Basic EPS (Q3 2026 vs. Q3 2025): SEK1.38 vs. SEK1.15 (up about 20.1%)
- Net Margin, trailing 12 months vs. prior year: 14.3% vs. 19.7% (compression of about 5.4 percentage points)
Prefer clean charts instead of another dense block of earnings tables and ratios for CTT Systems? View the full visual picture of how its valuation compares in our company report for CTT Systems.
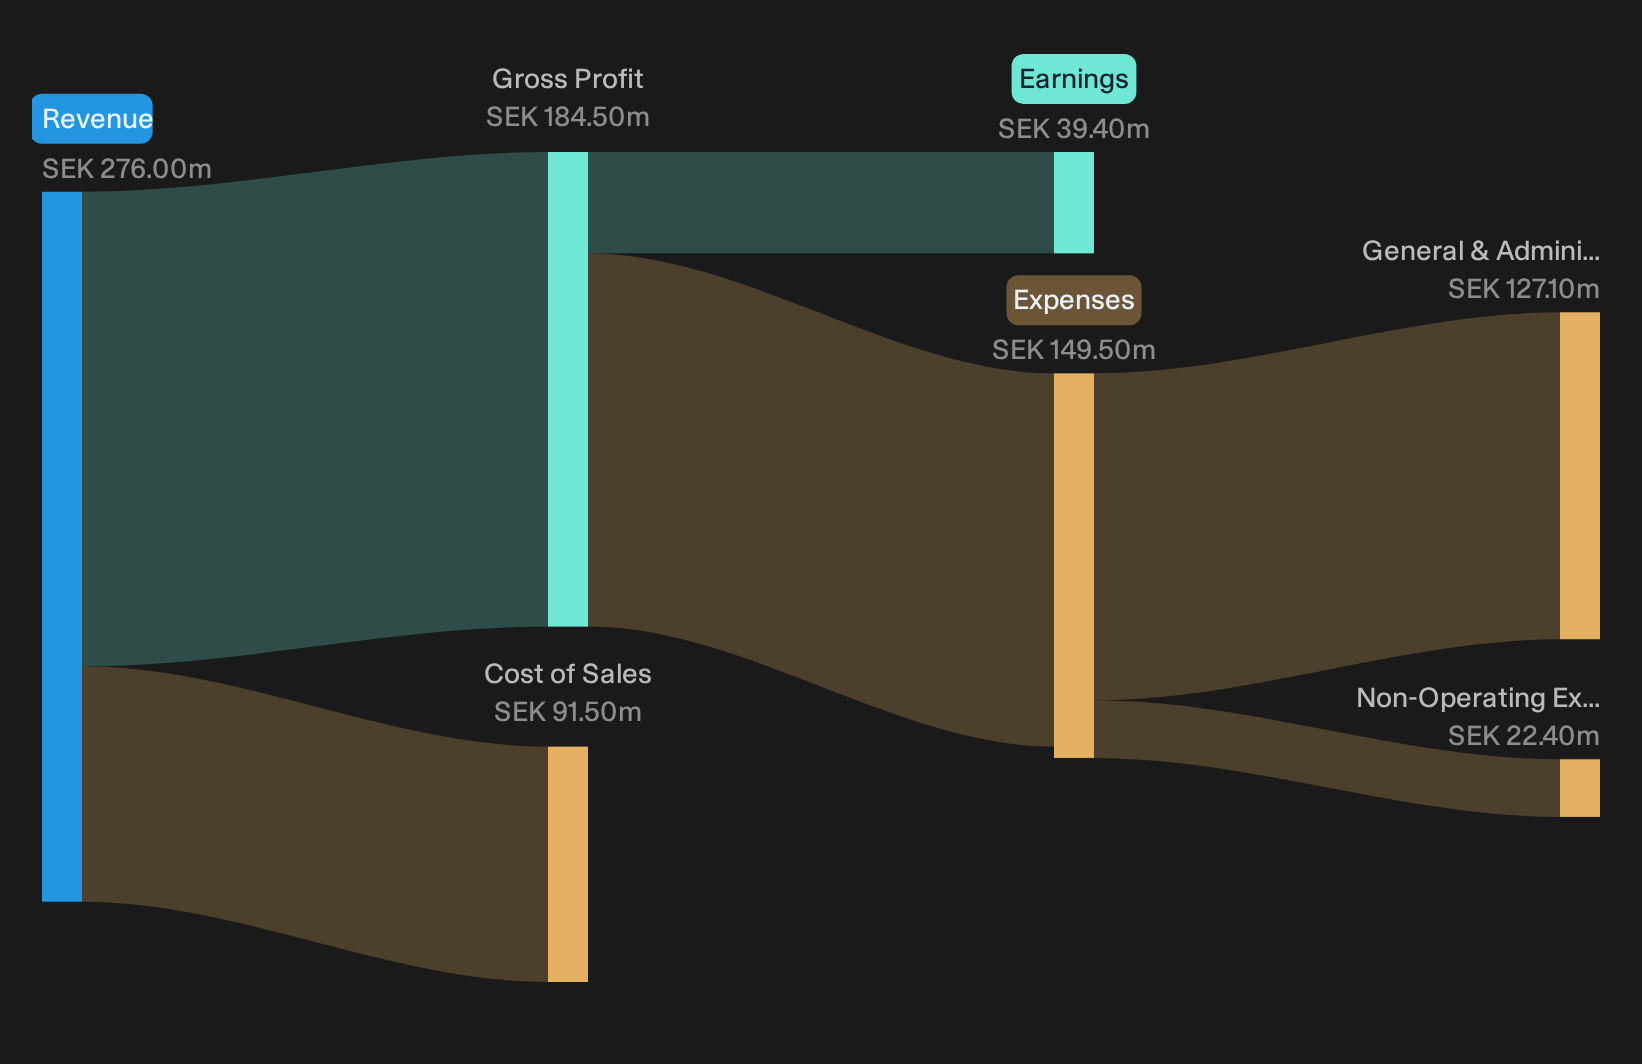
CTT Systems: Earnings Momentum Backs Optimists
For a bullish view on CTT Systems, the latest quarter offers some support. Revenue of SEK78.5m and net income of SEK17.3m both moved higher year on year, and EPS of SEK1.38 rose at a quicker pace than sales. That points to decent operational leverage. Management commentary around raised aftermarket guidance and a 30% EBIT margin in Q3 also lines up with the idea of a resilient, high value niche supplier rather than a volume driven commodity player.
Margin Pressure And Cyclicality Temper The Upside
Bearish arguments find backing in the margin picture. Trailing net margin compressed to 14.3% from 19.7% a year earlier, even with higher EPS and net income. That suggests mix, cost or pricing pressure that the headline growth does not fully show. Management also flagged timing issues in original equipment deliveries and a weak year for private jets, which fits a cyclical aerospace supplier that remains exposed to programme ramps and lumpy project pipelines.
After dividend coverage already looks thin, are margin trends and aerospace cyclicality just early signals of deeper fragility? Review our full risk analysis for CTT Systems which shows 1 important warning signHunt For Quiet Mispricings
CTT Systems just showed how earnings momentum can sit alongside margin uncertainty in one stock. The real opportunity sits in finding companies that could be mispriced before sentiment catches up.
- Company 1 - 21% below our estimate - uses acquisitions and digital tools to shift a traditional distributor toward higher margin services and data driven projects.
- Company 2 - 42% below our estimate - scales large LED installations as demand grows for software tied scoreboards, transit signage and youth sports experiences.
- Company 3 - 38% below our estimate - builds a device recommerce platform that plugs directly into government trade in subsidies and retailer take back programs.
Those are three of them. See the full list of 195 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com