


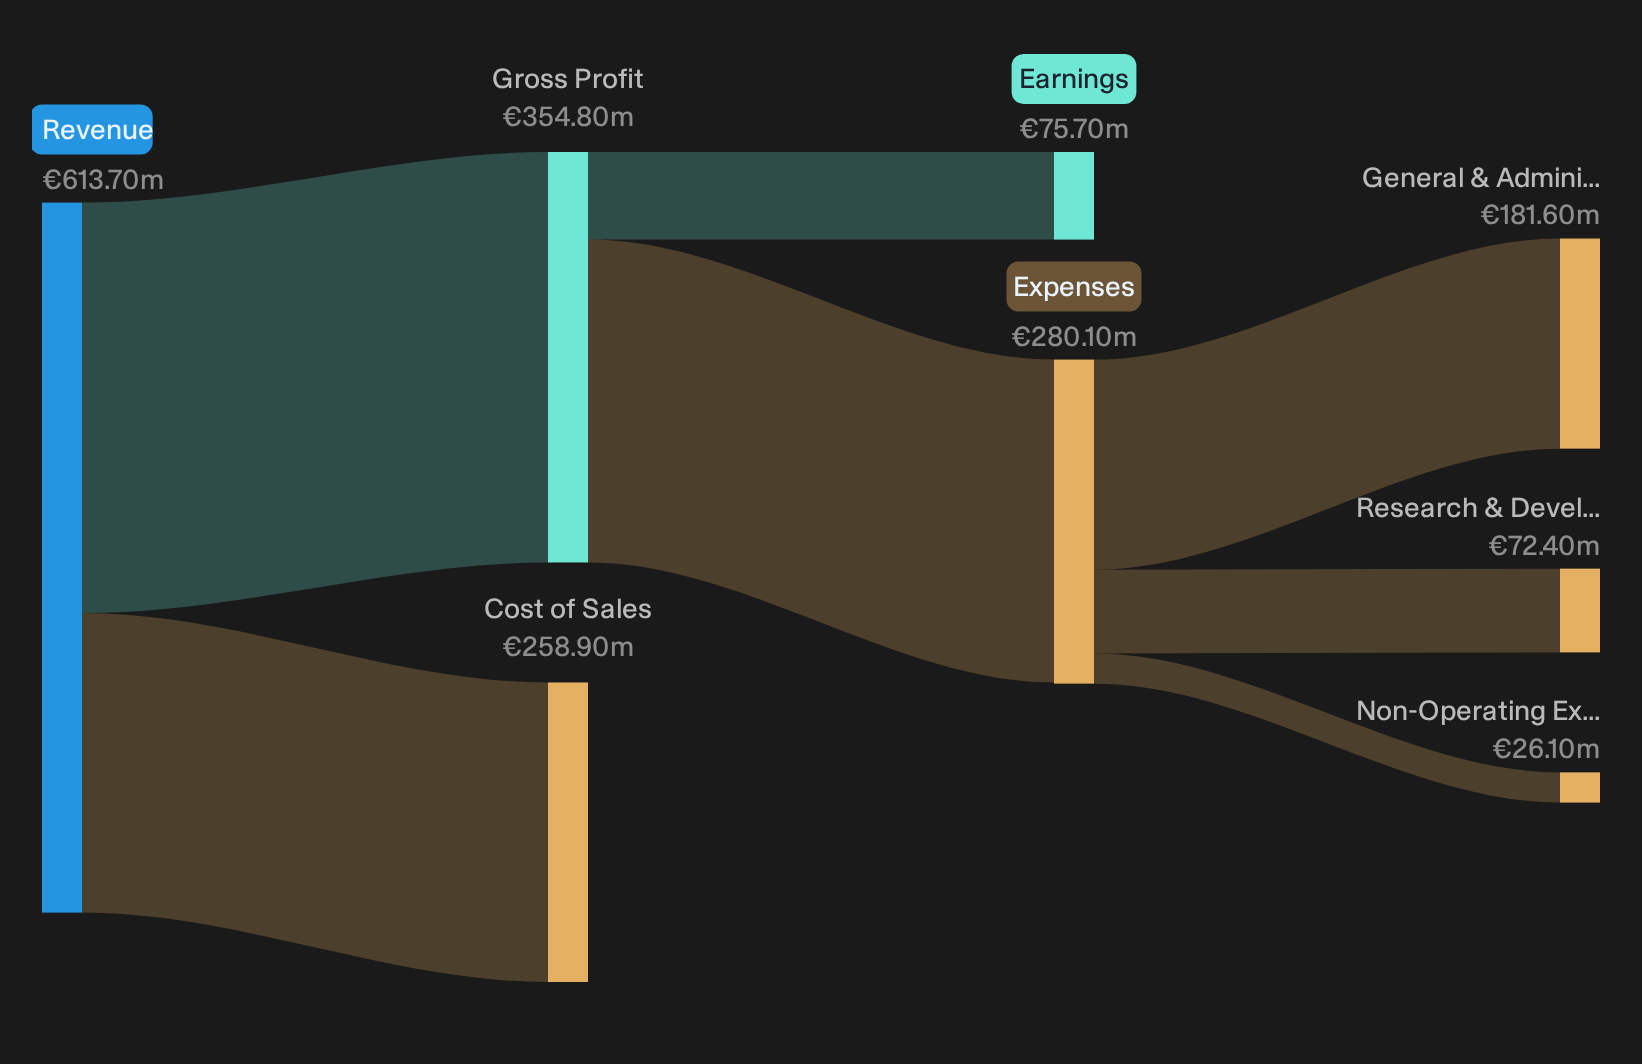
Vaisala Oyj stock closed today at €66.2, capping a 22.6% gain over the past three months, just as Q3 2026 results landed with record profitability. The quarter delivered €162.9m in sales and €0.8 basic earnings per share, helping lift trailing year earnings 20.3% and pushing net profit margin to 12.3%.
In the short term, the move in the share price reflects excitement. The bigger question for investors is whether a 31.7x P/E and a DCF value of €67.6 still leave enough room if this earnings power levels off.
Love Vaisala Oyj’s record profitability but unsure about paying a 31.7x P/E for it? Compare this setup with a curated screener of stocks that pair strong earnings power with sturdier looking valuations in our 195 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €162.9m vs. €154.0m (+5.8%)
- Net Income (Q3 2026 vs Q3 2025): €29.0m vs. €18.6m (+55.9%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.80 vs. €0.51 (+56.2%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 12.3% vs. 10.4% (improved)
Industrial Measurements just posted over 30% EBITA with record orders. Ask Charlie what makes Vaisala’s industrial margins so strong.
Vaisala’s Bull Story: Industrial And Digital Proof Points
Supporters argue Vaisala Oyj can turn industrial and software momentum into a sturdier earnings engine over time.
"A key factor is whether Vaisala can convert growth in Industrial Measurements, Xweather and lifecycle services into sustained high-margin, subscription and service revenue that can offset weaker renewable energy activity."
The latest quarter goes some way toward that goal. Industrial Measurements grew net sales 28% with a 31.7% EBITA margin and a 65.8% gross margin. Xweather delivered 9% sales growth and a 9.4% EBITA margin. Orders in both areas stayed healthy, and group ARR reached €60.9m, up 9%, indicating recurring revenue is gaining weight against weak renewables.
Bear Case: Project Cyclicality And FX Risks Under Review
Sceptics worry that project heavy end markets and currency swings could still undermine the mix shift story at Vaisala Oyj.
"Ongoing and potential future reductions in public sector spending, already visible in delayed or uneven ordering patterns for weather and environmental projects, could limit the flow of large contracts even as individual wins such as the €25 million Indonesian airport modernization move ahead."
The current set of numbers pushes back on that concern for now. Weather, Energy & Environment revenue declined 11% year on year, yet orders jumped and the order book climbed to €215m, helped by the €25m Indonesian airport project. FX pressure on EBITA eased versus last year, and Q3 margins benefited from tariff refunds, although that uplift is temporary.
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
Vaisala Oyj just reported a strong quarter while trading at what appears to be a full valuation. The real opportunity could be in stocks where earnings power and current pricing seem out of alignment.
- Company 1 - 40% below our estimate - uses long term civil and industrial construction projects to turn contracted backlog into earnings.
- Company 2 - 28% below our estimate - compounds secured lending in mortgages, gold and agriculture while lifting business handled per employee.
- Company 3 - 33% below our estimate - turns a growing residential project pipeline and industrial clusters into contracted presales and income from industrial park services.
Those are three of them. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com