


Yellowhead Pipeline groundbreaking puts Canadian Utilities in the spotlight
The Yellowhead Pipeline groundbreaking puts Canadian Utilities (TSX:CU) at the center of a $2.9b natural gas buildout in Alberta, with regulators, governments, Indigenous leaders and industrial customers already backing the project.
Canadian Utilities has seen momentum pick up recently, with a 7 day share price return of 3.35% and a year to date share price gain of 17.60%, while long term investors have experienced a 33.27% 1 year total shareholder return and very strong multi year gains. This suggests the Yellowhead Pipeline news is feeding into a broader reassessment of growth prospects and risk.
Scan for other infrastructure heavy utilities showing similar momentum and balance sheet strength by jumping into our hand picked 42 power grid technology and infrastructure stocks aligned with projects like Yellowhead.
Bulls point to Canadian Utilities’ Yellowhead-backed momentum and a wide headline discount, while bears focus on modest earnings and regulatory risk. Does the current valuation lean more toward opportunity, or is optimism already priced in?
Most Popular Narrative: 12% Undervalued
Canadian Utilities last closed at CA$50.32, while the most followed narrative anchors fair value at CA$57.00. This points to a valuation gap that investors are now weighing against Yellowhead Pipeline momentum and merger headlines.
Substantial investment in grid modernization and expansion, including major projects like the Central East Transfer Out and 90% contracted Yellowhead pipeline, positions Canadian Utilities to capitalize on rising power and gas demand from electrification and industrial growth, supporting future increases in rate base and long term revenue growth.
See why 43 investors see Canadian Utilities as 12% undervalued.
Result: Fair Value of CA$57.00 (UNDERVALUED)
Still, the narrative around Canadian Utilities can shift quickly if Alberta regulatory disputes drag on, or if heavy project funding pressures the balance sheet and future returns.
Find out about the key risks to this Canadian Utilities narrative.
Another View: Market Ratios Question the Discount
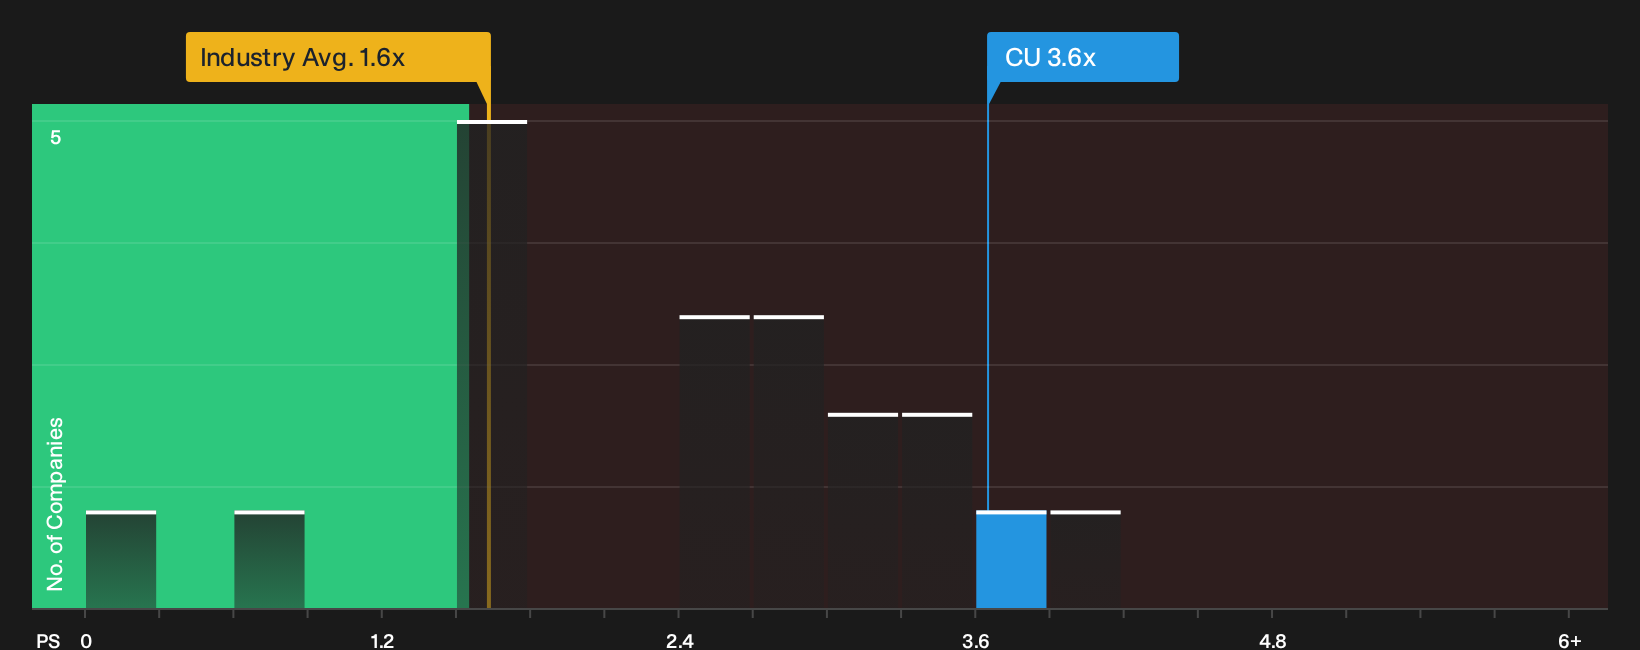
Canadian Utilities looks cheap on cash flow models, with our DCF work implying the shares trade about 64% below an estimated CA$139 future cash flow value. Yet the P/S ratio of 3.6x sits well above peers at 1.8x and a fair ratio of 2.7x, which points to richer expectations baked into today’s price. Which signal do you treat as more important?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Canadian Utilities so far. If you want to move quickly and base your view on the full picture, weigh up the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Canadian Utilities?
If Yellowhead has you thinking bigger about infrastructure and cash flow, do not stop with Canadian Utilities. The same toolkit can surface your next opportunity.
- Target value driven opportunities by scanning our hand picked 3 high quality undervalued stocks that match solid fundamentals with price tags that still look reasonable.
- Lock in potential income streams by filtering for 3 dividend fortresses that prioritize reliable payouts alongside financial resilience.
- Reduce unpleasant surprises by focusing on 8 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com