


Commercial Bancgroup came into this Q3 2026 report looking like a quiet value story. The stock traded on an 11x P/E, below both the broader US banks group and closest peers, and carried a discounted price against one prominent cash flow estimate. Yet the market’s first take was fairly muted, with the share price up just 2% on the day.
The real headline sits in profitability. Net interest margin printed at 4.14% for the quarter and earnings per share reached roughly $0.79, reinforcing a picture of a bank that is converting a relatively modest valuation into solid banking returns.
Like the look of Commercial Bancgroup’s 4.14% net interest margin but want a wider set of banks pairing healthy profitability with robust balance sheets? Compare CBK against our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
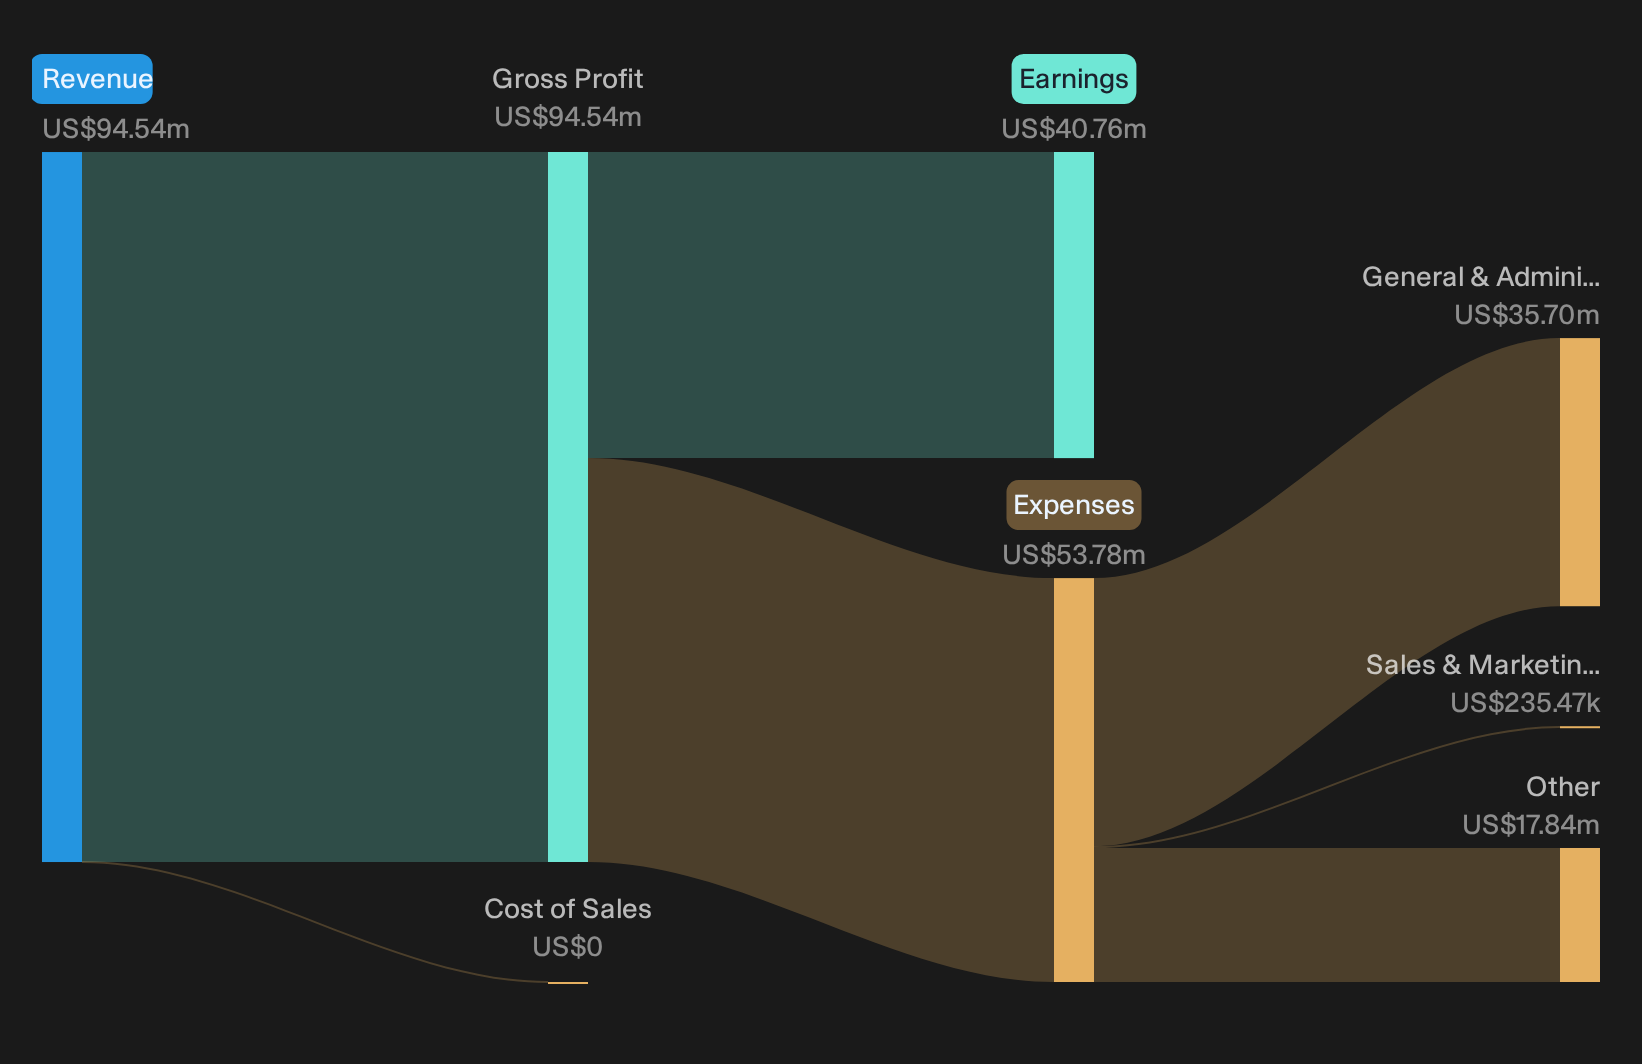
- Total Revenue (Q3 2026 vs Q3 2025): US$24.84m vs. US$22.85m (up 8.7%)
- Net Income, Excluding Extra Items (Q3 2026 vs Q3 2025): US$10.87m vs. US$9.47m (up 14.8%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.79 vs. US$0.77 (up 2.6%)
- Net Interest Margin (Q3 2026 vs Q3 2025): 4.14% vs. 4.00% (modest improvement in lending spread)
Earnings tell you how Q3 landed, but investors who care about valuation spend just as much time on the cash flowing through the business over time. Commercial Bancgroup’s recent results set the stage, yet cash generation is what ultimately anchors a price tag.
On the current cash flow profile, and using a discounted cash flow lens, the shares could hypothetically screen as a stock that could be a dramatic 40% undervalued.
Commercial Bancgroup’s Bull Story Faces a Reality Check
Optimists have argued that Commercial Bancgroup can turn fresh capital and a busy pipeline into stronger earnings power.
"Management highlights a full loan pipeline and expects strong fourth quarter 2025 closings, which, if converted, can lift interest income and support revenue as new loans replace prior payoffs from long-term borrowers selling their businesses."
The Q3 2026 print shows revenue of US$24.84m and net income of US$10.87m, with basic EPS at US$0.79 and net interest margin at 4.14%. Those figures indicate lending activity and pricing are supporting income today, yet they do not confirm that prior pipeline ambitions have translated into a step change in earnings power.
Bear Case: Margin Fragility And Growth Friction
Skeptics worry that Commercial Bancgroup’s strong spread is more fragile than it looks and that balance sheet choices could drag on earnings.
"Net interest margin is supported by a short duration balance sheet and higher cost time deposits, including CDs priced around 3.85% for 7 to 9 months."
Current net interest margin of 4.14% and an 8.7% revenue increase against Q3 2025 suggest funding costs and asset repricing are still working in the bank’s favor. Basic EPS is only modestly higher at 2.6% growth though, which hints that while margin compression has not yet bitten, the cushion against future funding pressure is not visibly widening either.
One Narrative disagrees with today's price. → See where this Narrative says Commercial Bancgroup should trade.
Hunt Quiet Mispricing Before It Closes
Commercial Bancgroup just reported a steady banking quarter that produced a limited share price reaction. The potential opportunity lies in studying stocks that might be mispriced before broader market attention adjusts expectations.
- Company 1 - 31% below our estimate - targets complex manufacturing programs in regulated sectors as an expanding opportunity pipeline converts awarded work into production revenue.
- Company 2 - 26% below our estimate - sells metabolic therapies that have reshaped obesity and diabetes management as high demand for key injectables continues to test capacity and supply planning.
- Company 3 - 23% below our estimate - expands robotic surgical platforms and smart care tools as hospitals increasingly standardize on its systems for procedures involving higher case complexity.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com