


Celestica walked into this Q3 2026 earnings release with the stock under pressure, down roughly 25% over the past month and 16% over the past quarter. The company then reported a strong quarter for an electronics manufacturer, booking US$5,829.7m of revenue and US$3.30 in basic earnings per share. That combination of a sliding share price and solid printed profit shifts attention to the longer term. For investors thinking in years rather than days, the key question now is whether this earnings power aligns with the multi-year growth and valuation case already being discussed around Celestica.
Impressed by Celestica’s earnings power but uneasy about the recent 25% share price slide? Take a look at our screener of resilient balance sheet plays that pair solid fundamentals with steadier trading action through the list of solid balance sheet and fundamentals stocks (7 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$5,829.7m vs. US$3,194.0m (higher year on year)
- Net Income Excl. Extra Items (Q3 2026 vs. Q3 2025): US$397.2m vs. US$267.8m (higher year on year)
- Basic EPS (Q3 2026 vs. Q3 2025): US$3.30 vs. US$2.33 (higher year on year)
- Net Income Excl. Extra Items, Trailing 12 Months (Q3 2026 vs. Q3 2025): US$1,245.8m vs. US$716.7m (higher on a trailing 12 month basis)
Tired of scrolling through dense tables and long lists of figures to understand Celestica’s story? View the complete visual snapshot of the business, including how analysts are framing the outlook, in our company report for Celestica.
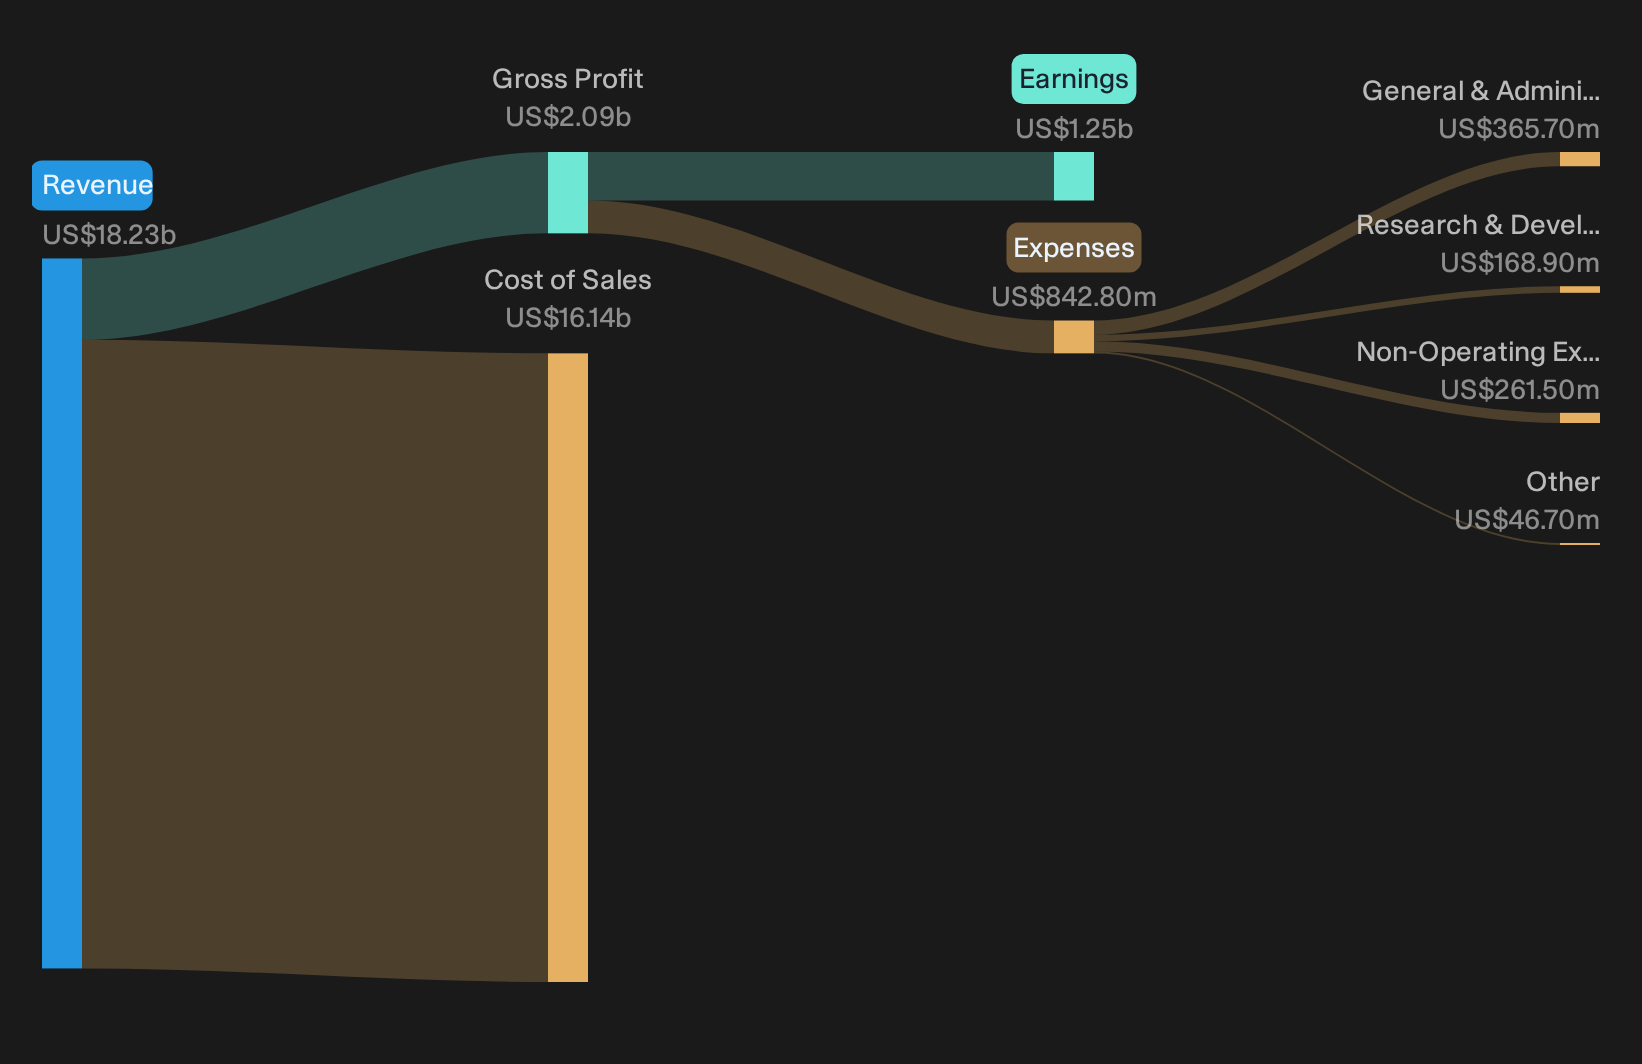
Celestica’s AI Ramp Story Meets Hard Numbers
The bullish script says Celestica is already turning AI hype into tangible hyperscaler programs and a richer mix.
"Accelerated demand for advanced networking and AI infrastructure by hyperscaler customers is now flowing through Celestica’s CCS outlook, with management guiding to approximately 85% CCS revenue growth in 2026 and expecting companywide revenue growth to accelerate further in 2027, which can support higher operating leverage and earnings."
Q3 revenue of US$5,829.7m and basic EPS of US$3.30, alongside raised 2026 guidance and talk of record operating margin in 2027, point to execution so far lining up with those ambitious ramp targets rather than lagging them.
Testing Celestica’s Concentration And CapEx Fears
The bear script argues that hyperscaler dependence and heavy spending could backfire if ramps slip.
"The large increase in capital intensity, with Q2 2026 CapEx at US$264 million or 5.6% of revenue and full year CapEx guided to about US$1b to support AI infrastructure programs, could prove excessive if customer ramps are delayed or resized. This would weigh on free cash flow and could limit future net margin improvement."
CapEx plans and an ongoing patent investigation remain real overhangs, and recent share price declines underline that concern. Yet Q3 profit metrics and higher 2026 and 2027 guidance do not yet show margin strain or ramp disappointment flowing through the income statement.
One Narrative disagrees with today's price. → See where this Narrative says Celestica should trade.
Hunt Quiet Dislocations Before They Close
Celestica shows how earnings strength and share price direction can move out of sync. The real opportunity could be spotting stocks where fundamentals and valuation have not yet reconnected.
- Company 1 - 37% below our estimate - designs critical transport, water and energy infrastructure upgrades as government projects move from planning to contracted execution cycles.
- Company 2 - 42% below our estimate - runs integrated freight and industrial services contracts that deepen as customers shift shipping, storage and field work to single-provider agreements.
- Company 3 - 47% below our estimate - refreshes fashion assortments based on online sell through data that alters design and inventory decisions in near real time.
Those are three of them. See every one of the 3 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com