


Armstrong World Industries stock took a hit today, sliding about 6% to around US$155 after its Q3 2026 earnings landed. The move jars with the headline story. The company just posted record third quarter sales of US$475.8m and net income of US$91.9m, alongside a trailing net profit margin of 18.4%.
Short term traders focused on the price drop. Long term holders are more likely weighing a business that continues to generate profits, sits on a P/E of 20.5x and is trading below one discounted cash flow value estimate.
If you appreciate Armstrong World Industries’ margins and earnings power but want more options at a similar quality level, consider exploring a curated list of resilient stocks with strong profitability and balance sheets in the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$475.8m vs. US$425.2m (up about 11.9%)
- Net Income (Excl. Extra Items) (Q3 2026 vs. Q3 2025): US$91.9m vs. US$86.3m (up about 6.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.17 vs. US$2.00 (up about 8.8%)
- Net Profit Margin (Trailing vs. Prior Year): 18.4% vs. 19.1% (margins contracted slightly)
Data center demand beat Armstrong’s own expectations this quarter. Ask Charlie what Armstrong’s data center push really means for growth.
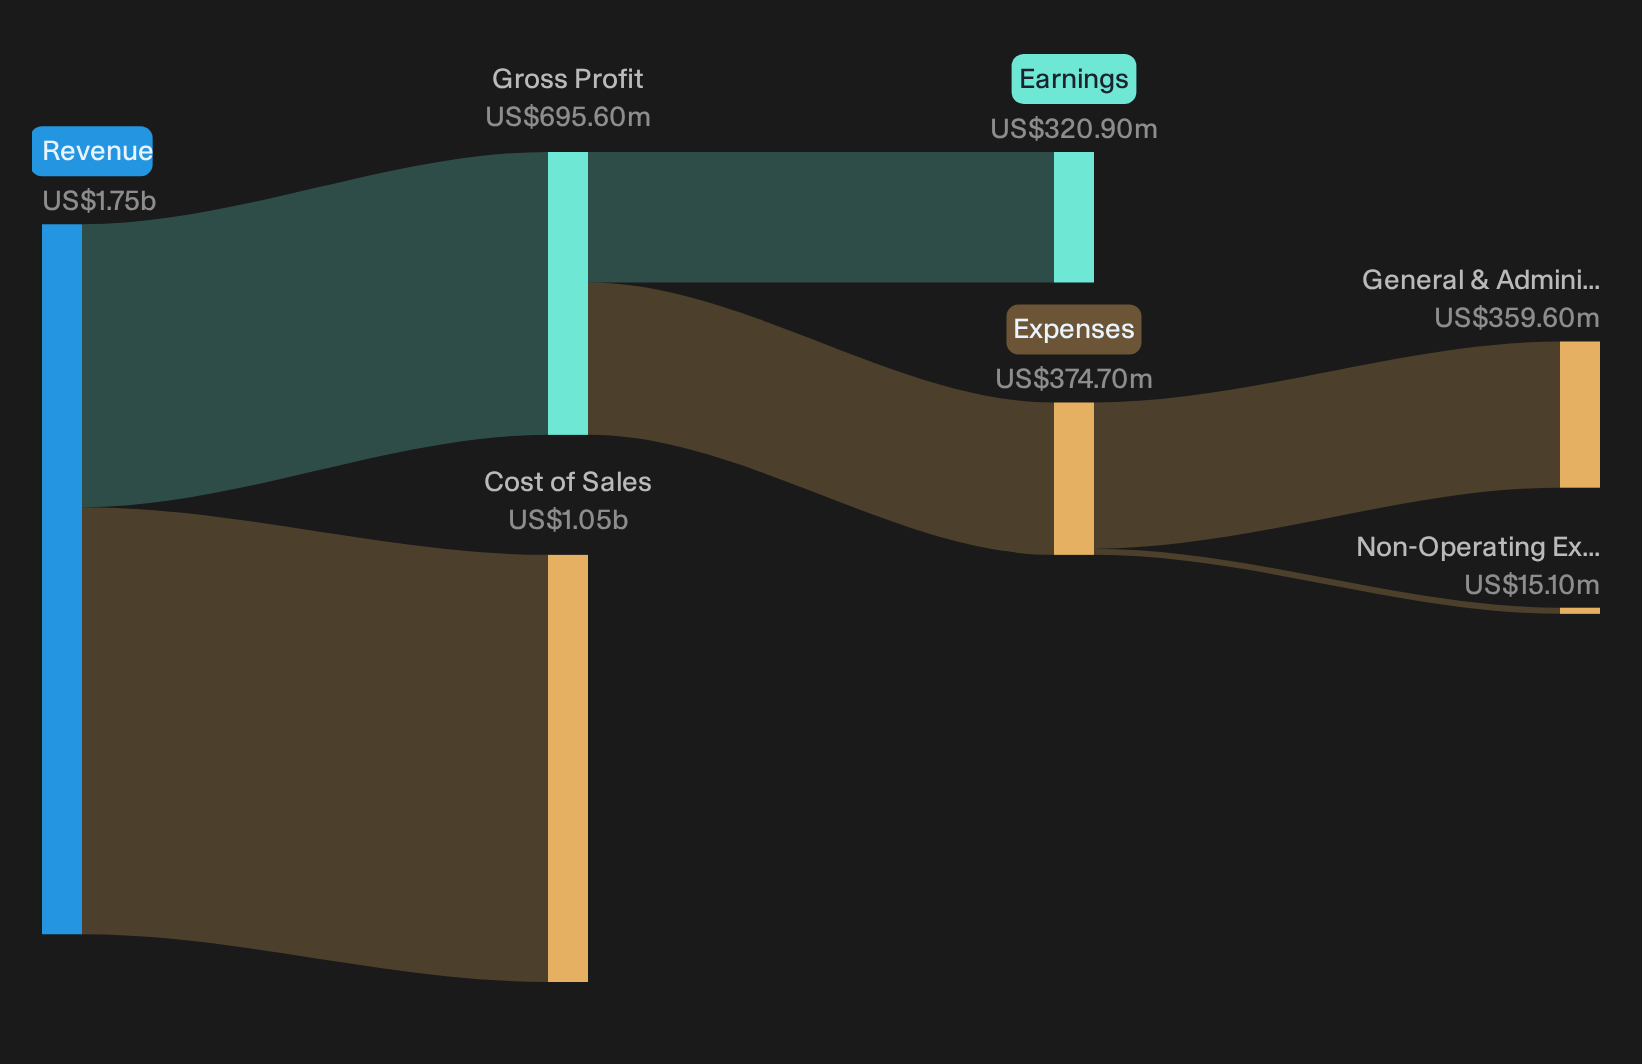
Armstrong World Industries: Testing The Upside Story
The bullish story says Armstrong World Industries can turn platforms and energy efficient solutions into structurally richer earnings, not just higher sales.
"Consistent pricing and mix led AUV gains in Mineral Fiber, including 6% AUV growth in Q2 2026 and company expectations for about 6% AUV growth for full year 2026, together with contribution from PROJECTWORKS, Kanopi, TEMPLOK and data center solutions that are expected to add up to 1.5 percentage points of volume growth above market, support the case for continued net sales growth and adjusted EBITDA margin expansion."
Q3 data broadly lines up with that ambition. Mineral Fiber AUV rose 6%, volumes were positive for the third quarter in a row, and segment EBITDA margin edged higher to 44% despite mix headwinds and higher input costs. Architectural Specialties also widened margins alongside strong organic growth, which supports the idea of richer project scope feeding profitability, even as tariffs and inflation trimmed the full year EBITDA growth range.
Armstrong World Industries: Stress Testing The Risks
The bear story worries that end market softness and project hiccups in Architectural Specialties could undercut that higher margin plan.
"The securities fraud investigations that followed softer than expected sales volumes and delays on five major Architectural Specialties projects highlight ongoing execution and disclosure risk. Any further volume shortfalls or project delays could weigh on investor confidence and affect the valuation multiple applied to earnings."
Recent numbers show execution in this segment moving in the opposite direction of that fear. Architectural Specialties net sales rose 22%, with organic growth of 16%, and adjusted EBITDA advanced 25% with margin at 19.4% and organic margin above 20%. Order intake stayed in double digits and transportation related wins were strong. There is some integration friction around Parallel and slightly lower inorganic contribution, yet the broader portfolio is delivering higher project throughput rather than visible shortfalls in this quarter.
The price and this Narrative do not agree. → Uncover what this Narrative says Armstrong World Industries is actually worth.
Hunt Quiet Mispriced Earnings Power
Armstrong World Industries recently reported, and its strong quarter contrasted with a sliding share price. The real opportunity is researching stocks that could be undervalued before the market recognizes their earnings power.
- Company 1 - 34% below our estimate - turns heavy investment in high horsepower engine capacity and data center power contracts into a broader, more specialized power platform.
- Company 2 - 46% below our estimate - converts a record, technology-focused backlog into long duration data center and modular construction projects that keep fabrication facilities fully utilized.
- Company 3 - 23% below our estimate - ties cloud infrastructure, workplace software and AI tools into a single ecosystem enterprises adopt as they scale real AI workloads.
Those are three of them. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com