


Money is pouring into AI infrastructure, and the Broadcom and Anthropic financing deal shows how huge that funding wave has become, with banks and private capital lining up behind it. Investors now face a clear question about who potentially benefits most from this kind of equipment and chip financing, and who quietly shoulders the risk. This article walks through three U.S. Specialty Equipment Finance and Leasing stocks exposed to that theme and explains how the same news can signal both opportunity and caution for your portfolio.
The three stocks below are just a sample to frame the theme. The full screen surfaced 10 more equipment finance and leasing companies with equally detailed stories around AI infrastructure exposure that are not covered here. If you want to identify and analyze potential higher conviction ideas in this space, head straight into the Specialty Equipment Finance & Leasing for AI Infrastructure screener.
Capital Southwest (CSWC)
Capital Southwest plugs into the AI equipment finance theme as a lender that can underwrite secured loans and leasing-style structures for mid-sized businesses buying data center or chip gear. This makes its approach to risk and income generation especially important for this screen.
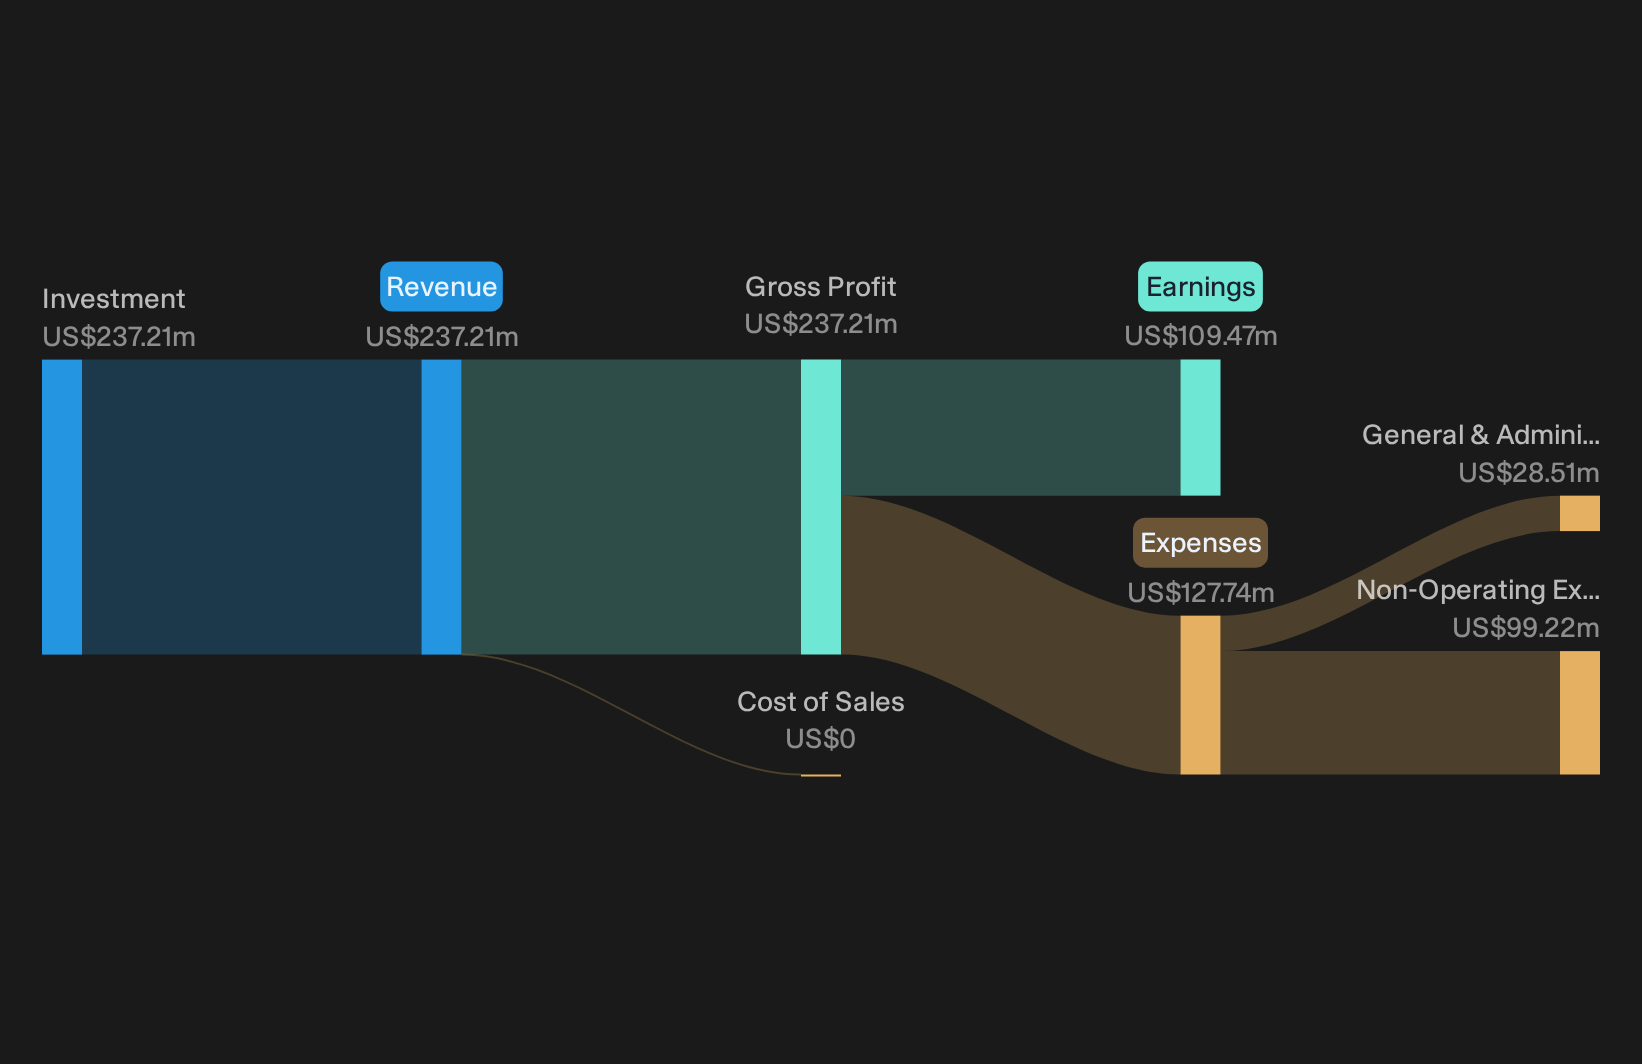
Capital Southwest is a US business development company that earns about US$237 million from investment income and lends to lower middle market borrowers across sectors, with flexibility to fund data center and semiconductor equipment while carrying a market value of roughly US$1.43b.
"Conservative first lien senior secured underwriting, with about 99% of the credit portfolio in first lien positions, average borrower exposure of roughly 0.8% to 0.9% and nonaccruals around 1% to 1.5% of fair value, supports a portfolio approach focused on preserving credit quality and net margins."
The real swing factor is how a single funding and payout trade off ultimately shapes what portion of that careful credit work reaches your returns.
That trade off is exactly what the full narrative for Capital Southwest unpacks, showing where income stability could be masking concentration risks or future upside optionality.
Hewlett Packard Enterprise (HPE)
Hewlett Packard Enterprise leans into the AI infrastructure theme by selling servers, networking gear, and as a service offerings that can be paired with leasing style and vendor financing models for large data center and inferencing projects.
HPE generates about US$11.3b from Networking and US$29.8b from segment adjustments and other operations, reflecting a broad IT infrastructure mix, and carries a market value near US$77.9b.
For investors tracking how AI chip financing spills into data centers and networks, Hewlett Packard Enterprise sits at the intersection of hardware, recurring contracts, and financing structures.
"The rapid adoption of AI and machine learning across industries is driving a significant increase in demand for high performance compute and networking infrastructure."
A key consideration now is how one major swing factor affects the balance between richer AI margins and the cost of funding that gear.
That trade off is exactly what the full narrative for Hewlett Packard Enterprise breaks down, showing how AI demand, financing terms and hardware economics could be accelerating or quietly capping Hewlett Packard Enterprise’s upside.

Corvex (MOVE)
Corvex runs GPU based AI cloud infrastructure that directly depends on securing and financing large volumes of chips and data center hardware. The business reports about US$9.8 million of revenue from the United States and has a market value around US$239 million.
Corvex provides exposure to AI infrastructure capacity, where GPU clusters and power hungry data centers are funded through a mix of debt, equity and customer prepayments. For a capital intensive model built on fixed term AI contracts, changes in funding costs could have a significant impact on future returns.
Those funding swings make it worth checking the analysis report for Corvex before Corvex’s financing costs and contract structure start materially reshaping the AI capacity story.

Seeking Fresh Alternatives Before They Fly?
New themes can break out fast, and the strongest momentum often appears before headlines catch up. Scan fresh ideas while it matters, under the radar for now, and consider positioning early.
- Focus on durable cash generators and monitor balance sheet strength using the curated list of solid balance sheet and fundamentals (24 results) before the crowd starts following the same stories.
- Explore the next potential uptrend in automation and factory intelligence with a focused group of 94 robotics and automation stocks that could benefit as demand for productivity tools builds.
- Review a targeted cohort of 35 elite gold producer stocks to stay prepared for potential shifts in monetary policy that might influence risk appetite or inflation expectations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com