


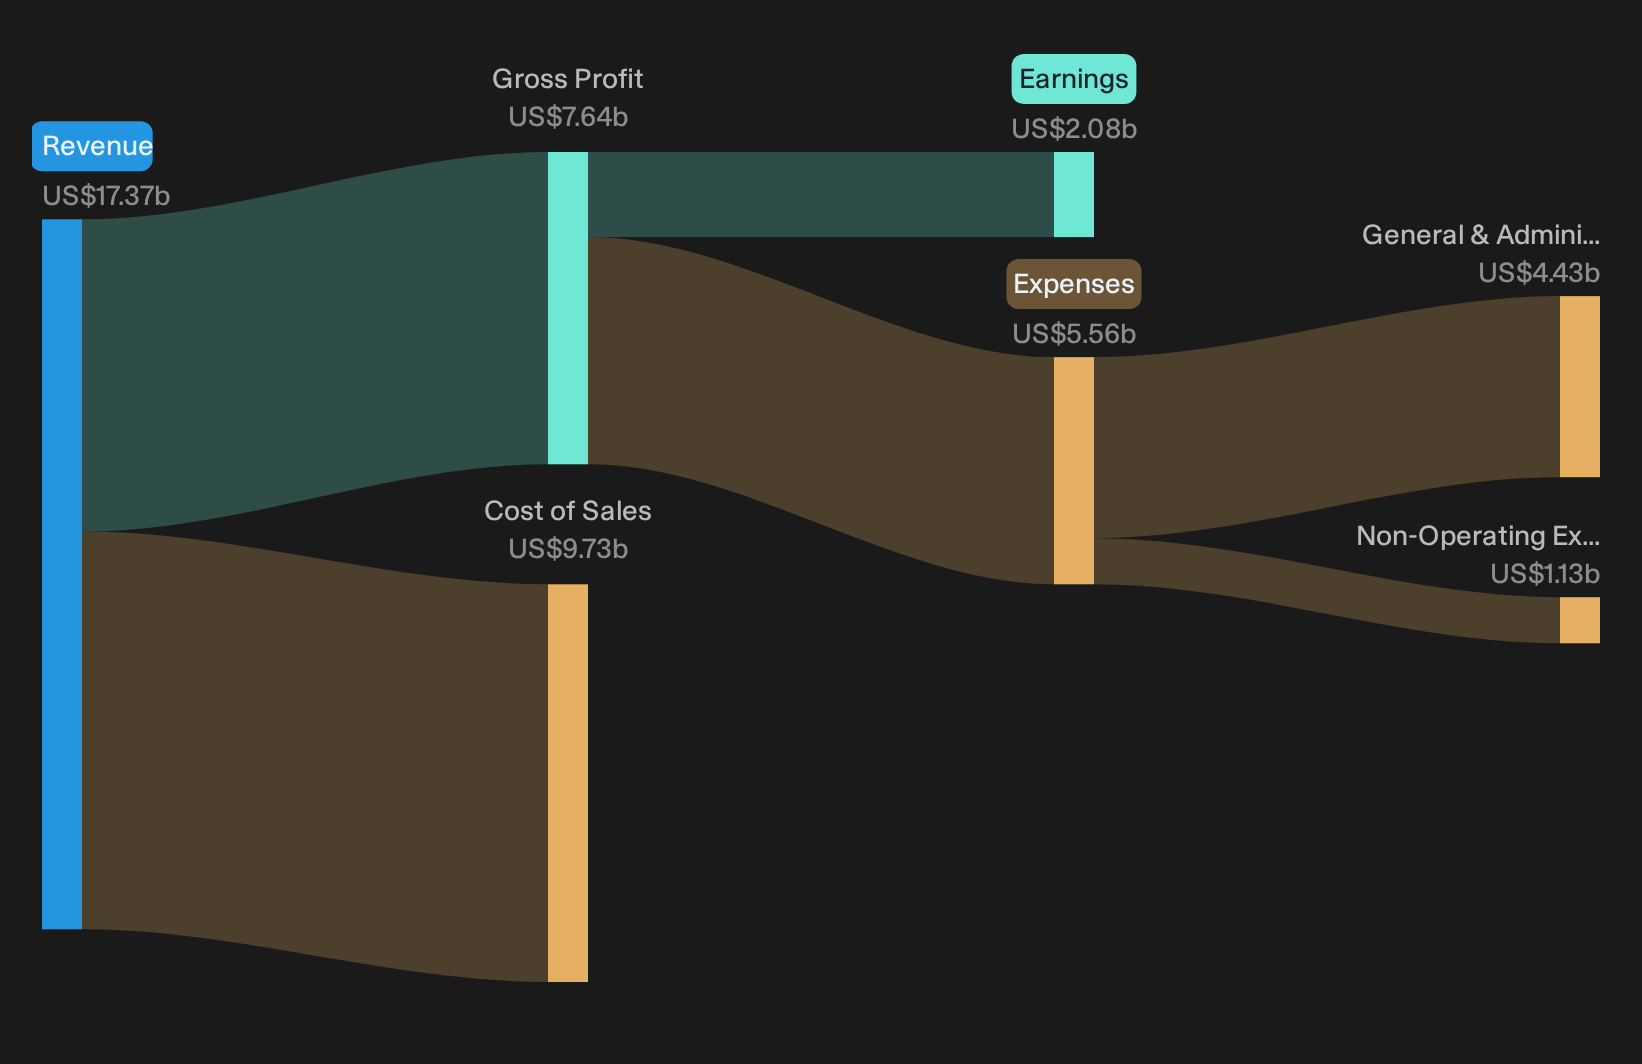
Ecolab entered its Q3 2026 earnings release priced for perfection, trading at a rich P/E multiple and sitting near recent highs after a steady run, yet the stock barely flinched, rising about 0.8% on the day. The headline was clear: Revenue reached about US$4.7b and basic earnings per share came in near US$1.97, with operating margin progress at the center of the story.
That muted share price move underplays the single biggest takeaway for investors. Margin traction across Ecolab’s water and hygiene platform, not just sales growth, is what now needs the closest attention.
Love Ecolab’s margin focus but want more options with strong profitability and balance sheet support? Scan the list of solid balance sheet and fundamentals stocks (24 results) to see a curated set of stocks built around that profile.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$4,694.8m vs. US$4,165.0m (up about 12.7%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$551.3m vs. US$585.0m (down about 5.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.97 vs. US$2.06 (down about 4.7%)
- Organic Operating Income Margin (Q3 2026): 19.6% (management highlighted this as a key profitability focus for Ecolab in the quarter)
Ask Charlie what Ecolab’s data center boom means for earnings.
Ecolab growth engines: pricing power put to work
The bullish story argues that Ecolab’s growth engines and pricing model do more than just hold the line on costs. They are supposed to reshape the mix and lift profitability.
"Growth engines such as Global High Tech, Life Sciences, Digital and Pest, which now contribute roughly a quarter of sales and include Global High Tech targets for more than 25% annual growth to US$4b of sales and 25% operating margin by 2030, are expected to drive faster organic revenue growth and support the company’s goal of at least 20% operating margin and higher ROIC."
Q3 marks a concrete step toward that ambition. Organic operating income margin reached 19.6%, while Global High Tech grew 63%, Life Sciences rose 17%, Digital advanced 34%, and Pest added 8%. Those gains helped organic operating income grow 11%, even as net income and EPS softened year on year, which shows mix shift working but not yet flowing cleanly to the bottom line.
Ecolab execution risks: high capex and M&A drag
The bear case centers on whether Ecolab can keep this machine running while spending heavily and folding in new deals without tripping over its own ambition.
"Elevated capital expenditure at around 7% of sales for several years, combined with the CoolIT acquisition reducing adjusted EPS by about 0.20 US dollars per quarter in the second half of 2026, could limit near term free cash flow and delay the expected improvement in earnings and returns on invested capital."
Recent numbers partially validate that concern. Management highlights that pro forma EPS, including CoolIT and Ovivo, would have grown mid teens, yet reported net income excluding extra items declined 5.8% and basic EPS fell 4.7%. Organic margins improved, but higher interest and amortization tied to acquisitions are clearly weighing on near term earnings power.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
Ecolab showed how a detailed margin story can matter as much as the headline EPS print. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 46% below our estimate - convert a record project backlog tied to AI heavy data centers into higher value modular mechanical builds.
- Company 2 - 42% below our estimate - scale newer storage and inverter offerings so tracker customers deepen commitments despite project delays.
- Company 3 - 23% below our estimate - supply liquid cooling and power systems that make high density AI racks viable without traditional cooling towers.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com