


Dropbox has put up a solid share-price run in recent years, and that raises a simple question for anyone looking at the stock today. Is the current valuation still grounded in the earnings power of the business, or has the price moved ahead of what the income statement can support?
- Over the past 3 years the stock has returned 40.4%. That puts real weight on whether the underlying earnings justify where the share price now sits.
- Recent positive coverage around Dropbox points to optimism about the company’s ability to translate its subscription base and cost structure into durable profit. This, in turn, can shape how comfortably investors view today’s earnings multiple.
- There is a second opinion on Dropbox worth weighing. See what analysts think Dropbox's shares could be worth.
The issue now is whether Dropbox's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing Dropbox through the lens of its earnings multiple, it can help to compare it with other businesses screened on clear fundamentals such as solid balance sheet and fundamentals stocks screener (24 results).
Does Dropbox Look Undervalued on Earnings?
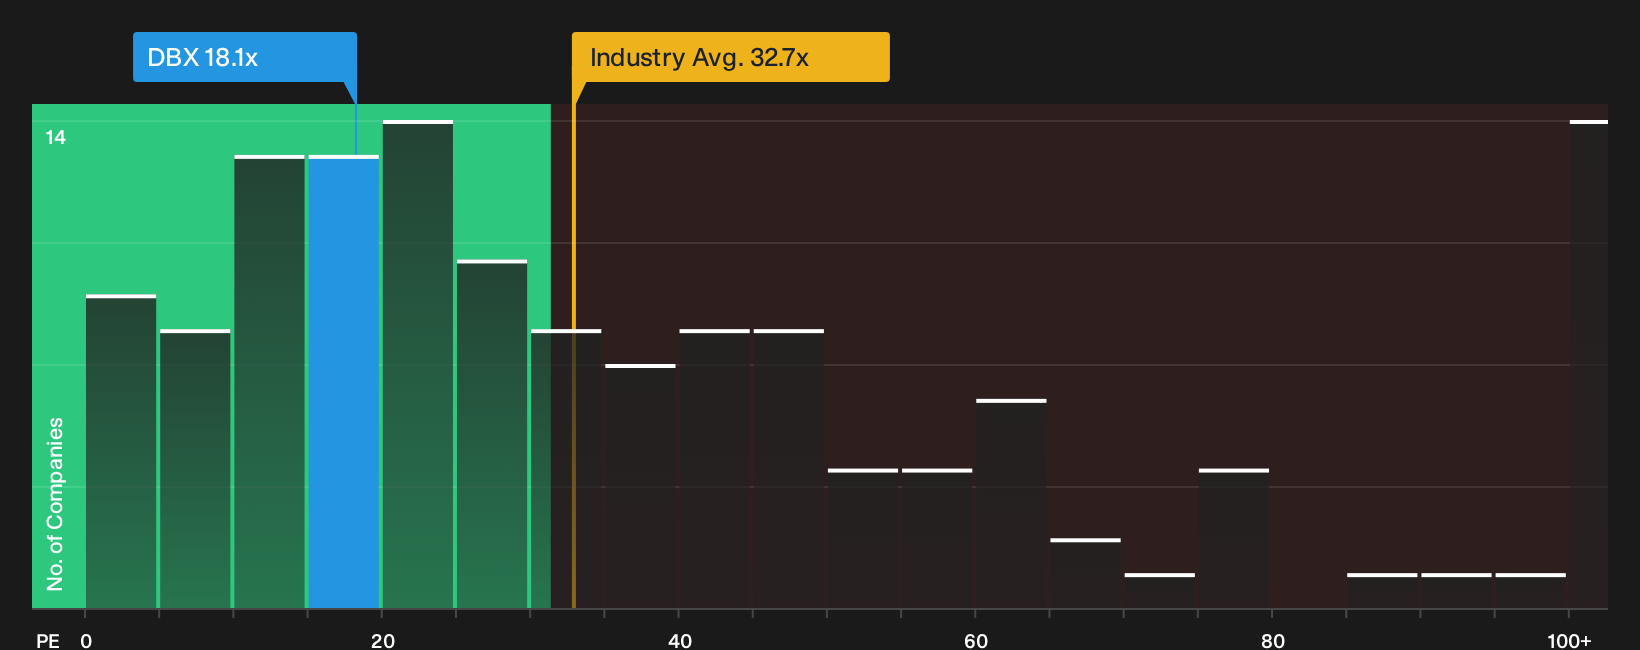
A P/E ratio works well for Dropbox because the business reports positive earnings and investors can relate its share price directly to those profits. Dropbox currently trades on a P/E of 18.1x, which sits below the software industry average of 32.7x and also below the peer group on 26.8x.
The Fair Ratio, which reflects what you might expect for a company with Dropbox's sector, profitability profile, size and risk, suggests the current 18.1x multiple is below that tailored benchmark and points to the stock screening as undervalued on this measure. Despite recent upbeat technical signals and short term price strength, the earnings multiple still prices Dropbox at a discount to both its sector and closer peers, so you would need to decide whether its profit quality and growth prospects justify that gap. Explore the numbers behind Dropbox's P/E valuation.
The Dropbox Narrative: What Would Justify Today's Price?
Narratives on Dropbox pick up where the P/E puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to unfold for the shares to look meaningfully stronger or weaker than today. Each scenario links a specific set of catalysts and risks to an estimated value range, so you can track over time which storyline about Dropbox's business is actually taking shape on the Community page.
Community views on Dropbox split between those who see hidden upside in its AI efforts and those who think the cash flow story is already fully recognised.
Bull case: 12% undervalued
"Three consecutive quarters of net new paying user growth to 18.19 million and sequential ARR expansion, following earlier expectations for a decline, indicate that improved onboarding, activation and retention tooling can compound over time into a larger monetizable base..."
Discover why this Narrative puts Dropbox at 12% undervalued.
Bear case: 16% overvalued
"Recent research argues that Dropbox shares already reflect a high level of confidence in the success of the AI pivot at a time when the core file sync and share business is only growing modestly and near term revenue expectations are flat..."
Explore why this Narrative puts Dropbox at 16% overvalued.
Dropbox's price still leaves one crucial question open
What really shapes how Dropbox is run, and how decisions trade off short term gains against long term resilience, is who sits in charge and the way their pay packets are structured. See who runs Dropbox and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com