


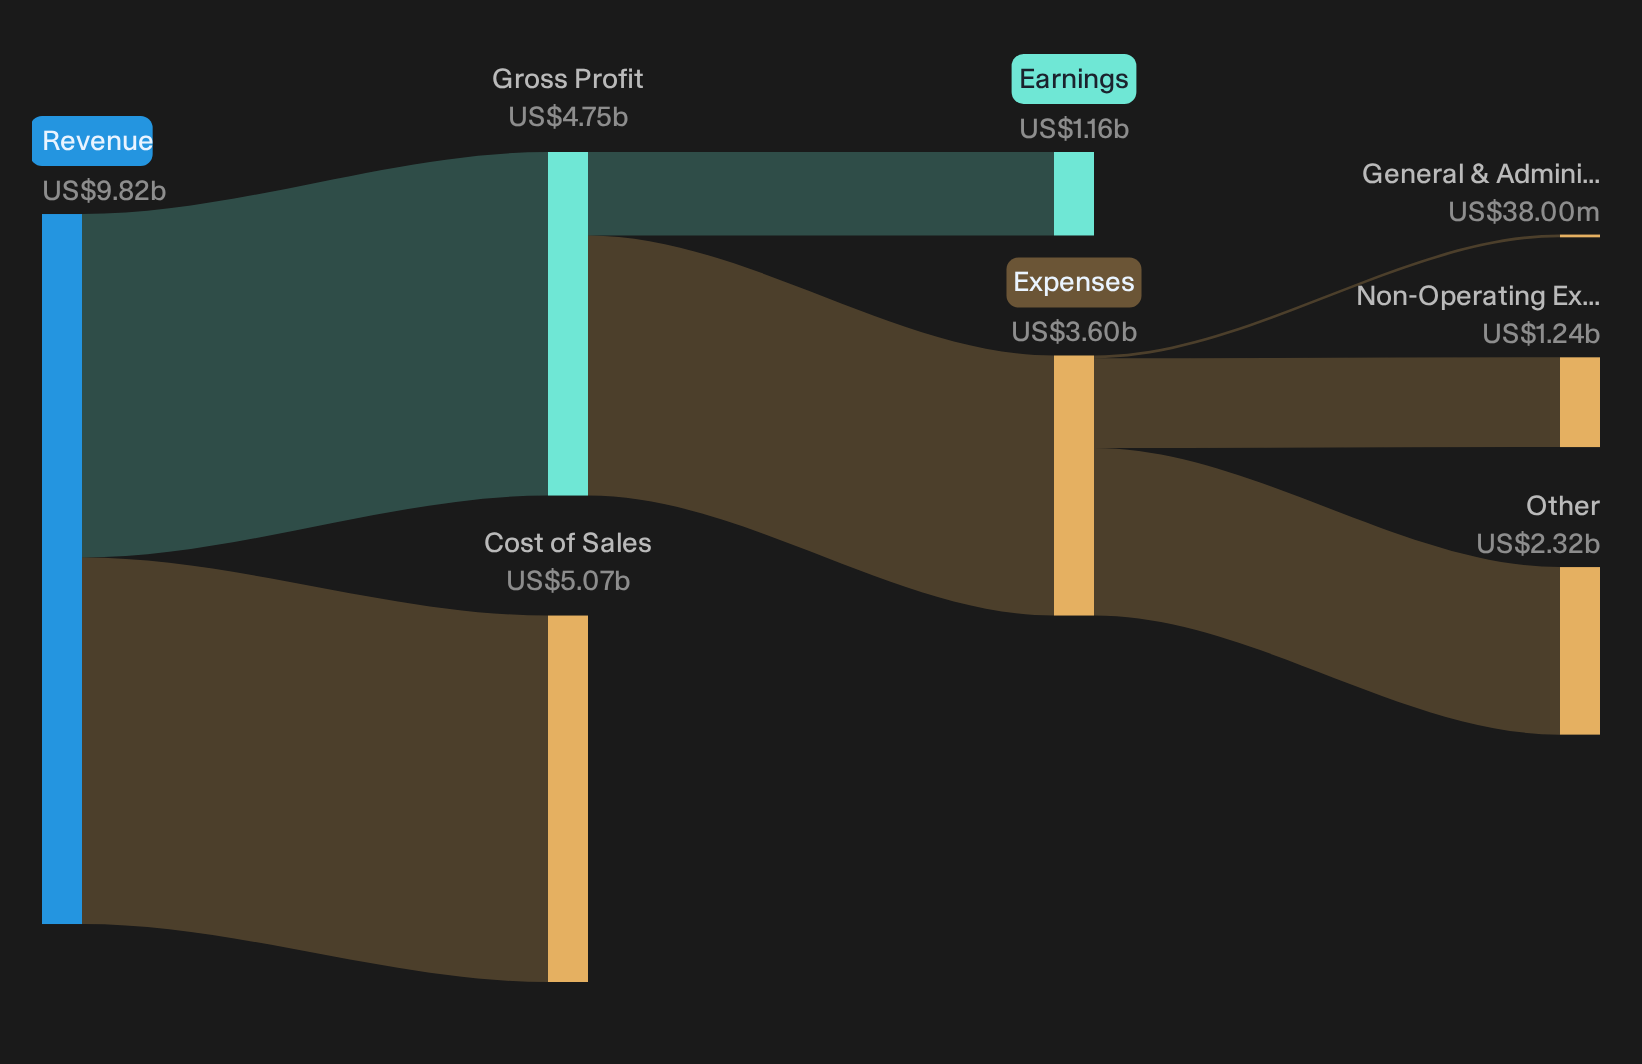
CenterPoint Energy just posted Q3 2026 results and the stock barely flinched higher, up 1.9% to US$41.97, even as the headline numbers pointed to a stronger earnings engine. Basic earnings per share came in at about US$0.50 and non GAAP earnings per share reached US$0.53, with trailing 12 month earnings of roughly US$1.76 per share helping to frame a richer P/E multiple.
That muted price reaction looks more like investors squinting at valuation than responding to the quarter itself. The results leaned toward earnings strength rather than any obvious crack in the story.
We see potential in the earnings power at CenterPoint Energy, but we are cautious about paying a higher P/E multiple when the stock’s move is this small. Benchmark your watchlist against our screener of 29 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,191 million vs. US$1,988 million (up about 10.2%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$331 million vs. US$293 million (up about 13.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.50 vs. US$0.45 (up about 11.6%)
- Trailing 12 Month Basic EPS (Q3 2026 vs. Q3 2025): US$1.76 vs. US$1.59 (up about 10.9%)
Earnings are one thing, but investors who care about what they are paying for CenterPoint Energy tend to watch the cash that actually comes through the business. When you look at CenterPoint Energy's cash flows alone, the stock could be a striking 42% overvalued.
CenterPoint Energy growth thesis meets key execution marks
The bullish story rests on CenterPoint Energy turning a huge capital plan and large load wins into durable earnings power.
"CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035, which ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion and therefore to future revenue and earnings."
Q3 non GAAP EPS of US$0.53, a guidance lift to a range of US$1.90 to US$1.92 for 2026, and new 2027 guidance of US$2.07 to US$2.09 all line up with that ambition. The capital blueprint is now US$70.7b, with US$4.1b already deployed year to date and US$1.5b pulled forward, which shows the plan is moving out of the slide deck and into the ground.
Bear case focuses on funding strain and growth concentration
The bear side worries that the same growth engine could overreach on funding and exposure to a few big projects.
"Earlier concerns about higher interest expenses tied to net new debt are now paired with an at the market equity program of up to US$1b that runs through 2029. If this flexible funding mix results in higher than expected financing or dilution costs, it could weigh on net margins and earnings growth."
Q3 already shows higher financing costs as a headwind and management now plans about US$4b of equity issuance from 2027 to 2030, with total 10 year equity needs up to US$4.5b. That is a real cost of the expanded US$70.7b plan and leaves investors watching whether O&M cuts, Ohio sale proceeds and capital trackers are enough to offset funding drag on future earnings.
One Narrative disagrees with today's price. → See where this Narrative says CenterPoint Energy should trade.
Hunt For Mispriced Earnings Power
CenterPoint Energy just showed how a busy quarter can leave the share price nearly unchanged. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 15% below our estimate - leverages data center construction demand as backlog, segment trends and cash generation reshape its balance sheet and revenue mix.
- Company 2 - 38% below our estimate - uses policy supported device trade ins and growing refurbishment capacity to pursue higher quality supply and steadier recommerce margins.
- Company 3 - 42% below our estimate - develops solar tracking and software projects while promoting newer storage and inverter offerings to deepen its installed base and margin mix.
Three companies from the same screener. Open all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com