


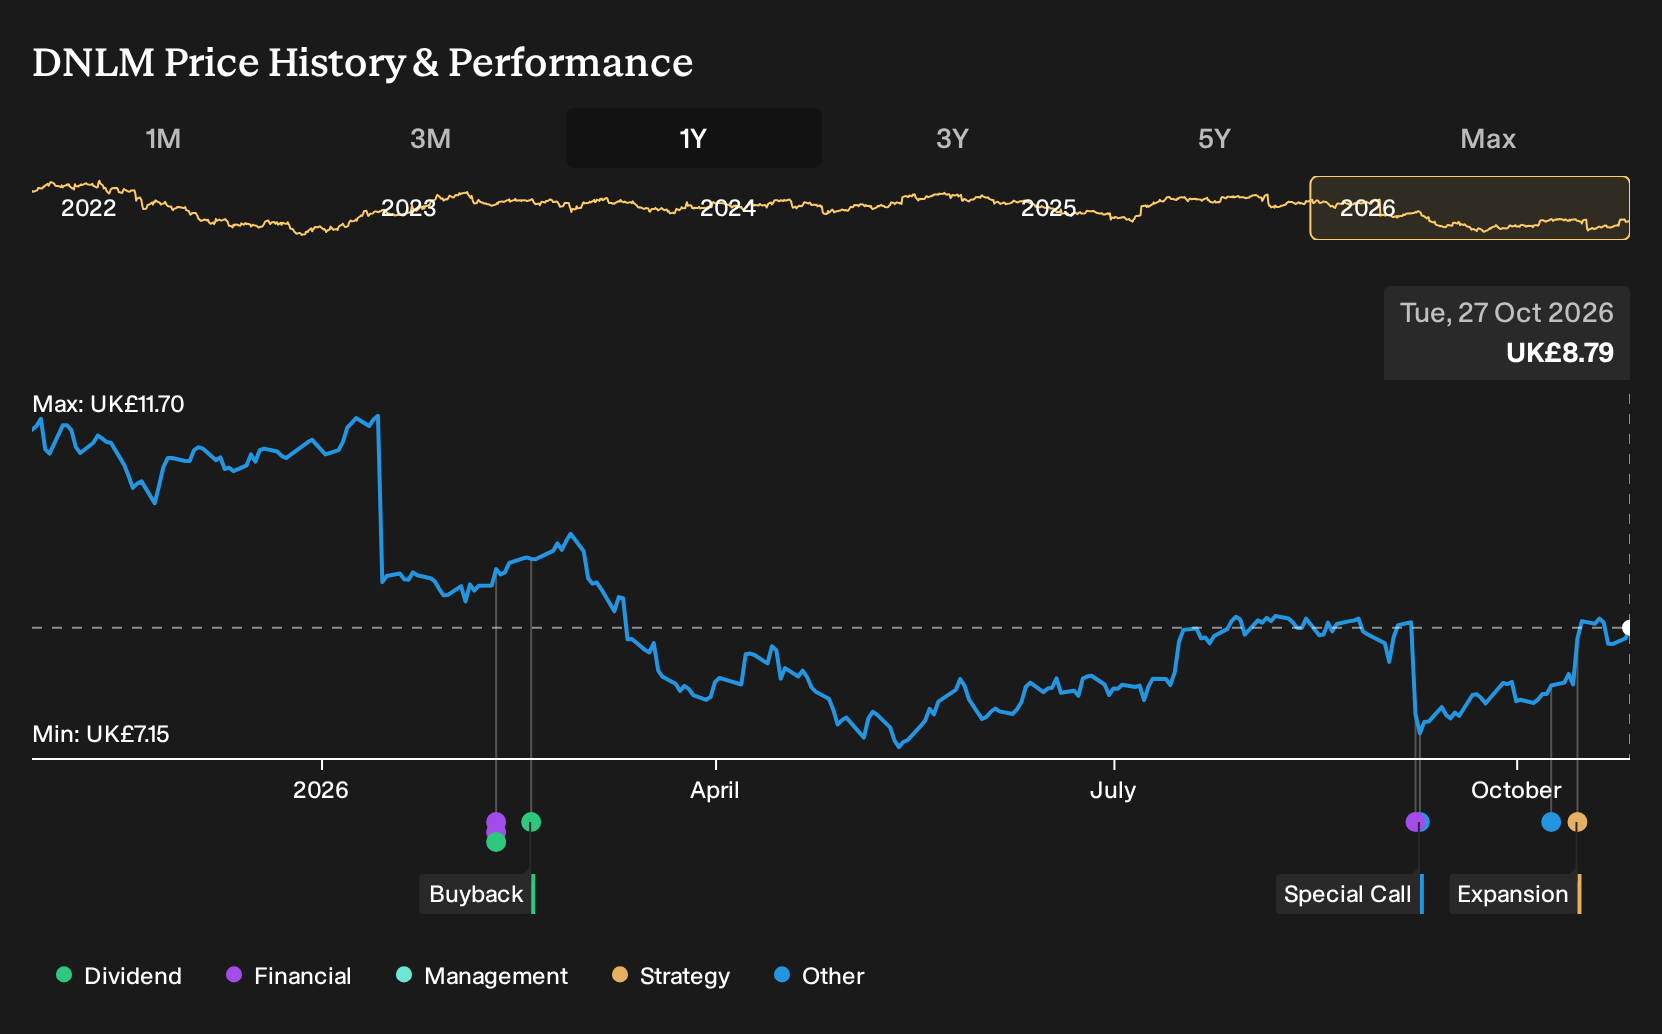
- Dunelm Group reported sales of £433 million for the 13 weeks to 26 September 2026, up 1.1%, with stronger trading later in the quarter after an early slowdown linked to hot weather.
- Refitted and renewed stores, including learnings applied from St. Albans to a larger Doncaster revamp, are already showing encouraging sales uplifts, highlighting how physical estate quality is influencing Dunelm Group's trading pattern.
- We will now look at how Dunelm Group's modest sales growth, helped by refits and renewals, might reshape its investment narrative.
Compare Dunelm Group's measured sales momentum and store refits with other retailers that pair modest growth with solid fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (10 results)
Dunelm Group Investment Narrative Recap
Dunelm Group appeals to investors who believe its mix of omnichannel homewares, disciplined merchandising and cost focus can turn modest sales trends into steady profit compounding. The latest 1.1% quarterly sales uplift to £433 million feels incremental rather than transformational, so it does not radically change that thesis.
The key near term swing factor is whether consumer demand and in store execution can lift growth back toward the company’s medium term ambitions. The biggest risk remains cost and wage pressure outpacing those modest sales gains, which would squeeze already tight margins if productivity and cost removal plans underperform.
The most relevant update for that debate is the store renewal and expansion program. Five refurbishments are now complete and management describes early sales uplifts as encouraging, while a larger Doncaster refit will apply learnings from the St. Albans project that is already seeing strong trading.
For shareholders, the question is whether these refreshed and new locations meaningfully support Dunelm Group's cost removal and revenue targets or simply offset the drag from older stores. Execution risk is material. If renewals, refits and two planned openings in the first half fail to sustain better trading, the growth and margin case becomes more difficult to justify.
Dunelm Group's narrative projects £2.1b revenue and £172.5 million earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about £17 million from £155.5 million today.
Discover why Dunelm Group's fair value signals a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view on Dunelm Group leans heavily on the store and digital expansion catalyst. The most optimistic analysts were assuming revenue of about £2.1b and earnings near £170.8 million by 2029. They saw the multichannel push as justification for a higher 19.2x P/E. After this trading update, those expectations may shift, in either direction, as you compare different narratives.
Explore 4 other Dunelm Group fair value estimates, including one that suggests as much as 76% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dunelm Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dunelm Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dunelm Group's overall financial health at a glance.
Looking for more Dunelm Group sized ideas?
If the Dunelm Group story has sharpened your thinking, use that same lens on a wider field of opportunities with the Simply Wall St Screener.
- For investors hunting for value with quality, scan a curated set of 10 high quality undervalued stocks that combine strong fundamentals with room for sentiment to catch up.
- If resilience matters most to you, focus on businesses with healthier finances by filtering through a list of solid balance sheet and fundamentals (10 results) that aims to limit balance sheet surprises.
- When income is a priority, narrow your research to potential yield opportunities by zeroing in on a shortlist of 5 dividend fortresses that meet a 5%+ threshold.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com