


Liberty Energy (LBRT) just delivered a mixed update. Third quarter revenue reached US$1,196.16 million, and results shifted from a profit to a net loss alongside a fresh dividend declaration.
Liberty Energy’s latest earnings and dividend news landed alongside a sharp rebound in trading, with the share price up 5.41% on the day to US$16.94 and a 7 day share price return of 2.17% after a 30 day decline of 10.56%.
Recent moves suggest sentiment has firmed in the very short term, even though the year to date share price return is still down 10.28%. The 1 year total shareholder return of 0.88% and 5 year total shareholder return of 42.55% point to a mixed but still positive longer record for investors who stayed in the stock.
Scan other energy players showing a mix of earnings pressure and income strength by reviewing the hand-picked 5 dividend fortresses alongside Liberty Energy’s latest results.
Liberty Energy now trades below its recent highs after a quarter that paired higher sales with a net loss and a fresh dividend. Is most of the upside already used up, or could valuation still leave room ahead?
Most Popular Narrative: 37% Undervalued
The most followed narrative currently places Liberty Energy’s fair value at $27.00, well above the last close at $16.94. This frames the recent pullback and mixed quarter as only part of a bigger, long term story around completions and power.
The main thing that has to go right is Liberty Energy successfully executing its capital intensive pivot toward a 3 GW distributed power platform while keeping its frac fleets tightly utilized and cost efficient through digiTechnologies and AI driven tools.
The current valuation implies the market is discounting Liberty Energy’s plan to deploy roughly 3 GW of on site power with targeted 5 to 6 year cash on cash paybacks and double digit unlevered returns, while also questioning how much of the tight frac and energy security backdrop will translate into durable cash generation for shareholders.
See why 9 investors see Liberty Energy as 37% undervalued.
Result: Fair Value of $27.00 (UNDERVALUED)
Still, rising capex needs around the 3 GW power build and a power unit that is not expected to add meaningful earnings until 2028 could challenge this Liberty Energy narrative.
Find out about the key risks to this Liberty Energy narrative.
Another View: Liberty Energy Through The P/E Lens
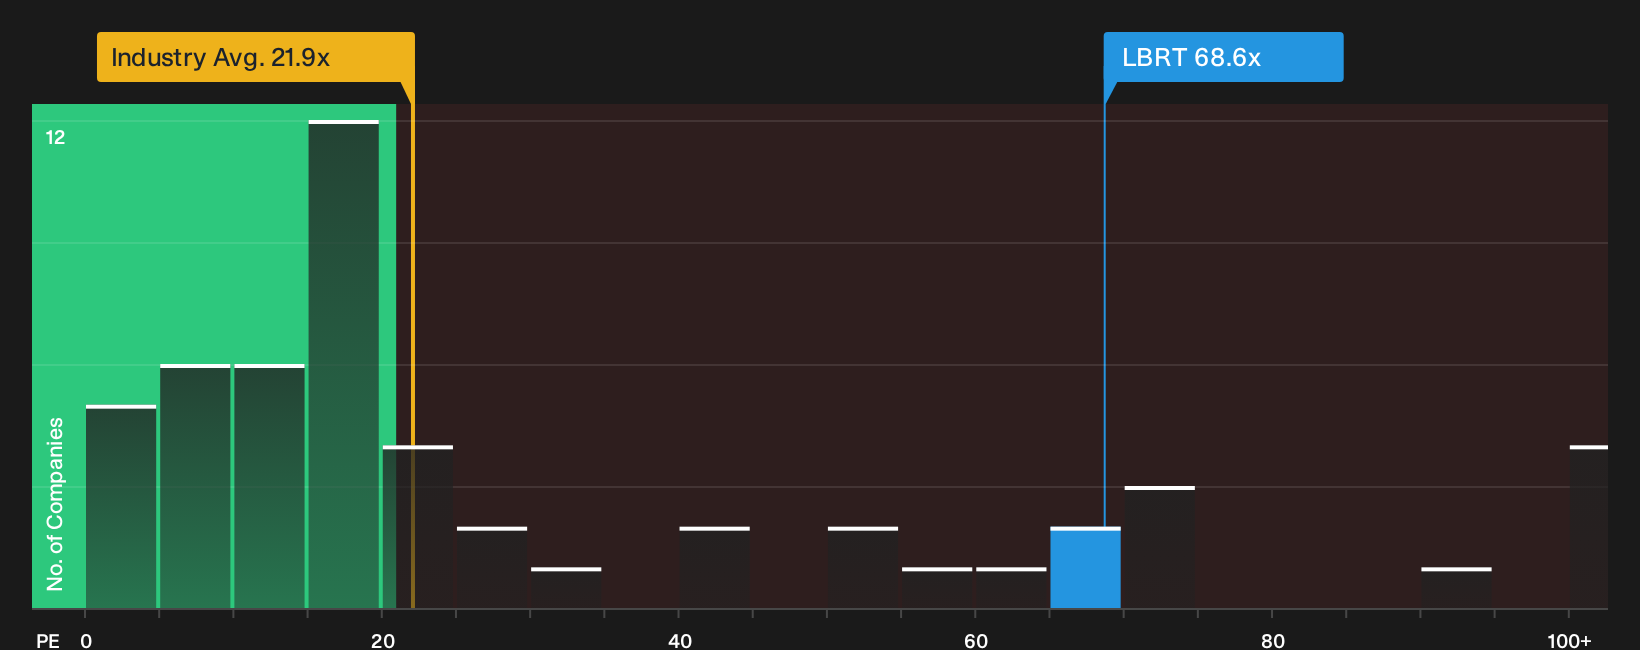
The story looks different when you step away from fair value targets and focus on simple earnings multiples. Liberty Energy trades on a P/E of 68.6x, while the US Energy Services industry sits at 21.9x and the fair ratio for the stock is 13.4x. That gap points to potential valuation risk if sentiment cools or earnings do not track optimistic forecasts. Investors may wish to consider how comfortable they are with paying today’s multiple given the level of uncertainty about future results.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Liberty Energy’s valuation and earnings can feel messy. Move quickly, review the underlying data for yourself, then weigh the 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Liberty Energy?
Do not stop at Liberty Energy. Broaden your watchlist with a few focused stock shortlists that spotlight different strengths and help you stress test your thinking across the market.
- Target resilience first by scanning a 30 resilient stocks with low risk scores that can help you focus on companies with steadier risk profiles when volatility picks up.
- Hunt for value by reviewing a 29 high quality undervalued stocks that highlights businesses combining quality fundamentals with prices that may not fully reflect those traits.
- Strengthen your core holdings by checking a list of solid balance sheet and fundamentals (24 results) so you can weigh companies with sturdier financial footing alongside more cyclical ideas.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com