


- In late October 2026, Lundin Gold reported strong conversion and near mine drilling results at Fruta del Norte in Ecuador, including confirmed mineralization continuity, new high grade zones, and progress toward upgrading Inferred Resources to Mineral Reserves.
- The detail that stands out is the rapid move from discovery to a 0.54 Moz Mineral Reserve at FDNS in about 18 months, which underlines how quickly drilling success around Fruta del Norte can translate into formal mine planning options.
- This analysis will focus on how Lundin Gold's existing investment narrative intersects with continued high grade drilling success around Fruta del Norte's core orebody.
Scan how Lundin Gold's drilling success compares with peers and identify other high grade producers on your radar with our curated 35 elite gold producer stocks.
Lundin Gold Investment Narrative Recap
To own Lundin Gold, you need to believe Fruta del Norte can keep running reliably, with high margin production and enough new ounces defined to support mine life over time. The latest conversion and near mine drilling results reinforce that the orebody model is holding together. The biggest short term swing factor remains how consistently the operation delivers against its throughput and grade plans.
On the risk side, very little changes near term. Lundin Gold is still a single asset producer in Ecuador with an unresolved tax assessment of about US$154 million and a dividend that is flagged as not well covered by earnings or free cash flow. The new drilling success does not directly affect those issues yet.
The most relevant recent development related to this drilling update is management’s ongoing push to grow and convert resources in the Fruta del Norte district, including FDNS, FDN East and Bonza Sur. The inaugural 0.54 Moz Mineral Reserve at FDNS in 2026, reached around 18 months after discovery, showed how quickly drilling can translate into mine planning options around the existing infrastructure.
In that context, the fresh conversion and step out results look operationally important because they aim to shift Inferred material into the Indicated and Reserve categories and keep Fruta del Norte’s production base supported by defined ounces. For investors watching catalysts, the key questions stay simple: How much additional mine life and scheduling flexibility does Lundin Gold ultimately book, and can that offset concentration, tax and dividend coverage risks over time?
Lundin Gold's current analyst narrative points to revenues of $2.5b and earnings of $1.1b by 2029, based on assumed yearly top line growth of 7.4% and an earnings increase of about $164.9m from $935.1m today.
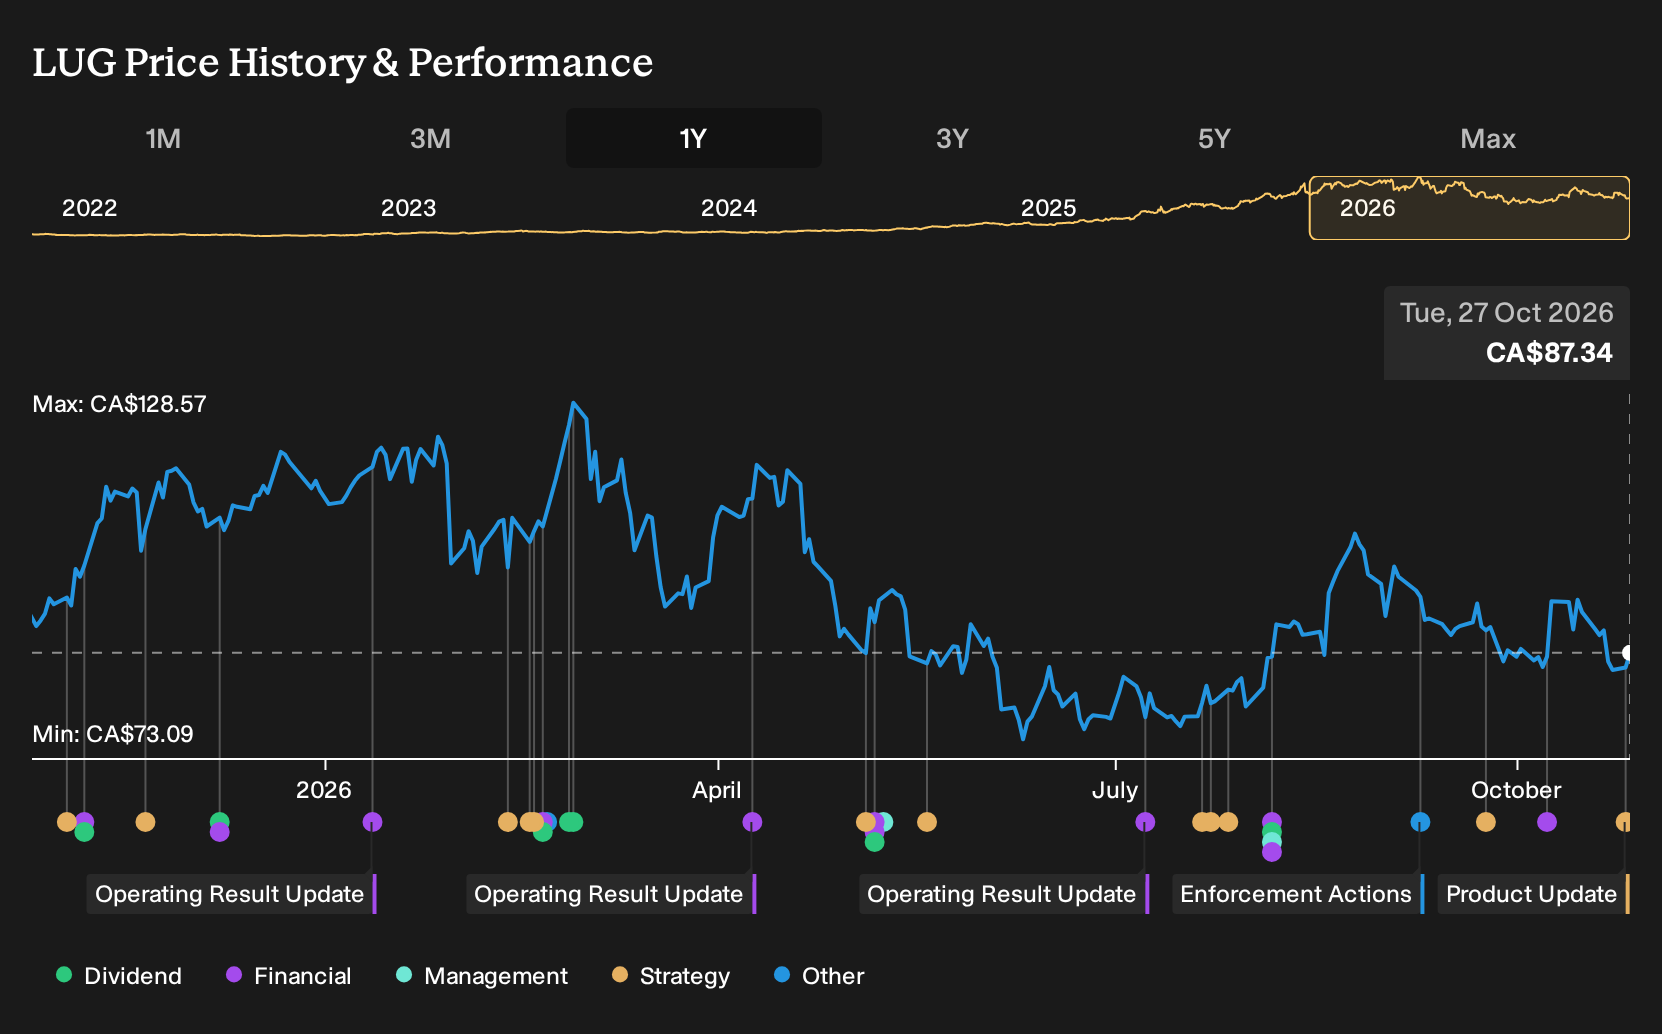
Uncover how Lundin Gold's fair value indicates a 9% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One angle the lowest Lundin Gold analysts stress is tax pressure rather than drilling upside. They already pencilled in slower revenue growth to about $2.3b and earnings of roughly $992.4m by 2029, before this FDN update. That is a more cautious story. Use it as a reminder that views can differ sharply and may shift again after this news.
Explore 3 other Lundin Gold fair value estimates, including one that suggests it could be worth just CA$95.45.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lundin Gold research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lundin Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lundin Gold's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lundin Gold?
If Lundin Gold is already on your watchlist, it can help to widen the net and see how other companies stack up on quality, value, and resilience using the Simply Wall St Screener.
- For investors hunting for strong businesses that still look attractively priced, start with a focused set of 3 high quality undervalued stocks that clear both quality and valuation filters.
- If stability and financial strength matter most to you, narrow the field to companies with robust balance sheets using our list of solid balance sheet and fundamentals (7 results) as your next port of call.
- When you want ideas that are off the beaten track yet supported by solid fundamentals, scan through a curated 9 high quality undiscovered gems that might not yet be on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com