


Onto Innovation (ONTO) heads into its 9 November 2026 earnings release with expectations for a 146.74% EPS increase and stronger revenue, putting the upcoming report squarely in focus for investors.
Onto Innovation shares trade at US$214.17 after a sharp 25.54% decline in the 30-day share price return, even though the year-to-date share price return is up 29.12% and the 1-year total shareholder return of 63.88% signals stronger longer run momentum.
See how Onto Innovation compares with other semiconductor players on earnings momentum and valuation by checking our curated list of 29 high quality undervalued stocks.
The chart has flipped fast for Onto Innovation, with a steep recent pullback sitting against strong trailing returns and upbeat earnings expectations. Does that reset leave enough upside to justify the risk at today’s price?
Most Popular Narrative: 44% Undervalued
Against the last close at $214.17, the most followed narrative on Onto Innovation pitches a fair value of $380. This frames expectations going into the earnings release in a very different light.
Onto Innovation is emerging as one of the most strategically important semiconductor equipment companies in the AI supply chain. While much investor attention remains focused on GPU manufacturers and memory suppliers, the next bottleneck increasingly lies in advanced packaging, the complex process of stacking, connecting, and inspecting AI chips and HBM memory at nanometer precision.
See why 38 investors see Onto Innovation as 44% undervalued.
Result: Fair Value of $380 (UNDERVALUED)
Still, this bullish Onto Innovation story can break if advanced packaging capex slows sharply or if a rival process control platform wins key HBM and TSMC sockets.
Find out about the key risks to this Onto Innovation narrative.
Another View: Onto Innovation Looks Expensive On Earnings
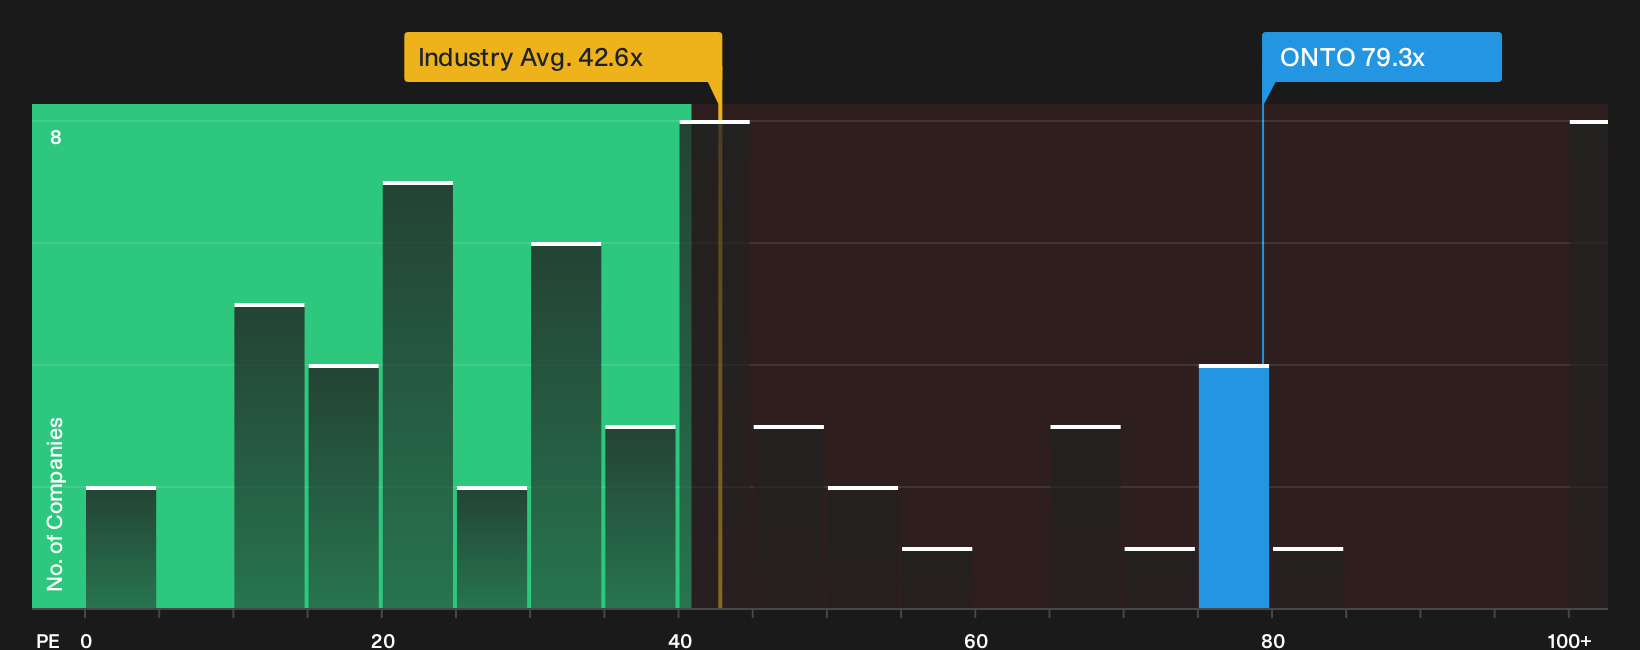
The US$380 fair value anchor presents a very different picture when you look at how Onto Innovation is priced on current earnings. The stock trades on a P/E of 79.3x, compared with 42.6x for the US semiconductor industry and a 39.9x peer average. The fair ratio sits at 44.4x.
In plain terms, the market is already paying a heavy premium to both sector and peer benchmarks, as well as to where the P/E could converge if it moved toward that fair ratio. For anyone weighing the bullish narrative, the key consideration is whether the growth case is strong enough to justify that extra valuation risk or whether patience is more appropriate at this multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Onto Innovation can create both opportunities and risks, so move quickly to review both sides of the story and weigh the 3 key rewards and 3 important warning signs.
Looking for more Onto Innovation style opportunities?
If you only stop at Onto Innovation, you risk missing other ideas that fit your goals, so put the screener to work and keep your watchlist fresh.
- Target potential mispricings by scanning a focused set of quality candidates through the 29 high quality undervalued stocks.
- Strengthen your income stream by hunting for robust payers using the 5 dividend fortresses.
- Prioritise resilience by filtering for financially solid businesses via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com