


ArcBest (ARCB) has drawn fresh attention after recent trading, with the share price closing at US$130.34. Investors are weighing that move against returns over the past month, the previous 3 months, and longer multi year periods.
Recent trading suggests momentum for ArcBest is still skewed to the upside, with a 1 day share price return of 3.16% compared with a 90 day share price return that declined 7.88%, while the 1 year total shareholder return of 78.53% points to a much stronger long run picture.
Scan how ArcBest's recent momentum compares with peers by checking a curated set of transport and logistics stocks in the list of solid balance sheet and fundamentals (24 results).
After that sharp swing in ArcBest, the real fork in the road is simple. Do you lean into the current price, or wait and hope for a cheaper entry that may not show up soon?
Most Popular Narrative: 23% Undervalued
On the narrative view, ArcBest screens as undervalued, with a fair value of about $169.77 against the last close at $130.34. This raises a simple question for investors about whether the market is fully crediting its freight mix and cost reset story.
The main thing that has to go right is that ArcBest continues to execute on network optimization, AI-enabled cost savings and asset-light restructuring so that the expected annualized savings and productivity gains show through in future profitability. Ongoing network and cost-structure optimization, including terminal rationalization, brand consolidation and workforce reductions that are expected to reach about US$40 million in annualized savings by early 2027, positions ArcBest to convert incremental revenue into stronger net margins.
See why 4 investors see ArcBest as 23% undervalued.
Result: Fair Value of $169.77 (UNDERVALUED)
Still, if freight demand stays muted or heavier shipments continue to weigh on LTL yield, the bullish ArcBest margin story could easily lose momentum.
Find out about the key risks to this ArcBest narrative.
Another View: ArcBest On Sales Ratios
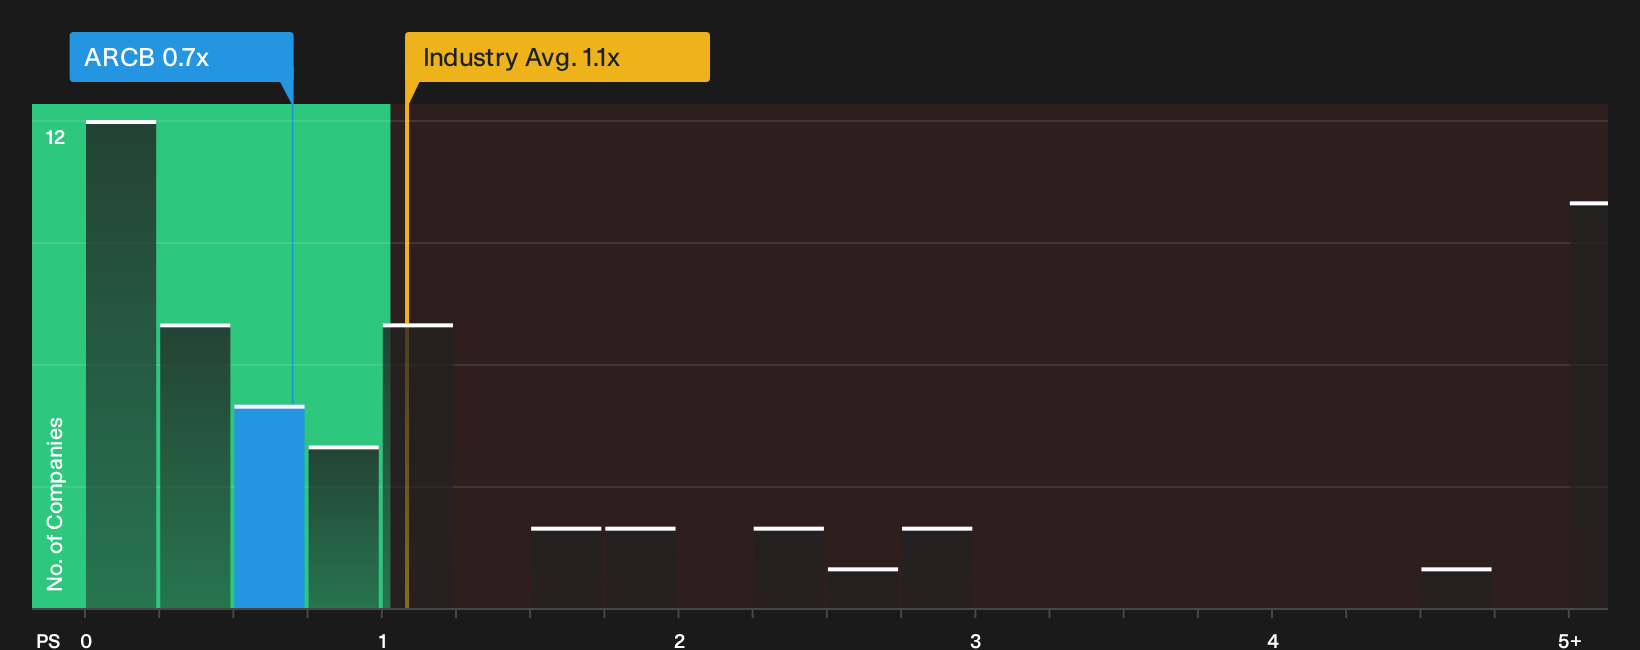
The DCF narrative presents ArcBest as meaningfully undervalued, yet the sales multiple sends a more cautious message. At a P/S of 0.7x versus a fair ratio of 0.6x, the stock appears somewhat expensive on this measure, which raises a simple question: Is the DCF too generous, or is the market underestimating the freight reset story?
To see how that sales multiple compares with peers and how the fair ratio might influence it over time, take a closer look at the valuation work behind See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on ArcBest's valuation story. If you want to move fast and rely on your own judgment, start by weighing the 3 key rewards and 3 important warning signs.
Looking for more ArcBest style investment ideas?
If ArcBest has sharpened your focus, widen the lens and put fresh ideas on your radar before the next move leaves you reacting instead of prepared.
- Hunt for quality at a discount by scanning the 29 high quality undervalued stocks and lining up candidates that match your return and risk expectations.
- Stack potential income streams by reviewing the 5 dividend fortresses and seeing which payouts match your goals for yield and stability.
- Prioritise resilience first by filtering for the 30 resilient stocks with low risk scores and shortlisting companies that may better fit a sleep at night portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com