


- Holmen has split its Forest business into two units, separating wood supply into a stand-alone operation, and reported Q3 2026 results with sales of SEK 4,945 million and net income of SEK 391 million, both below the prior year period.
- The new wood supply unit is now tasked with optimising purchasing and deliveries for Holmen’s mills, while the Forest business focuses on long term value creation from the group’s own forest land. This reshapes how costs and returns are managed across the industrial portfolio.
- The focus now shifts to how Holmen’s investment narrative could be reshaped by weaker earnings and the Forest business split.
Look beyond Holmen and compare this restructuring story with other asset heavy businesses by checking which ones are in our list of solid balance sheet and fundamentals (207 results).
Holmen Investment Narrative Recap
To own Holmen, you need to be comfortable with a cyclical industrial group that leans on premium board and paper niches, large forest assets and volatile energy income. The Q3 2026 dip in sales to SEK 4,945 million and net income to SEK 391 million keeps the near term story centered on earnings pressure and softer profitability.
The immediate swing factor is whether core mills keep running efficiently while Wood Products and Energy work through weak conditions. The key risk remains prolonged loss making in Wood Products or repeated storm and power grid issues, which could keep returns low and limit how much value Holmen can pull from its SEK 57b forest and land base.
The most relevant announcement here is the Q3 2026 report, because it puts hard numbers around Holmen’s starting point as the Forest area is divided. Nine month net income of SEK 1,518 million compared with SEK 2,298 million a year earlier makes it clear that the business is coming into this new structure after a period of lower profitability.
That context matters for catalysts. Any improvement in wood pricing, board mix or energy pricing will now show up against a backdrop of weaker recent earnings, while operational missteps in the new wood supply unit could quickly hit mill costs. For you, the question is how much execution risk feels acceptable given Holmen’s asset base and earnings profile.
Holmen's narrative projects SEK 22.3b revenue and SEK 2.7b earnings by 2029. This assumes fairly flat yearly revenue and no change in earnings from current earnings of SEK 2.7b.
Uncover why Holmen's fair value indicates a 14% potential upside to its current price that could narrow quickly as sentiment around Holmen adjusts.
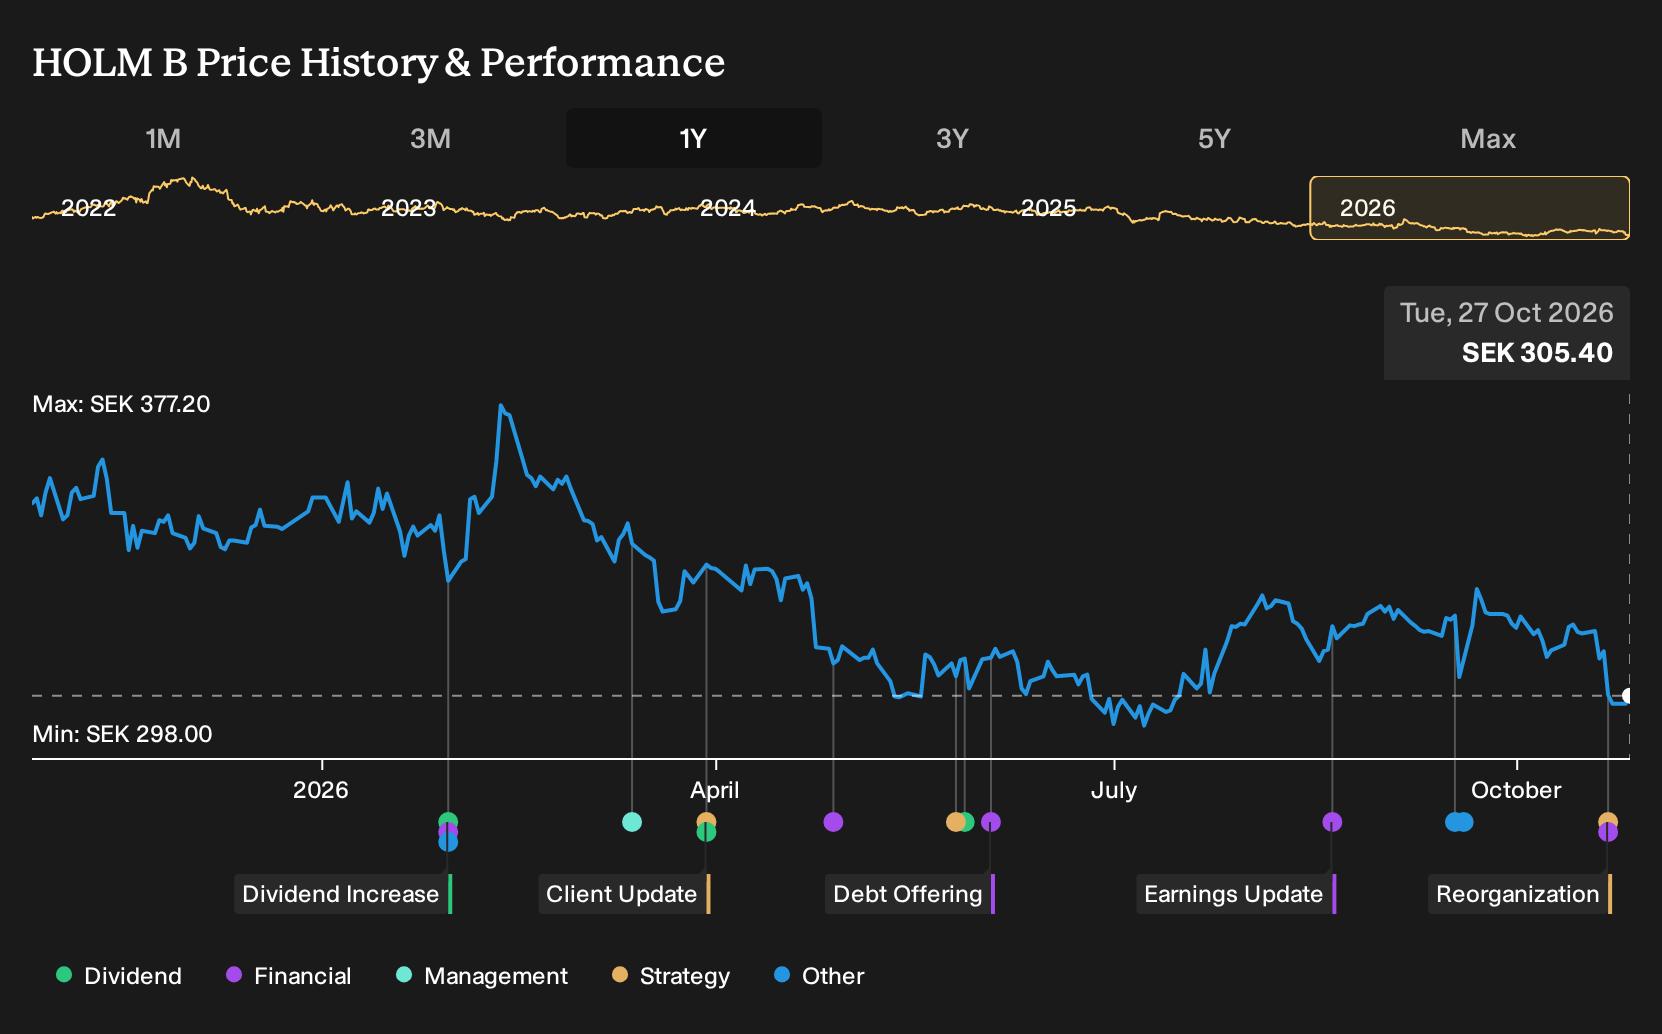
Exploring Other Perspectives
One alternate angle on Holmen focuses on the bullish catalyst of land and energy monetisation. The most optimistic analysts were already pencilling in revenue of about SEK 23.9b and earnings of roughly SEK 3.4b by 2029. That is a far brighter path than consensus. Q3’s weaker earnings and the Forest split may nudge these stories in different directions, so use this as a prompt to compare several viewpoints before deciding what feels reasonable to you.
Explore 2 other Holmen fair value estimates, including one that suggests as much as 15% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Holmen research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Holmen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Holmen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Holmen?
Holmen might be the starting point, but your portfolio benefits when you weigh it against a wider set of opportunities using the Simply Wall St Screener.
- For investors who want resilient balance sheets and solid fundamentals, scan our list of solid balance sheet and fundamentals (207 results) and see which businesses match that profile.
- If value is your focus and you prefer companies where quality meets a lower implied price, take a look at the 195 high quality undervalued stocks and compare those setups with Holmen.
- When you want ideas that are less crowded and backed by strong financial underpinnings, the 610 high quality undiscovered gems can surface under-the-radar stocks worth a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com