


Investor focus around Praxis Precision Medicines (PRAX) is building ahead of third quarter 2026 results on November 9 and an Investor Day on November 12, which will be centered on ulixacaltamide and relutrigine launch plans.
Against that backdrop, Praxis Precision Medicines has seen a mixed pattern in recent months, with the share price down 4.7% over the past 30 days and 8.1% over 90 days, even as total shareholder return over one year reached 34.2% and the three year total shareholder return has been extremely strong. This suggests the upcoming earnings release and Investor Day could be acting as a fresh catalyst for reassessing both growth potential and risk around its late stage neurology pipeline.
Scan beyond Praxis Precision Medicines and explore other neurology focused opportunities by reviewing the hand picked 34 healthcare AI stocks that could benefit as new CNS therapies come to market.
Praxis Precision Medicines trades at a steep discount to both analyst targets and estimated fair value after a strong three year run. Is the market prudently pricing late stage risk, or overly penalising execution uncertainty?
Most Popular Narrative: 58% Undervalued
Praxis Precision Medicines closed at $267.59, while the most followed narrative pegs fair value at $643.06 using a 7.4% discount rate. This frames the current price as materially below those long term assumptions.
Multiple late stage epilepsy programs, including vormatrigine and relutrigine with breakthrough designation in severe genetic epilepsies, create a portfolio effect in a growing CNS innovation cycle. This increases the probability of multiple approvals and a step change in total company earnings over the back half of the decade.
See why 8 investors see Praxis Precision Medicines as 58% undervalued.
Result: Fair Value of $643.06 (UNDERVALUED)
Still, the Praxis Precision Medicines story can change quickly if key epilepsy trials disappoint or if vormatrigine setbacks deepen and reshape how investors view the pipeline.
Find out about the key risks to this Praxis Precision Medicines narrative.
Another View on Praxis Precision Medicines Valuation
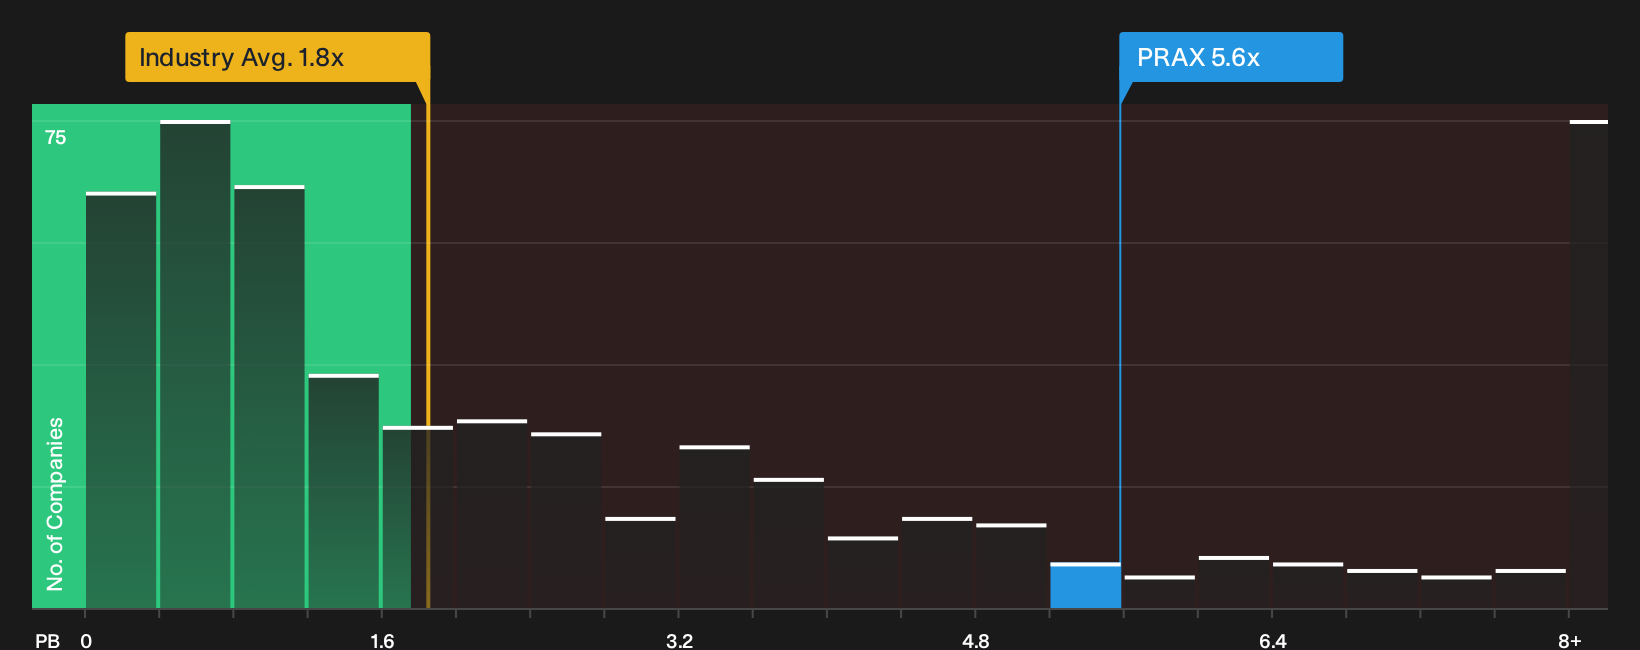
Analysts frame Praxis Precision Medicines as 58% undervalued on long term earnings forecasts, yet the share price tells a more complicated story. On P/B, the stock trades at 5.6x, which is expensive versus the US Biotechs average of 1.8x, although it sits below the 7.9x peer average.
This gap means investors weighing the Praxis Precision Medicines story are balancing a deep discount to earnings based fair value against an already rich balance sheet multiple. The key question is whether future execution justifies paying up on P/B when the rest of the sector is cheaper.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Praxis Precision Medicines can feel confusing. Move quickly, review the full data set, and weigh both sides for yourself with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Praxis Precision Medicines?
If Praxis Precision Medicines is on your radar, you may want to round out your research by comparing it with other clear opportunities that match different risk and return profiles.
- Target potential mispricings and compare them side by side with Praxis by scanning the 29 high quality undervalued stocks that share strong fundamentals.
- Seek more predictable cash flows in your portfolio by reviewing the 5 dividend fortresses that focus on higher yielding payout streams.
- Dial down portfolio volatility and offset biotech risk by checking the 30 resilient stocks with low risk scores that rate well on financial resilience and stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com