


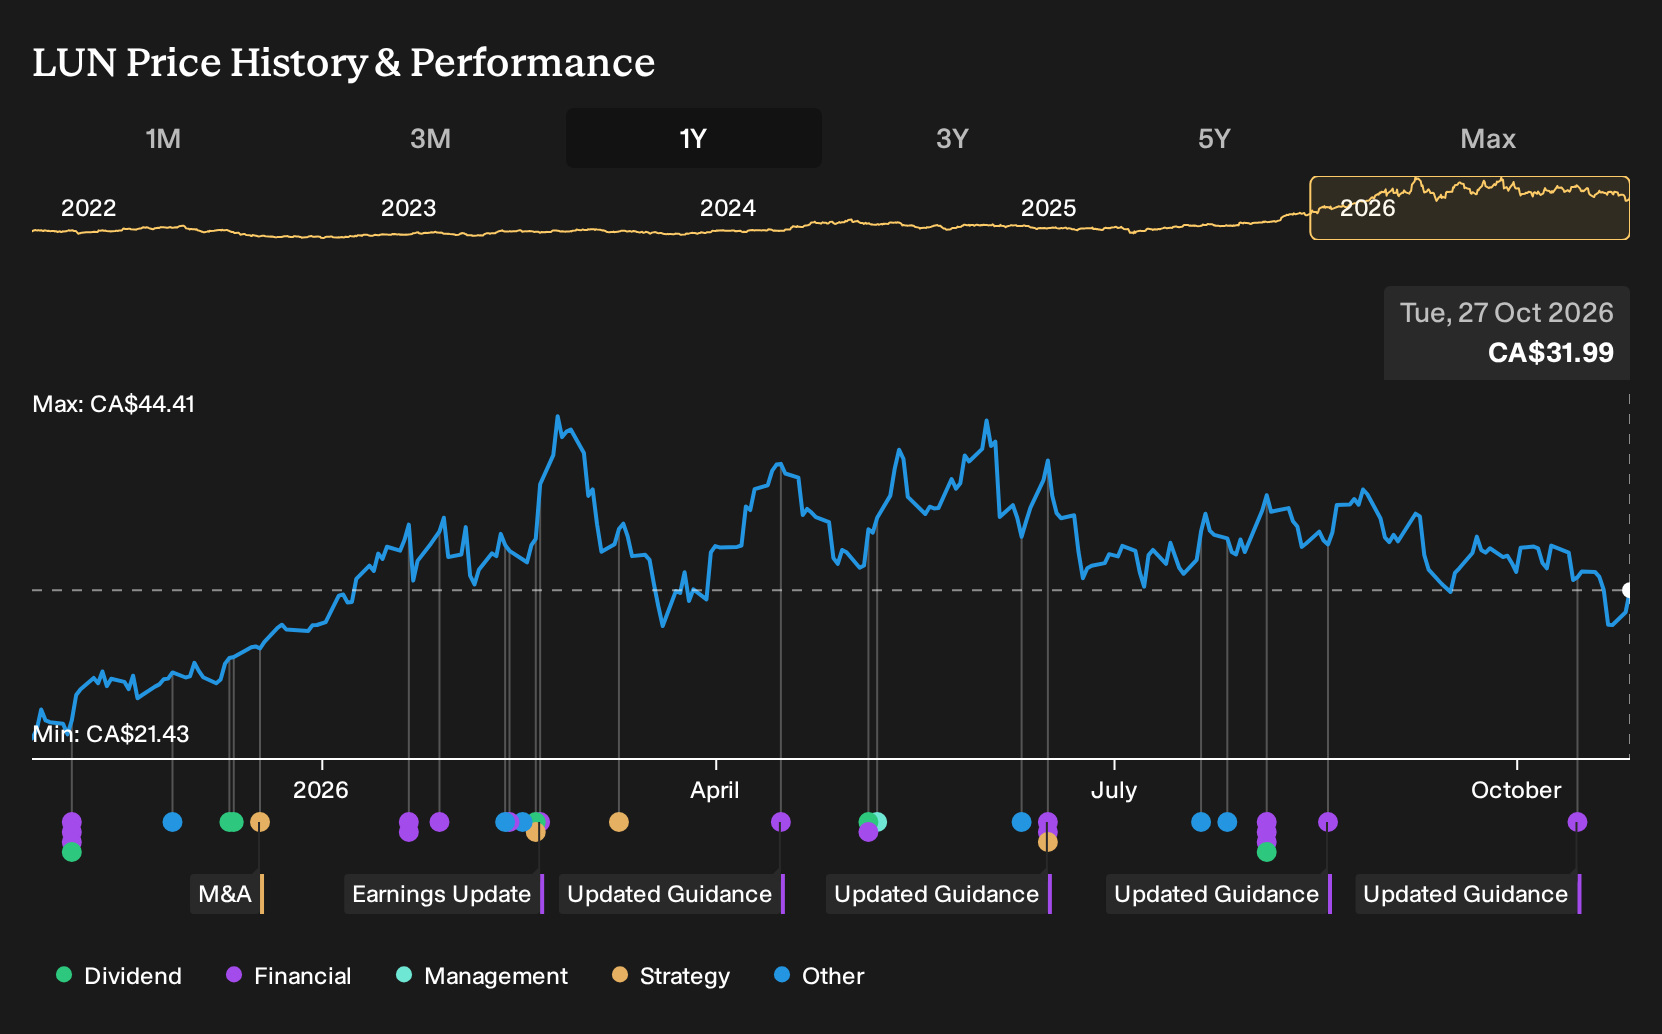
- In October 2026, Lundin Mining issued quarterly revenue guidance that includes an expected positive impact of about $51 million from unaudited provisional pricing adjustments on prior period copper concentrate sales.
- The focus on upward adjustments to historical copper sales highlights how Lundin Mining’s exposure to copper pricing mechanics can meaningfully influence near term reported revenue without any immediate change in production volumes.
- We will now assess how Lundin Mining's investment narrative could shift in light of the $51 million copper pricing uplift.
Scan how other copper producers are positioned for similar pricing shifts by reviewing the hand-picked 16 top copper producer stocks shaping the next leg of earnings-sensitive moves.
Lundin Mining Investment Narrative Recap
Lundin Mining appeals to shareholders who want concentrated exposure to copper-heavy assets in Chile and Brazil, with Candelaria, Caserones and Chapada driving the bulk of revenue. The big question is whether current operations and projects like Vicuña and Saúva can turn into durable, repeatable cash generation rather than just one-off pricing wins.
The provisional copper pricing uplift of about $51 million is helpful for the upcoming quarter but does not change the main near-term swing factors. Investors are still watching cost control, execution on expansion projects and any sign that South American regulatory or political risk could start to pressure volumes, capex timing or margins.
The October 2026 guidance around the $51 million provisional pricing adjustment is the announcement that matters most here. It directly ties reported revenue to prior copper price moves, rather than to new tonnes mined or processed. As a result, it gives a clearer read on how sensitive Lundin Mining is to price mechanics built into its concentrate contracts.
For catalysts, that guidance sharpens focus on the next operating and financial updates, where you will want to separate one-off pricing effects from underlying performance at Candelaria, Caserones and Chapada. It also underlines an existing risk: heavy copper exposure, combined with capital-intensive projects and higher-risk funding, can make earnings swings larger when prices move in the opposite direction.
Lundin Mining's current earnings are about US$1.4b and consensus expects earnings to be US$1.2b by 2029. This implies an earnings decline of roughly US$200m, alongside analyst assumptions that revenue stays broadly flat over that period while profit margins compress.
Uncover why Lundin Mining's fair value indicates a 37% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The most optimistic Lundin Mining narrative leans heavily on volume growth as the real catalyst. Before this pricing news, the bullish camp was pencilling in revenue of about US$5.6b and earnings of US$1.2b by 2029. You can see how different that is from consensus, and how this new copper adjustment might later reshape both stories.
Explore 3 other Lundin Mining fair value estimates, including one that suggests as much as 279% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lundin Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lundin Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lundin Mining's overall financial health at a glance.
Looking for more Lundin Mining style ideas?
Once you have a view on Lundin Mining, it can help to compare that thesis with other companies that match the kind of risk and return profile you want in your portfolio.
- If you want potential upside but still care about balance sheet strength, start with a list of solid balance sheet and fundamentals (7 results) that can handle tougher conditions without relying on constant refinancing.
- If value is your priority, sort through a 3 high quality undervalued stocks where fundamentals and pricing work together instead of pulling in opposite directions.
- If you prefer steadier cash returns, focus on a 3 dividend fortresses that aims to combine income with resilient business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com