


- Blackstone joined Bank of America, Citi and Morgan Stanley in a US$63b AI infrastructure financing deal, serving as the sole provider of committed second lien funding to support Broadcom hardware that will be leased to Anthropic.
- The financing underlines Blackstone’s push into AI compute infrastructure as a fee source linked to real world demand for accelerator capacity.
- We will look at how Blackstone’s investment narrative evolves as it takes sole second lien risk in this AI infrastructure financing.
Scan how Blackstone’s AI push compares with other infrastructure and compute plays by jumping into our curated list of 55 AI infrastructure stocks.
Blackstone Investment Narrative Recap
To own Blackstone, you need to believe its large alternatives platform, perpetual capital products and insurance relationships keep driving fee based earnings even as real estate and leadership transitions introduce bumps. The latest quarter supports that narrative. Revenue of US$3,062.89m and net income of US$662.37m were close to last year, with earnings per share inching higher.
In the short term, the key swing factor is how quickly Blackstone converts its fundraising momentum and AI infrastructure push into realized performance fees. Real estate stress and leadership changes remain the main operational risk. The recent AI financing and Q3 numbers do not materially change that risk reward balance right now.
The earnings release is the clearest operational marker to focus on, alongside the AI infrastructure financing. Over nine months, Blackstone reported US$11,724.46m of revenue and US$2,541.29m of net income, both above the prior year. Basic EPS from continuing operations moved to US$3.20 from US$2.57, with diluted EPS at US$3.19.
For you, the question is how those figures connect to the next leg of the story. Higher year to date profit gives Blackstone more room to support investments such as AI compute and potential deals such as the Accord Software Systems minority stake, while any future pressure from real estate, debt levels or dividend coverage could still weigh on how consistently those earnings turn into cash for shareholders.
Blackstone's latest analyst narrative points to forecast revenue of US$22.1b and projected earnings of US$11.3b by 2029, based on an assumed 12.6% yearly revenue growth rate and an earnings increase of about US$7.8b from current earnings of US$3.5b.
Discover how Blackstone's fair value indicates a 20% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
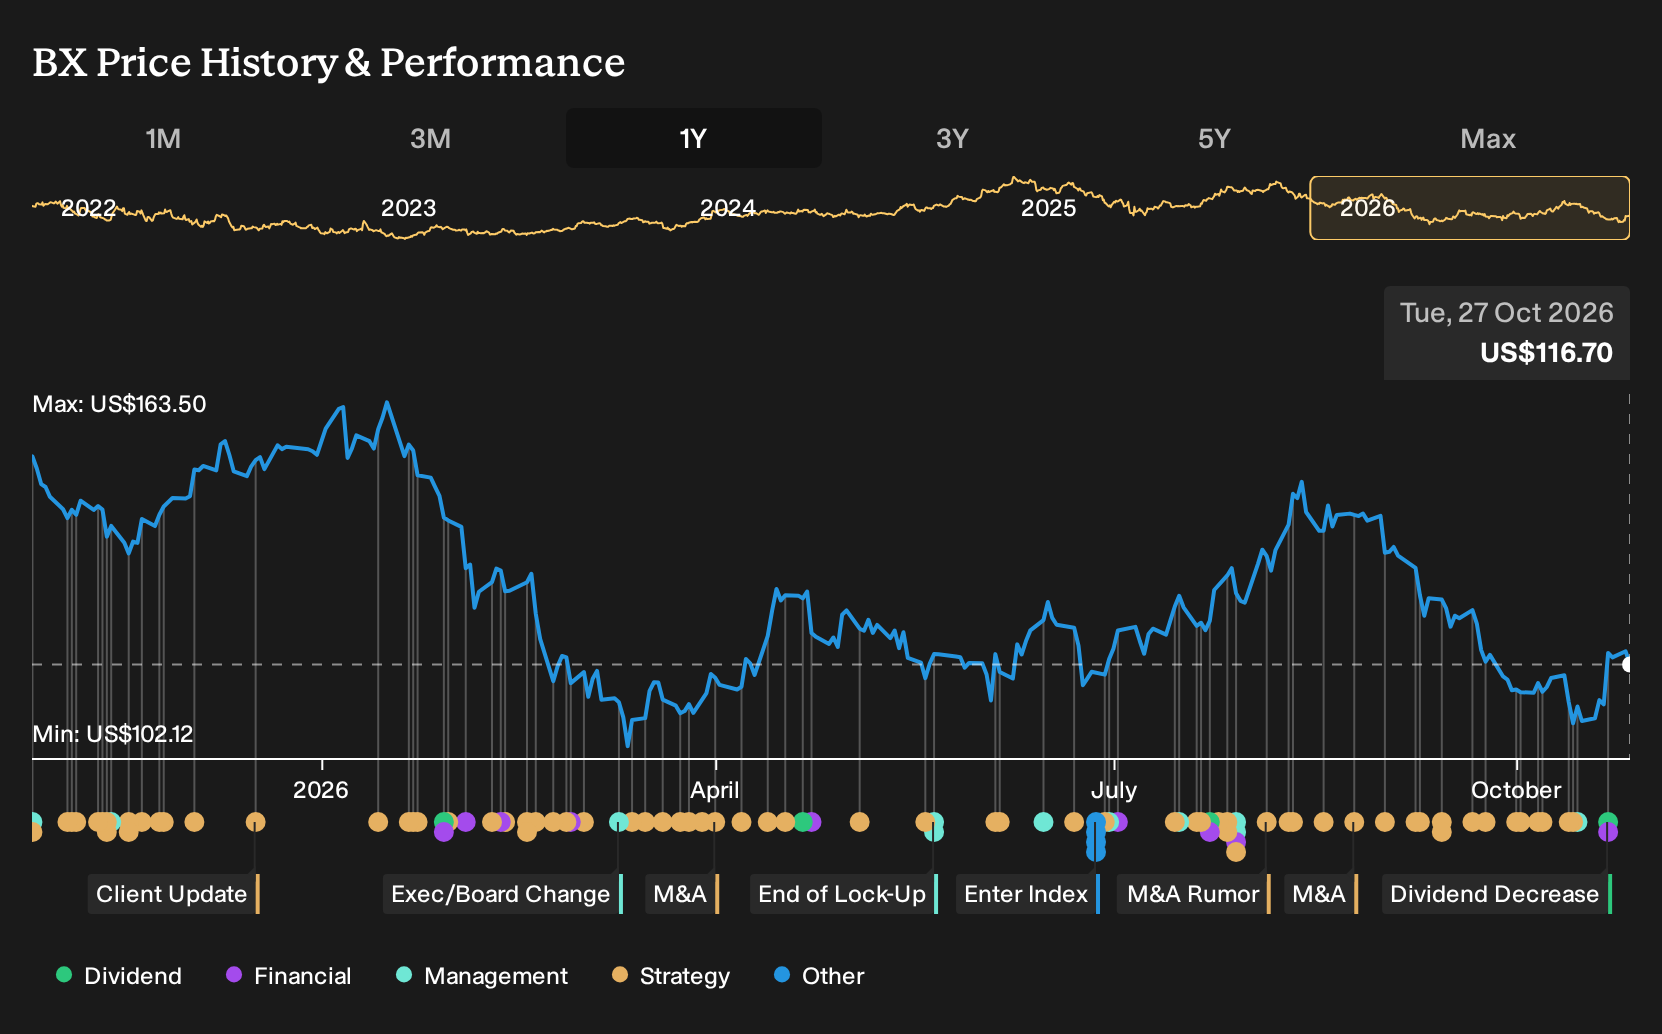
One bearish twist focuses on liquidity pressure in products like BCRED rather than real estate stress. The most cautious analysts saw Blackstone reaching about US$20.7b of revenue and US$11.7b of earnings by 2029, yet only backing a US$116 price target. Those views were set before this AI financing and might shift.
Explore 4 other Blackstone fair value estimates, including one that suggests it could be worth just $116.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Blackstone research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Blackstone. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Blackstone's overall financial health at a glance.
Looking For More Investment Ideas Beyond Blackstone?
If you want to stress test your view on Blackstone, it helps to line it up against other opportunities that share some of the same qualities you care about. The Simply Wall St Screener lets you filter by balance sheet strength, income focus or mispriced quality so you can see how different candidates stack up side by side.
- If capital preservation is your priority, start with companies that show lower risk profiles and resilient fundamentals through the 30 resilient stocks with low risk scores.
- If you are hunting for income, compare yield focused opportunities that may support stronger cash distributions using the 5 dividend fortresses.
- If you want to find under the radar quality, line Blackstone up against potential compounders by scanning our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com