


CleanSpark (CLSK) is back in focus after a recent share pullback that coincided with cautious sentiment ahead of its next earnings report, where analysts expect weaker earnings per share and revenue.
The recent slide has been sharp. CleanSpark’s 30 day share price return is down 38.6% and the 90 day share price return is down 43.7%, while the 1 year total shareholder return is down 56.6% despite a 3 year total shareholder return of 97.8%. This suggests that sentiment has cooled as investors factor in weaker earnings expectations and higher perceived risk ahead of the upcoming results.
Scan beyond CleanSpark and pressure driven setups like this by reviewing our curated list of 16 cryptocurrency and blockchain stocks that are already on investors' radar.
CleanSpark now trades far below the average analyst price target after this pullback, while sentiment remains cautious ahead of weaker earnings projections. Is this a simple discount, or a fair warning signal on valuation risk?
Most Popular Narrative: 66% Undervalued
CleanSpark last closed at $8.19, while the most followed narrative pegs fair value at $23.81 using a 10.08% discount rate and long term lease economics as key inputs.
CleanSpark's fully self-operated, scalable, and power-efficient infrastructure enables it to mine Bitcoin at a significantly lower cost than the market price, with further capacity expansion (additional 10 exahash and over 200 megawatts of contracted power ready for rapid deployment) poised to drive sustained increases in Bitcoin production, improving revenue and supporting higher net margins.
See why 132 investors see CleanSpark as 66% undervalued.
Result: Fair Value of $23.81 (UNDERVALUED)
Still, CleanSpark’s heavy dependence on Bitcoin mining economics, along with the capital required to keep upgrading its fleet, could quickly undermine this undervaluation narrative if conditions turn.
Find out about the key risks to this CleanSpark narrative.
Another View: CleanSpark’s Price-To-Sales Gap
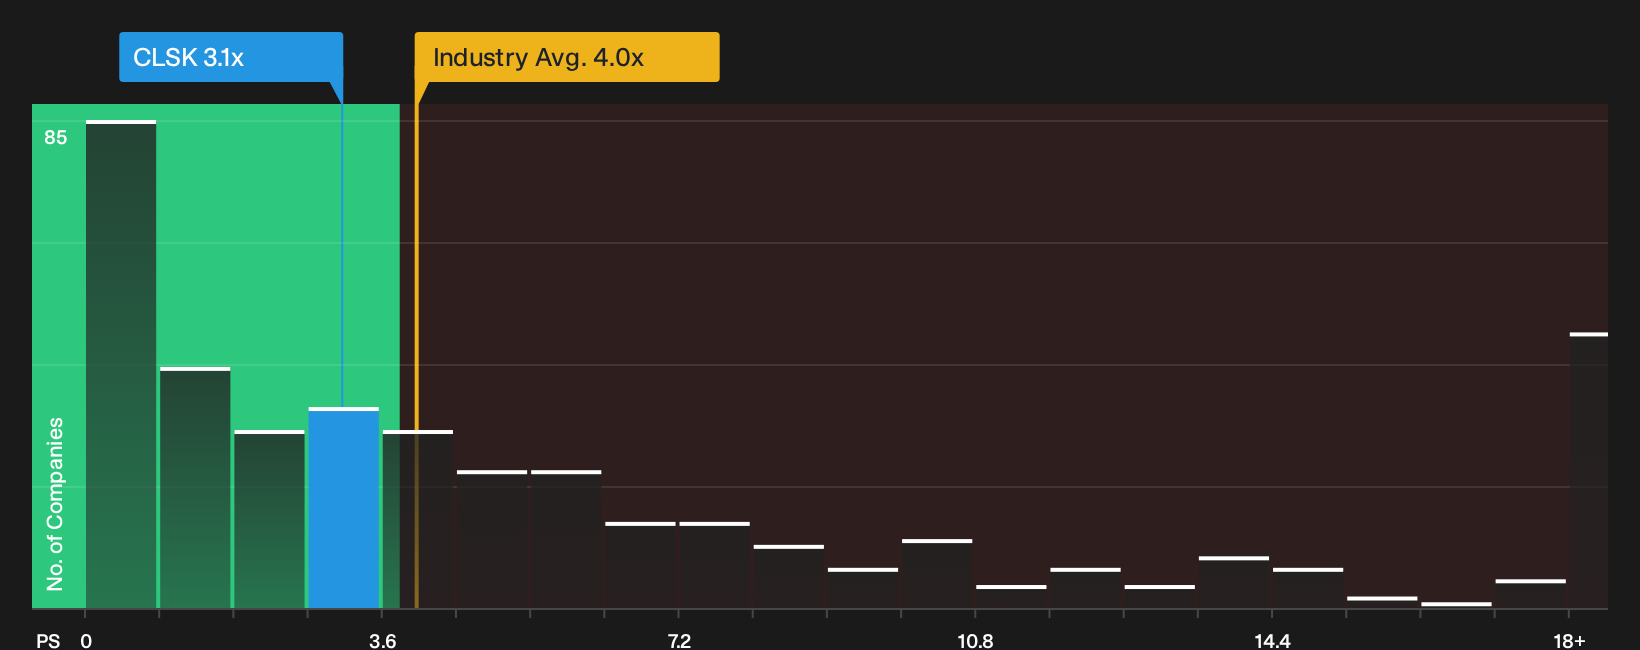
The analyst narrative presents CleanSpark as materially undervalued, yet its current P/S of 3.1x sits above an estimated fair ratio of 2.1x. That fair ratio is a level the market could move toward, which would indicate valuation risk if sentiment on Bitcoin mining weakens again.
This P/S of 3.1x is also richer than the fair ratio but lower than both the broader US Software group at 4x and peer averages at 4.7x. The stock screens cheaper than those groups, but not versus its own fair ratio, which leaves a simple question: Are you more anchored to what analysts see, or to where the multiple could compress toward?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this CleanSpark story is split. Move quickly, test the numbers for yourself, and weigh both the upside and the downside using 1 key reward and 3 important warning signs
Looking for more investment ideas beyond CleanSpark?
If CleanSpark has your attention, do not stop here. Broaden your watchlist with a few targeted idea lists that match different investing goals and risk levels.
- Zero in on potential mispricings by scanning a focused set of 29 high quality undervalued stocks that pair quality fundamentals with what looks like discounted market expectations.
- Stack your portfolio with dependable income by assessing companies in the 5 dividend fortresses that offer higher yields with business models built around regular cash returns.
- Dial down volatility while staying invested by reviewing the 30 resilient stocks with low risk scores that score well on financial strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com