


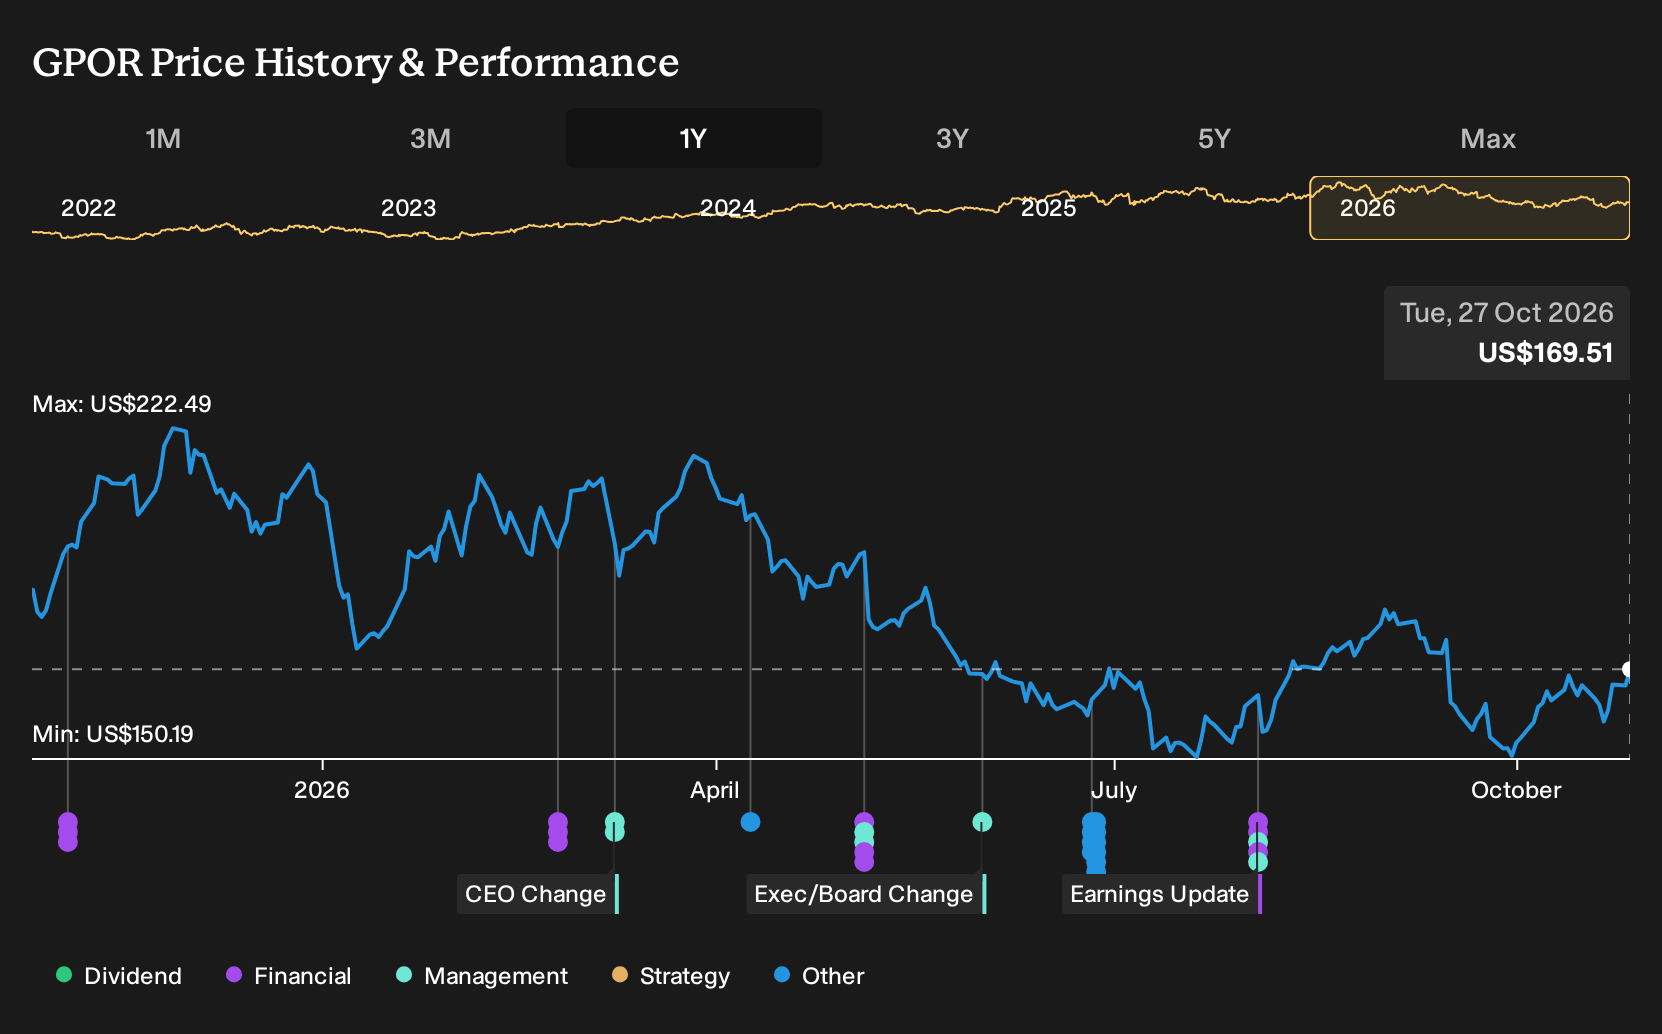
- Gulfport Energy is approaching its scheduled earnings release on 4 November 2026, with an Earnings ESP of +10.53% and a Zacks Rank #3, following recent commentary on its operational efficiency and disciplined capital allocation in the Appalachian and Anadarko basins.
- The focus on cost control, productivity gains and measured capital spending highlights how Gulfport Energy’s operating choices, rather than external hype, are shaping expectations around the upcoming results.
- We will now look at how Gulfport Energy’s positive Earnings ESP and upcoming report could influence the existing investment narrative.
Scan how Gulfport Energy’s approach compares with other operators focusing on efficiency and balance sheet strength by reviewing the hand-picked list of solid balance sheet and fundamentals (24 results) in similar sectors.
Gulfport Energy Investment Narrative Recap
To own Gulfport Energy, you need to be comfortable with a gas weighted producer that leans on drilling efficiency, liquids growth and disciplined spending in Appalachia and Anadarko. The upcoming report, flagged by a positive Earnings ESP, speaks directly to that execution. The key short term swing factor remains how effectively Gulfport Energy turns its cost work and acreage spending into resilient cash generation in a choppy commodity backdrop.
The biggest near term risk is that weaker gas pricing or softer demand limits the value of the enlarged Appalachia inventory, especially after planned discretionary acreage purchases. Recent earnings expectations do not materially change that core risk. They simply sharpen the focus on whether operational gains and low transport costs can offset any pressure on realized prices and margins.
Recent commentary around Gulfport Energy’s drilling and completion gains in the Utica and Marcellus ties closely to this earnings setup. Efficiency improvements, including faster drilling and about a 25% reduction in Marcellus drilling and completion cost per foot on the latest long lateral pad, go straight to unit cost and free cash flow resilience if sustained.
Planned US$140 million of discretionary land purchases in 2026, with US$83 million already committed in an Ohio auction, is the other key piece to watch as results arrive. Those bolt on deals add roughly 20% more Appalachia locations, which can support future production volumes, but they also raise the bar on execution given analyst concerns about returns if acquisition prices prove high relative to eventual well economics.
Gulfport Energy’s current analyst narrative references forecast revenues of US$1.7b and consensus earnings of US$531.7 million by 2029, built on an assumed 7.9% yearly revenue growth rate and an earnings increase of about US$44.6 million from US$487.1 million today.
Uncover how Gulfport Energy's fair value indicates a 27% potential upside to its current price, which could narrow quickly if Gulfport Energy executes on its current plan.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit far apart, between about US$215 and US$1,133, which shows just how differently retail investors can view Gulfport Energy. When you pair that with risks around gas pricing, discretionary land spending and recent revenue pressure, you are looking at a wide field of competing narratives to explore.
Explore another Gulfport Energy fair value estimate, including one that suggests as much as 568% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gulfport Energy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gulfport Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gulfport Energy's overall financial health at a glance.
Looking for more investment ideas beyond Gulfport Energy?
Once you have a view on Gulfport Energy, it can help to scan a wider field of opportunities so your portfolio is not overly tied to a single gas focused producer.
- If you want potential upside with a stronger margin of safety, consider screening for quality companies trading below what their fundamentals might justify through the 29 high quality undervalued stocks.
- For income focused portfolios that value consistency from cash payouts, filter for reliable payers using the 5 dividend fortresses.
- When capital preservation and balance sheet strength matter most, start with financially robust businesses by using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com