


D-Wave Quantum has swung from deep losses in recent years to a very large 3 year share price gain, which puts a spotlight on whether its current US$12.13 level lines up with what the balance sheet actually supports. With the stock still volatile and the business investing heavily in quantum hardware and services, the open issue for you is how much book value can reasonably anchor that price.
- Over the past 3 years the stock has delivered a return of roughly 16 times an initial investment, which raises the stakes on whether the underlying net assets can justify such a step change in market value.
- The recent delivery of the Advantage2 system in Italy and a growing commercial footprint may support expectations for future revenue and capital needs that sit well ahead of what today’s equity base alone might suggest.
- The analysts covering D-Wave Quantum have run their own numbers. See what analysts think D-Wave Quantum's shares could be worth.
The issue now is whether D-Wave Quantum’s current share price is adequately backed by its book value when set against the industry average.
If you want more context around quantum-exposed opportunities rather than focusing on a single ticker, a targeted screen of 25 quantum computing stocks may be useful.
Does D-Wave Quantum Look Pricey on Book Value?
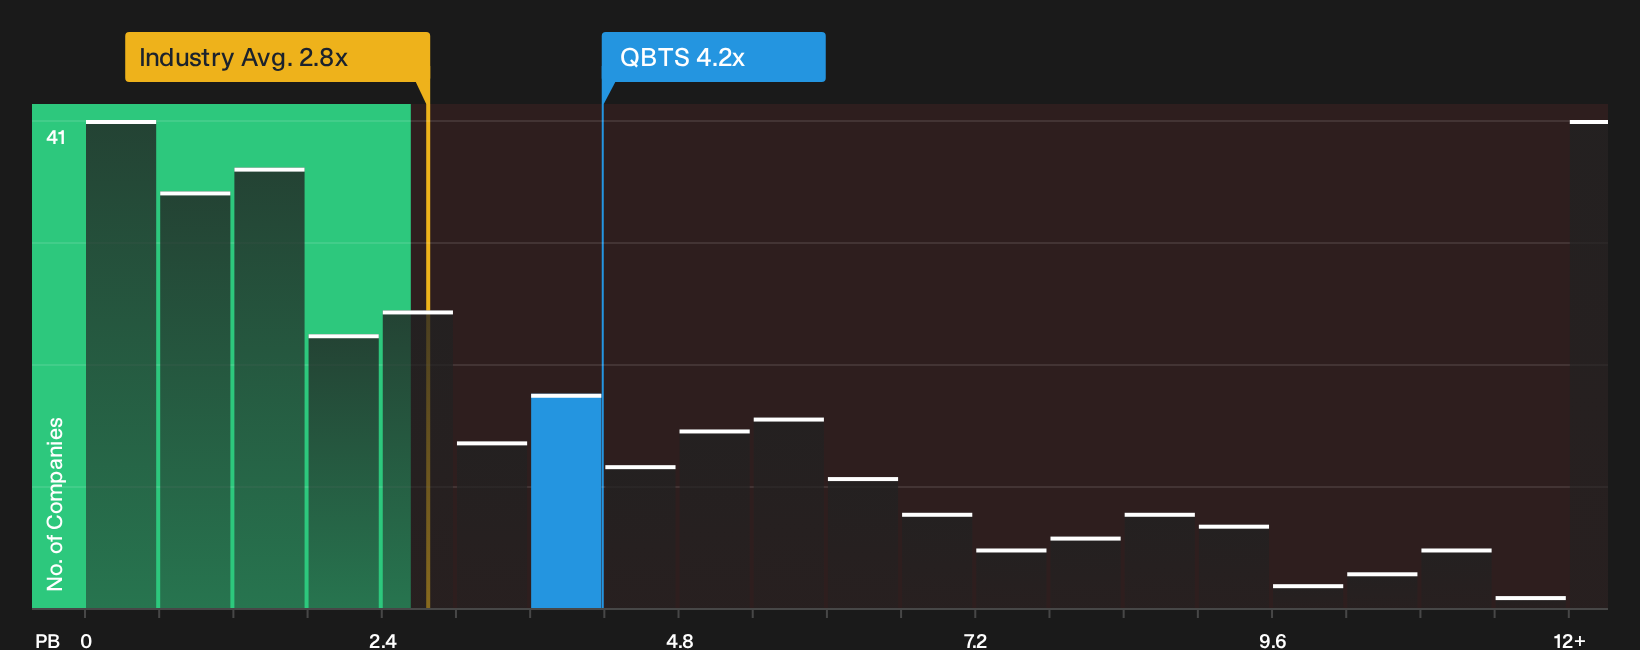
P/B suits D-Wave Quantum because the business is still loss making and book value gives you a cleaner anchor than earnings. The current P/B of about 4.2x sits above the wider software sector, where the average is roughly 2.8x, and even more clearly above the peer group level of about 15.0x that bundles in higher multiple software and quantum exposed stocks. On this yardstick the shares screen as overvalued against the broader industry backdrop.
Because the recent Advantage2 deployment in Italy adds to the story but not yet to the equity base in a material way, you are largely paying a premium to D-Wave Quantum’s current net assets on the expectation that future projects and commercial traction will justify that gap. The question is whether the scale of that P/B mark up fits with your view on the durability of the balance sheet and the funding needs ahead. Explore the numbers behind D-Wave Quantum's P/B valuation.
The D-Wave Quantum Narrative: What Would Justify Today's Price?
D-Wave Quantum Narratives on Simply Wall St pick up where the P/B puzzle leaves off by explaining the future growth, margin and earnings paths that would need to hold for the share price to sit materially above or below today's level, so you can see which assumptions actually carry the valuation. Instead of a single ratio or model output, they show the future story that number relies on, which you can then watch play out over time on the Community page.
One of the top community narratives on D-Wave Quantum: 70% undervalued
"Through a massive $550 million acquisition, a record-breaking month of sales, and a newly fortified balance sheet, D-Wave has moved the 'Quantum Era' off the whiteboards…"
Discover why this Narrative puts D-Wave Quantum at 70% undervalued.
One more D-Wave Quantum check that belongs beside the book value math
Price ratios only tell part of the story for D-Wave Quantum, and the research checks behind this piece have highlighted concerns that deserve your attention before you lean on any single metric. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com