


- Fortuna Mining reported past infill drilling results at the Lindero Mine in Argentina, where 31 diamond drill holes over 8,534 meters confirmed gold mineralization extending well below the current life of mine pit design, with several intervals showing higher than expected grades.
- The drilling focus on both upgrading Inferred Mineral Resources beneath the existing pit and securing metallurgical samples for near term mining areas highlights how Fortuna Mining is working to improve resource quality while testing recovery assumptions that are central to potential future cash generation.
- We will explore how Fortuna Mining's investment narrative is influenced by the deeper, higher grade Lindero infill results and their impact on resources.
Scan beyond Fortuna Mining and uncover other producers with deep drilling upside using our curated list of 35 elite gold producer stocks as a starting point for your next idea.
Fortuna Mining Investment Narrative Recap
To own Fortuna Mining, you need to be comfortable with a concentrated gold producer that is leaning heavily on a handful of assets like Lindero, Séguéla and the future Diamba Sud project. The short term swing factor is whether these operations can keep all in sustaining costs trending down while production stays stable after the San Jose and Yaramoko sales.
The latest Lindero infill results support the idea that Fortuna Mining has more potential mine life and grade leverage in Argentina, but they do not change the immediate catalyst. Execution on expansions and cost savings, against rising capex and political risk in places like Argentina and West Africa, still looks like the main near term risk.
The most relevant recent development is the emphasis on expansion at Séguéla in Côte d’Ivoire and the early stage work at Diamba Sud in Senegal. Together with Lindero, these projects shape how quickly Fortuna Mining can restore and then exceed the production lost from the mine divestments while trying to improve the quality of ounces.
Lindero drilling that confirms mineralization below the current pit ties directly into that story. If Séguéla and Diamba Sud progress on time and on budget, deeper mineralization at Lindero gives Fortuna Mining more optionality on where to allocate capital and how to manage high reported AISC, which remains a central execution and margin risk.
Fortuna Mining's current analyst narrative points to $2.3b in revenue and $771.8 million in earnings by 2029, based on a 24.1% yearly revenue growth assumption and an earnings increase of about $393.6 million from $378.2 million today.
Uncover how Fortuna Mining's fair value indicates a 45% potential upside to its current price that may not last much longer.
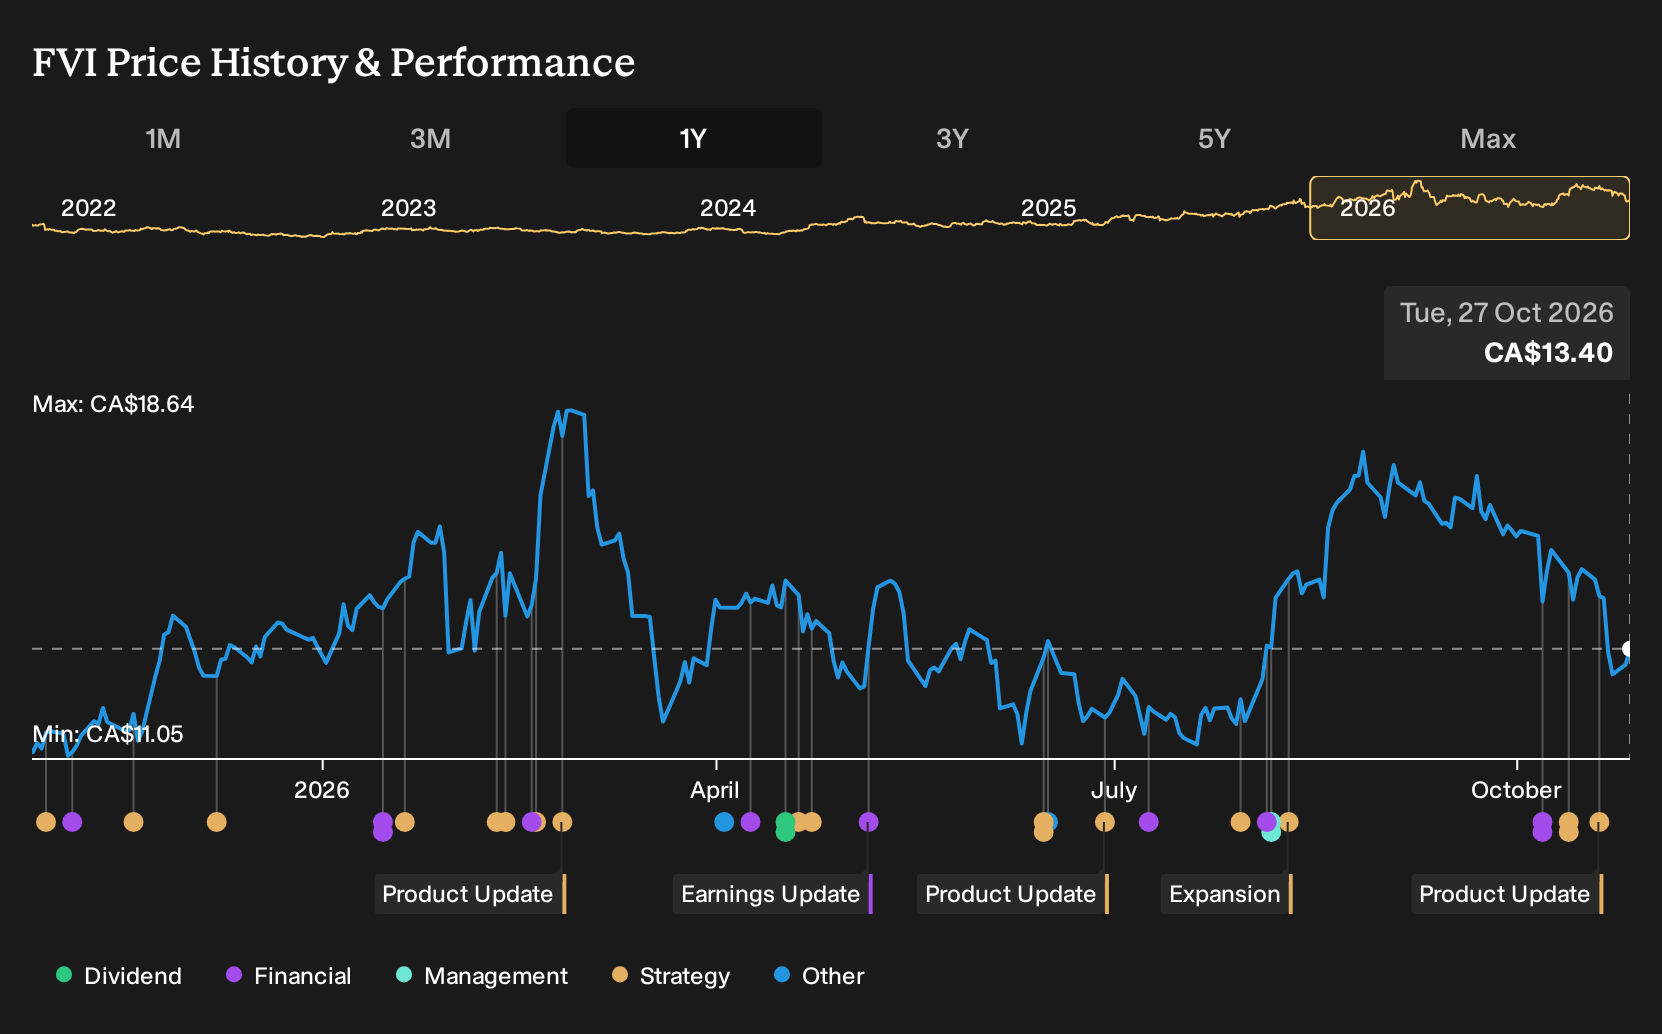
Exploring Other Perspectives
Some of the most optimistic analysts frame Lindero as a side story and focus instead on Diamba Sud as the real swing factor for Fortuna Mining. Before this drilling news, that group was already sketching out revenue of about $2.4b and earnings near $817.6 million by 2029. You can compare that outlook with your own view and decide whether fresh drill data eventually pushes those forecasts higher or pulls them back.
Explore 4 other Fortuna Mining fair value estimates, including one that suggests as much as 263% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Following the herd rarely leads to extraordinary investment returns, so consider trusting your own analysis.
- A great starting point for your Fortuna Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fortuna Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortuna Mining's overall financial health at a glance.
Looking For More Ideas Beyond Fortuna Mining?
If the Fortuna Mining story has sharpened your thinking, use that momentum to widen your opportunity set with a few targeted screens on Simply Wall St.
- If you want companies that trade below their assessed worth with solid fundamentals, start with our 3 high quality undervalued stocks as a way to spot potential mispricings.
- If resilience matters more to you than excitement, consider focusing on our 8 resilient stocks with low risk scores to see businesses with steadier risk profiles.
- If you prefer balance sheets that can handle rougher conditions, shortlist ideas from our list of solid balance sheet and fundamentals (7 results) and then compare them against your own criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com