


Parker-Hannifin (PH) heads into its fiscal first quarter 2027 earnings on Thursday, Nov. 5, with expectations for $8.23 in diluted EPS and a projected 14% year-over-year increase.
Parker-Hannifin’s share price has eased in the short term, with a 7-day share price return down 4.7% and a 30-day move down 7.9%. The latest close at $900.73 sits alongside a 1-year total shareholder return of 18.4% and a 3-year total shareholder return above 150%, so long term momentum remains intact while near term enthusiasm has cooled ahead of earnings.
Scan beyond Parker-Hannifin’s earnings setup and size up other industrial compounders through our hand picked list of solid balance sheet and fundamentals (24 results) for ideas with similar resilience.
Parker-Hannifin has pulled back after a strong multi year run, yet still carries expectations of solid profitability and growth. Does that recent dip offer a fair entry now, or is patience on price the better move before earnings?
Most Popular Narrative: 23% Undervalued
The most followed valuation storyline pegs Parker-Hannifin’s fair value at $1,163, which is above the recent $900.73 close, so the gap between price and narrative remains wide heading into earnings.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 48 investors see Parker-Hannifin as 23% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, the Parker-Hannifin story can be challenged if recent 3.2% organic growth persists and premium P/E expectations encounter softer industrial demand or slower aerospace conversion.
Find out about the key risks to this Parker-Hannifin narrative.
Another View: What Multiples Say About Parker-Hannifin
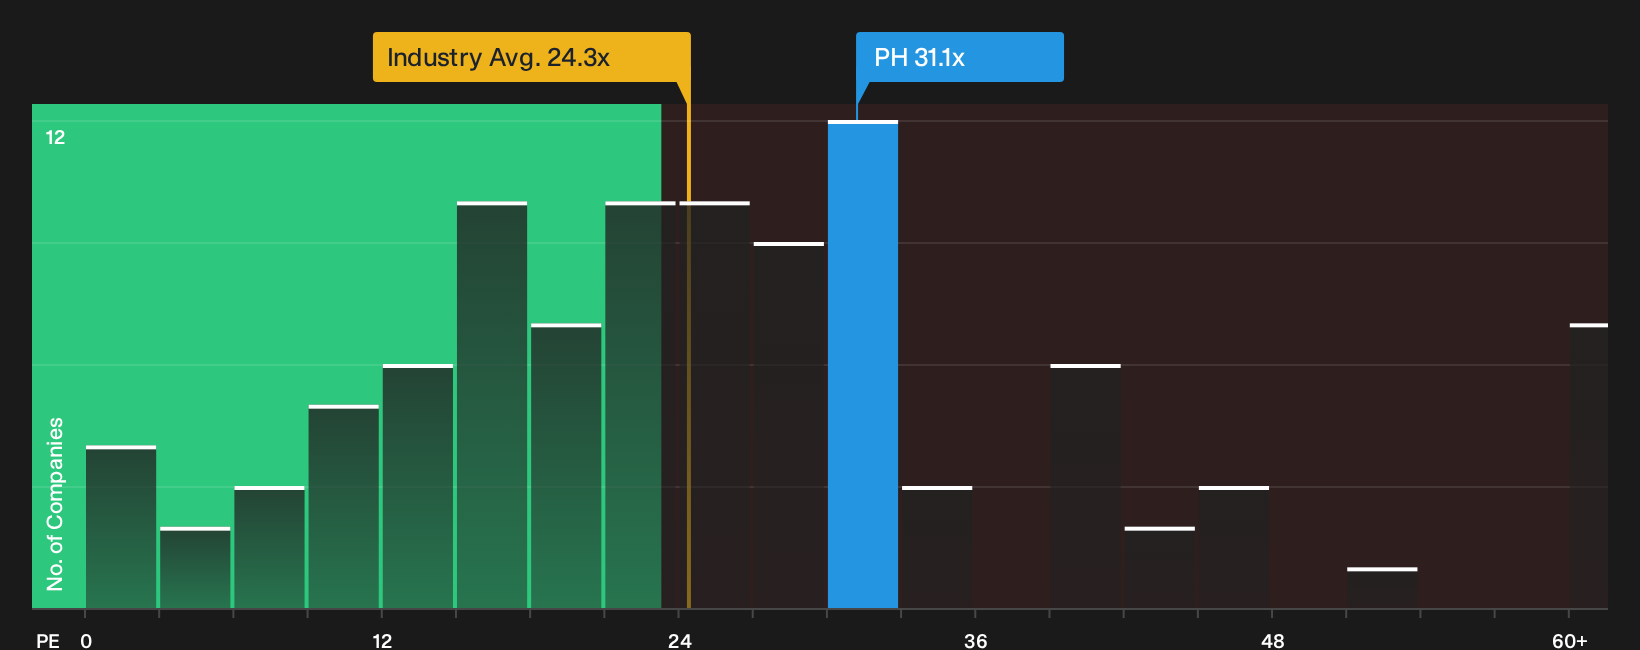
On simple earnings multiples, Parker-Hannifin looks rich. The shares trade on a P/E of 31.1x versus an estimated fair ratio of 28.5x and a US Machinery average of 24.3x, which points to higher valuation risk if growth or margins do not keep pace with expectations.
That premium can make sense if you believe Parker-Hannifin’s quality and execution justify paying well above both peers and the fair ratio. It also raises the question of how much margin for error is left if the industrial cycle stays slower for longer.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Parker-Hannifin so far. If you want to move before the next set of headlines lands, consider the trade-off between potential upside and risk by reviewing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Parker-Hannifin?
Do not stop at Parker-Hannifin. Use the Simply Wall Street screener to explore additional candidates and broaden your opportunity set.
- Explore the 29 high quality undervalued stocks to identify quality companies that may be trading below their estimated worth.
- Use the 5 dividend fortresses to focus on businesses that offer higher dividend yields supported by their fundamentals.
- Consider the 30 resilient stocks with low risk scores to find businesses with comparatively stronger balance sheets and more stable financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com